

UiPath Reports Thursday With Its Own Guidance Implying 8.5% Growth After a 17.3% Quarter
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
UiPath's shares have risen by half since late July without the company publishing a single new financial figure. Everything the market repriced was disclosed on May 28: net new annual recurring revenue nearly doubled to $49m from $27m a year earlier, dollar-based net retention rose to 109% from 108%, and customers paying more than $1m a year grew 18% to 374.
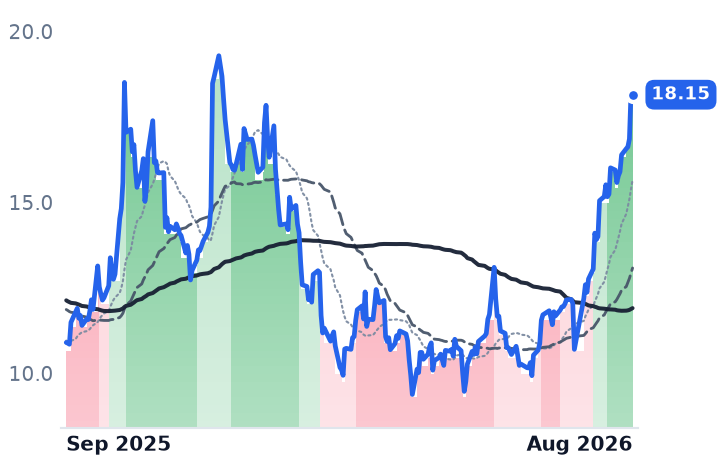
The direction of the business confirms. The timing does not. UiPath's own raised full-year revenue guidance leaves roughly $1.36bn for the final three quarters against $1.25bn a year earlier — about 8.5% growth, against the 17.3% just reported. Trailing price to gross profit has gone from 4.55x in late July to 6.96x, an expansion that arrived alongside a sector-wide software bid rather than any UiPath disclosure. Thursday's second-quarter print is the first test that can settle it.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
PATH | UiPath | Business Software & Automation | 🔴 Cont. Bear | +42.2% | +66.5% |
| Compared against · context, not the story | |||||
AVPT | AvePoint | Business Software & Automation | 🌱 Emerging Bull | +7.4% | −13.8% |
SPSC | SPS Commerce | Business Software & Automation | 🔴 Cont. Bear | +15.7% | −20.4% |
CCC | CCC Intelligent Solutions | Business Software & Automation | 🌱 Emerging Bull | +23.0% | −23.6% |
CRM | Salesforce | Customer Experience & CRM | 🔴 Cont. Bear | +39.1% | +2.1% |
NOW | ServiceNow | Specialized Enterprise Solutions | 🌱 Emerging Bull | +30.1% | −20.6% |
MSFT | Microsoft | Cloud Infrastructure & Platforms | 🔴 Cont. Bear | +10.5% | +2.1% |
PEGA | Pegasystems | Low-Code & Process Automation | 🔴 Cont. Bear | +18.4% | −32.5% |
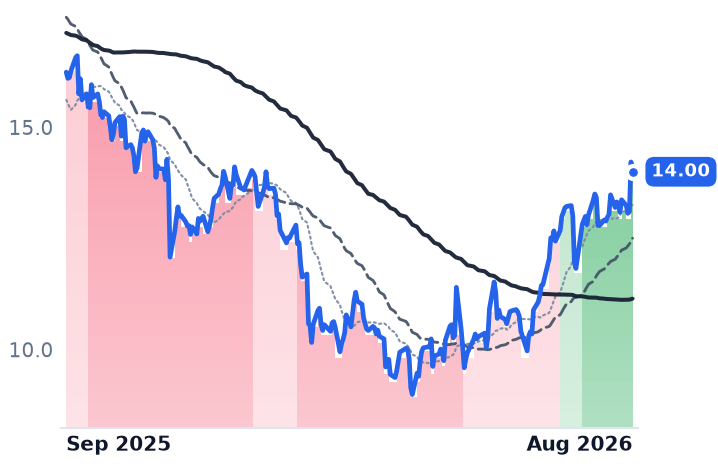
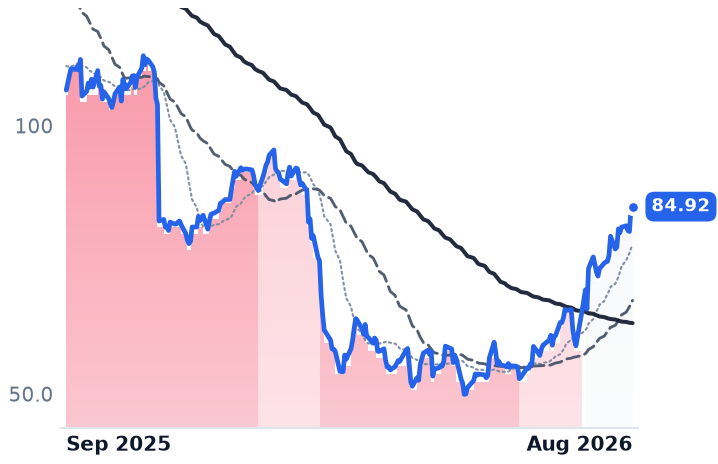
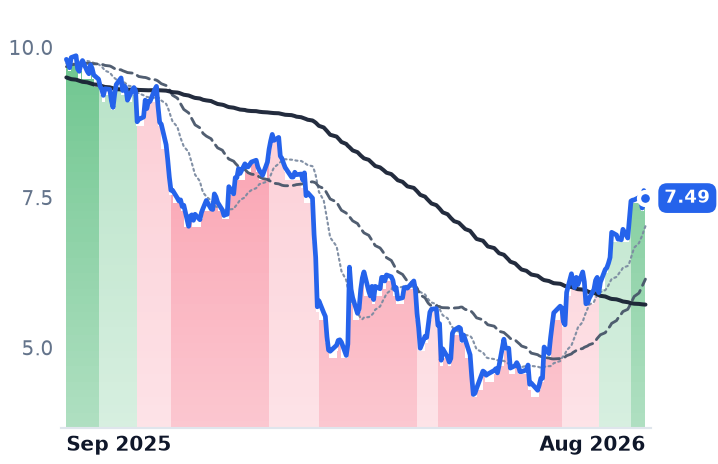
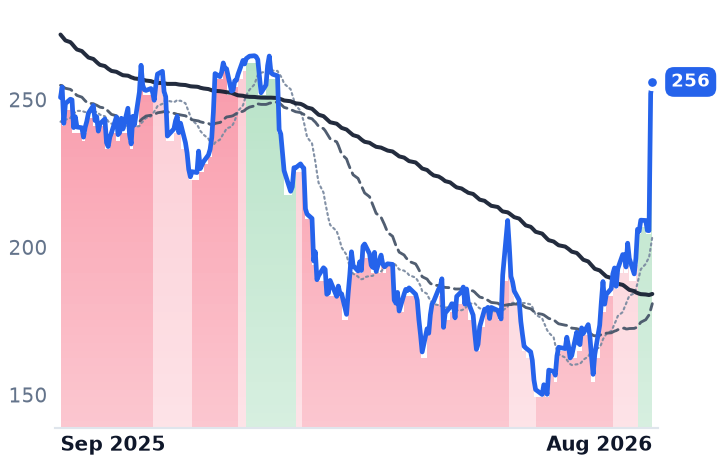
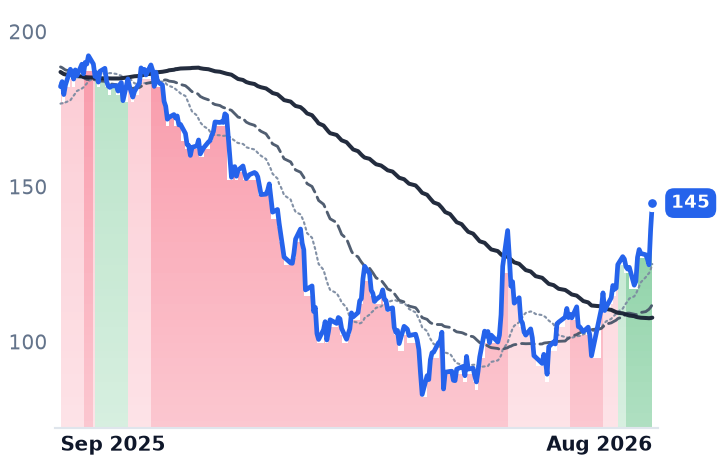
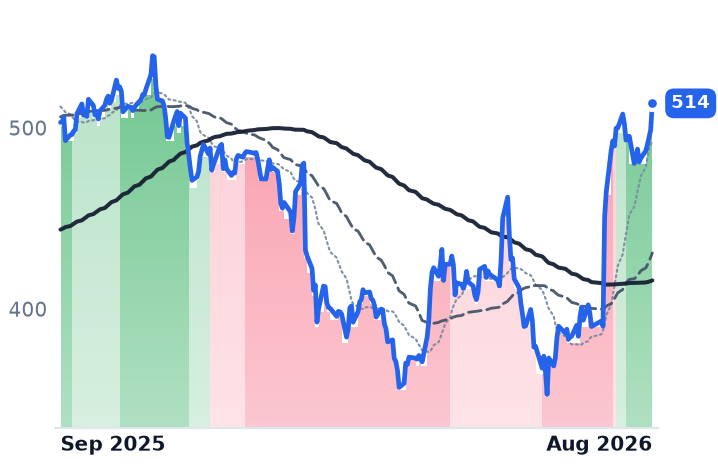
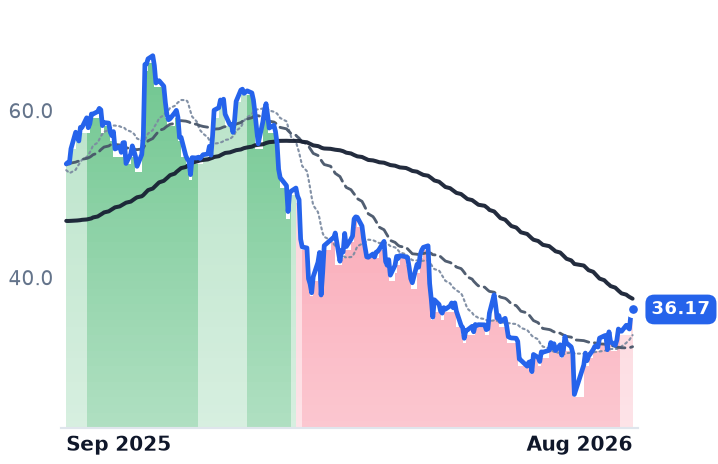
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
PATH | $9.7B | 30.1x | 23.2x | 5.8x | 5.4x | 7.0x | 6.5x | 56.8x | 3.9% |
AVPT | $2.8B | 40.0x | 29.8x | 6.1x | 5.6x | 8.3x | 7.6x | 34.0x | 3.6% |
SPSC | $2.9B | 39.0x | 16.5x | 3.8x | 3.7x | 5.4x | 5.3x | 15.0x | 6.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CCC | $4.1B | 105.6x | 15.5x | 3.7x | 3.5x | 5.0x | 4.8x | 16.9x | 7.5% |
CRM | $209.7B | 23.3x | 15.8x | 4.8x | 4.5x | 6.2x | 5.9x | 15.4x | 7.2% |
NOW | $132.8B | 79.8x | 31.6x | 9.0x | 8.2x | 12.1x | 11.0x | 39.8x | 3.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MSFT | $3.8T | 28.6x | 26.1x | 11.5x | 9.8x | 17.0x | 14.4x | 19.0x | 1.7% |
PEGA | $5.9B | 18.9x | 14.6x | 3.4x | 3.1x | 4.5x | 4.1x | 29.3x | 8.5% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
PATH | Revenue | +11.4% | +11.5% | +8.4% |
| EPS | +40.5% | +16.2% | +15.2% | |
AVPT | Revenue | +22.9% | +20.5% | +19.7% |
| EPS | +33.4% | +10.4% | +28.6% | |
SPSC | Revenue | +5.1% | +6.3% | +7.2% |
| EPS | +18.8% | +8.6% | +13.3% | |
CCC | Revenue | +10.1% | +8.9% | +8.2% |
| EPS | +25.4% | +16.1% | +13.7% | |
CRM | Revenue | +9.3% | +11.4% | +9.6% |
| EPS | +17.4% | +37.6% | −1.6% | |
NOW | Revenue | +22.4% | +18.7% | +18.6% |
| EPS | +17.1% | +23.2% | +21.4% | |
MSFT | Revenue | +18.0% | +18.6% | +19.5% |
| EPS | +26.7% | +16.0% | +19.0% | |
PEGA | Revenue | +8.8% | +9.2% | +8.7% |
| EPS | +18.0% | +7.8% | +6.2% |
Forward fiscal years only. Blank means no analyst coverage for that year.
UiPath reports second-quarter results after the close on Thursday, September 3, and they will be the first new financial information the company has put out since May 28. Everything the market has repriced in between — a doubling of net new contracted revenue, a first profitable quarter under standard accounting, retention edging up — was on the page three months ago.
What is at stake on Thursday is whether the deceleration the company itself has guided to actually shows up. UiPath, which sells software robots that run rule-based back-office workflows for banks, insurers, hospital systems and governments, and now sells an orchestration layer above them, raised full-year revenue guidance on May 28 to $1.776–1.781bn. Subtract the $418.4m already booked in the April quarter and roughly $1.36bn is left for the remaining three, against $1.25bn a year earlier — about 8.5% growth, against the 17.3% the April quarter delivered. Annual recurring revenue is guided to roughly 11.2% for the year.
What the May print actually showed
The operating improvement was real. Net new annual recurring revenue came in at $49m against $27m in the same quarter a year earlier; dollar-based net retention reached 109% after 107% in the January quarter; customers above $1m of recurring revenue rose 18% to 374; and operating income of $30.4m replaced a $16.4m loss. Total recurring revenue of $1.901bn still grew only 12%, five points slower than reported revenue — the contracted base is expanding more slowly than the income statement.
The agentic meter is quantified, but not isolated
UiPath does attach dollars to artificial intelligence: AI product recurring revenue of nearly $200m at the January quarter, roughly 11% of the total. That figure bundles agentic automation, intelligent document processing and the Maestro orchestration layer together, and when an analyst asked for the split, chief executive Daniel Dines declined, saying the company has not provided clear ratios between the components. On the May 28 call Dines said adoption of the agentic and orchestration products had moved "from early experimentation to production deployment", and quantified attach in proxies only: 16 of the top 20 deals included AI, and expansion deals with AI were six times larger than those without. Gross margin fell roughly a point year over year to 81.1%, consistent with cloud and inference cost landing in cost of revenue, though management did not say so.
The competitive socket is priced in public. Microsoft includes Power Automate with its top Microsoft 365 tier for attended automation, but charges $150 per bot per month for unattended desktop-flow execution — the direct substitute for UiPath's core meter, which Microsoft has not made free either. On August 20 UiPath shipped Maestro Flow, an orchestration canvas that runs inside Claude Code, Cursor and GitHub Copilot, with no announced pricing.
What the shares did, and what paid for it
The stock closed at $18.15 on August 28, up 48.9% in a month. Its largest single session, August 27, followed Salesforce's 22% day, which lifted Adobe, Autodesk and ServiceNow alike; UiPath disclosed nothing. Trailing price to gross profit is 6.96x against 4.55x in late July, and the forward earnings multiple of 23.2x sits on consensus that has revenue growth slowing to 8.4% next fiscal year. Meanwhile the company repurchased 20.4m shares at an average $11.47, about $234m, in a quarter that generated $131.9m of operating cash, funded from balance-sheet cash and cutting the diluted share count 3.8%.
The verdict splits by date. The business earns the direction — retention up two points off the January low, customers paying more than $1m a year growing faster than the base, profitability at the operating line — and that is a genuine answer to the argument that language-model agents eat rule-based automation. It does not earn the re-rating's timing or its size, because none of it is new, and management's own arithmetic guides the next three quarters to roughly half the growth rate of the last one. Thursday can move either way: a recurring-revenue line above the guided path would be company-specific evidence, while anything at or below it leaves the price resting on a software bid that began with someone else's earnings.
As of August 25, with the shares at $16.57, the average published analyst price target was $13.53. The stock cleared the top of that range before the numbers arrived.