

Strip Out Informatica and Salesforce Grew 6.4%, Not 10.8%
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Salesforce's best trading day since 2020 came the morning after a quarter whose headline growth it had partly purchased. Informatica, closed this year and absent from the year-ago base, supplied $456m of the $11.3bn reported — roughly four points of growth. The seat-billed core Salesforce now calls Agentforce Apps grew 8% in constant currency, gross margin fell to 76.65%, and GAAP operating income was flat.
Non-GAAP earnings of $5.90 a share included $2.53 from gains on strategic investments, chiefly an unrealized mark on the company's Anthropic stake. What is genuinely strong sits in the backlog: current remaining performance obligation of $33.5bn grew 14% in constant currency, three points faster than revenue. The income statement does not show it yet.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
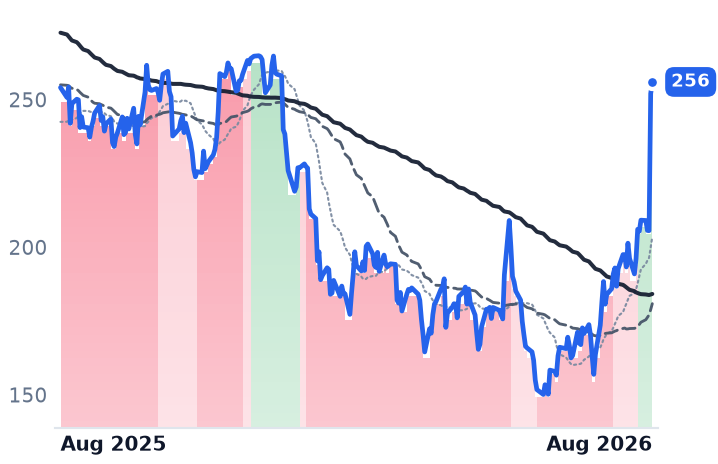
CRM | Salesforce | Customer Experience & CRM | 🔴 Cont. Bear | +41.7% | +0.7% |
| Compared against · context, not the story | |||||
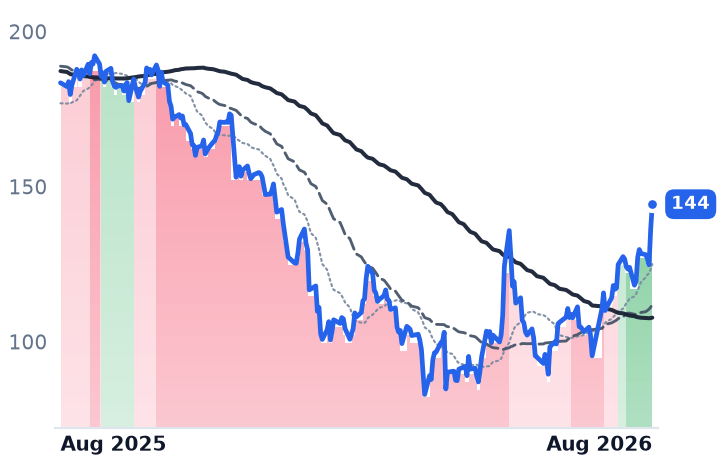
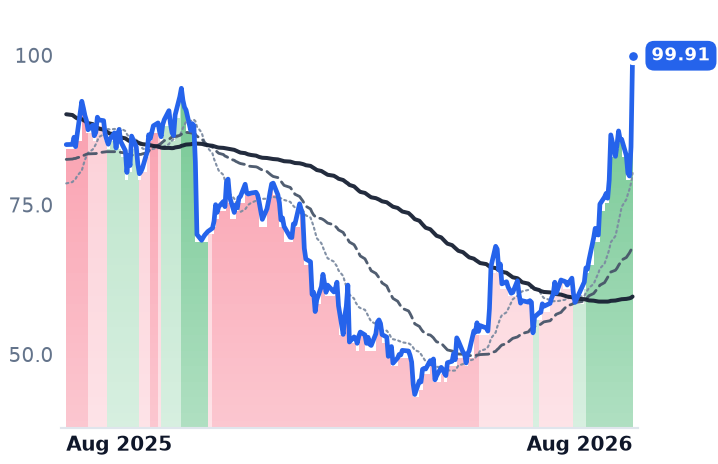
NOW | ServiceNow | Specialized Enterprise Solutions | 🌱 Emerging Bull | +31.1% | −21.3% |
MSFT | Microsoft | Cloud Infrastructure & Platforms | 🔴 Cont. Bear | +14.1% | +2.0% |
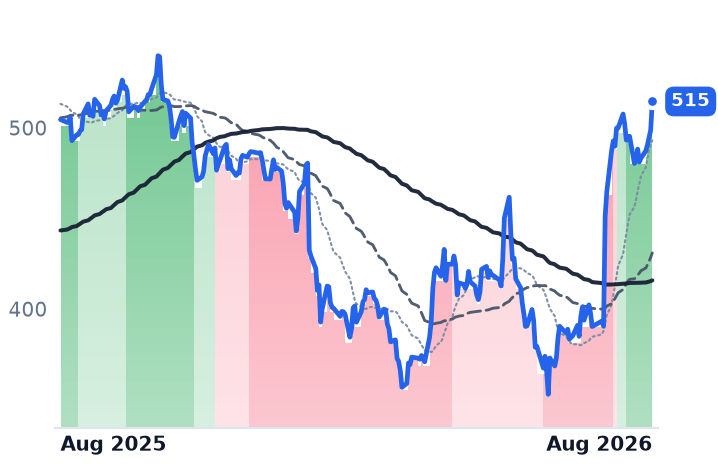
TEAM | Atlassian | Developer Tools & DevOps | 🔴 Cont. Bear | +96.6% | +8.5% |
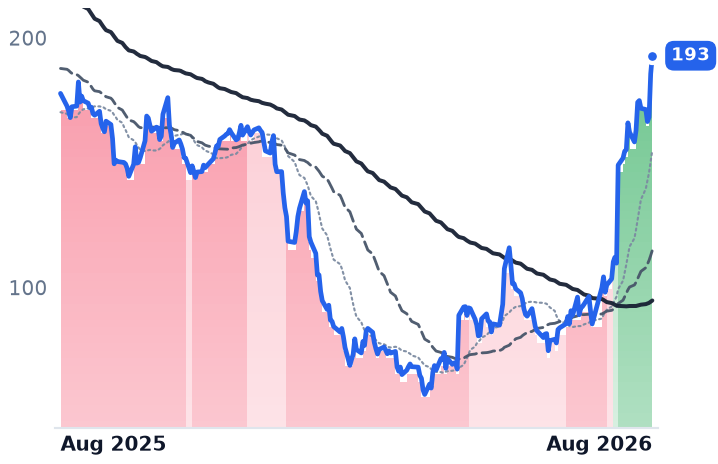
OKTA | Okta | Identity & Access Management | 🌱 Emerging Bull | +18.4% | +79.2% |
ESTC | Elastic | Data & Analytics Platforms | 🌱 Emerging Bull | +55.5% | +17.5% |
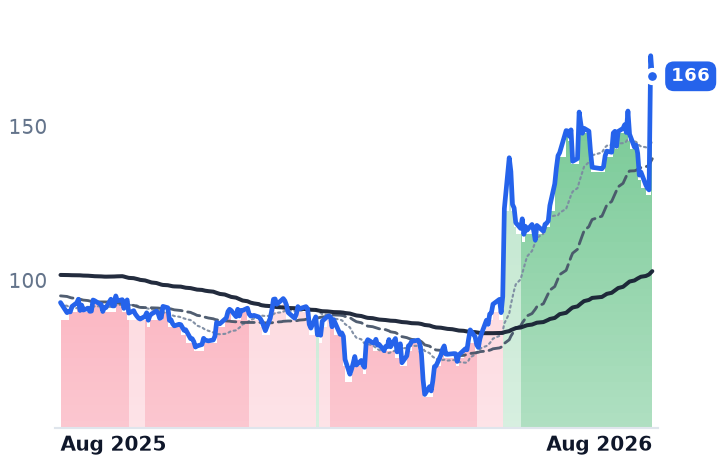
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CRM | $209.7B | 23.3x | 15.8x | 4.8x | 4.5x | 6.2x | 5.9x | 15.4x | 7.2% |
NOW | $132.8B | 79.8x | 31.6x | 9.0x | 8.2x | 12.1x | 11.0x | 39.8x | 3.4% |
MSFT | $3.8T | 28.6x | 26.1x | 11.5x | 9.8x | 17.0x | 14.4x | 19.0x | 1.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TEAM | $50.0B | n/m | 34.6x | 7.6x | 6.7x | 9.0x | 7.9x | 331.1x | 2.6% |
OKTA | $27.6B | 98.4x | 43.2x | 9.0x | 8.6x | 11.5x | 11.0x | 68.3x | 3.5% |
ESTC | $10.4B | 27.6x | 30.8x | 5.8x | 5.2x | 7.6x | 6.9x | 159.3x | 3.4% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
CRM | Revenue | +9.3% | +11.4% | +9.6% |
| EPS | +17.4% | +37.6% | −1.6% | |
NOW | Revenue | +22.4% | +18.7% | +18.6% |
| EPS | +17.1% | +23.2% | +21.4% | |
MSFT | Revenue | +18.0% | +18.6% | +19.5% |
| EPS | +26.7% | +16.0% | +19.0% | |
TEAM | Revenue | +24.7% | +15.4% | +14.7% |
| EPS | +55.5% | −0.1% | +21.6% | |
OKTA | Revenue | +12.0% | +10.0% | +9.5% |
| EPS | +24.3% | +11.7% | +10.9% | |
ESTC | Revenue | +17.6% | +15.0% | +14.5% |
| EPS | +30.3% | +28.2% | +18.8% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Salesforce bought a good part of its revenue growth last quarter. Informatica, the data-integration business it acquired and which was not in the year-ago base, contributed $456m of the $11.3bn the company reported on 26 August. Back that out of the reported figure and revenue grew about 6.4% against the 10.8% headline — a deceleration from the 13.3% posted in the April quarter, not the reacceleration the following session's 22.6% jump implied.
That session is why the composition matters. Salesforce, which sells sales-pipeline, customer-service, marketing, commerce and Slack collaboration software to enterprises and has historically billed by the seat, is the largest live test of whether agentic artificial intelligence adds revenue to an applications vendor or eats the seats it is sold against. The market answered on 27 August, before the answer is in the accounts.
The new segments hide the old question
Effective this fiscal year Salesforce stopped reporting Sales, Service, Platform and Marketing & Commerce separately. Its quarterly filing now splits subscription revenue two ways: "Agentforce Apps" — the seat-billed core of Sales, Service, Marketing, Commerce and Slack — at $7.2bn, up 8% in constant currency, and "Data 360, Headless Platform and Other" at $3.6bn, up 20%. The faster of the two is where Informatica's $440m of subscription revenue landed. Arithmetic on the disclosed figures leaves the rest of that line growing in the mid single digits. Neither reported segment grew organically faster than high single digits.
The earnings line was flattered from a different direction. Of $5.90 in non-GAAP diluted earnings per share, $2.53 came from gains on strategic investments, with roughly $2.7bn of unrealized gains attributed to the Anthropic stake. Excluding them leaves about $3.37 against a $3.27 consensus — an operating beat of some 3%. Gross margin fell to 76.65% from 78.10%, so gross profit grew more slowly than revenue, and GAAP operating income was flat at $2.3bn.
What is actually working is forward
Current remaining performance obligation — contracted revenue due within a year — reached $33.5bn, up 14% in constant currency, three points ahead of revenue and what management called the fastest bookings growth in four years. Agentforce annual recurring revenue passed $1.5bn, up over 240%, though the definition was widened this quarter to include Slackbot and other AI offerings, so that growth rate is not measured against a fixed product perimeter. It is still recurring-revenue arithmetic and customer counts rather than a revenue line.
The raise tells the same story. Full-year guidance went to $46.1bn–$46.4bn; of the $300m constant-currency increase, $200m is the pending Contentful and Fin acquisitions — Fin, the customer-agent company formerly called Intercom, at about $3.6bn — and $100m organic.
The other half of the session was Anthropic. "The number one AI in the world, Anthropic, and the number one CRM, Salesforce, coming together for the first time in an incredibly powerful way to build a new product called Claudeforce," Marc Benioff, chief executive, told investors on the 26 August call. Claudeforce puts Salesforce records and workflows inside Anthropic's Claude interface and makes Claude the default model across Slack and core products. "This SaaSpocalypse narrative has been such nonsense," Benioff said on CNBC the same day.
The re-rating did the work
Trailing four-quarter gross profit rose 2.1% when the new quarter replaced the year-ago one. The shares rose 22.6%. Price-to-trailing-gross-profit went from roughly 5.0x to 6.17x in a session, the top of its own range this year and up from 4.47x in late July. It remains far below ServiceNow, the workflow-automation platform now selling a customer-relationship product of its own, at 12.06x, and Microsoft at 16.98x. The 15.8x forward earnings looks cheaper than either — but that multiple rests on a fiscal 2027 consensus that embeds this quarter's investment gains; consensus has earnings per share falling 1.6% to $15.94 the following year.
So the backlog and the bookings earn some of this. Nothing in the income statement does. Organic growth slowed, both margins compressed, and the earnings beat net of an investment mark was three cents' worth of operating performance. What the market bought on 27 August was the forward book and a distribution deal.
That deal is the part worth watching, and not only for the revenue. Claudeforce makes the salesperson's habit form in Anthropic's window, with Salesforce's data supplied to it. General availability comes in September at Dreamforce.