

Snowflake and MongoDB Report This Week With Backlog Outgrowing Consumed Revenue
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Two data platforms that bill by the credit and the gigabyte have re-rated hard through a summer in which neither published a financial statement. Both fix that this week: MongoDB after the close on Tuesday, Snowflake on Wednesday.
The April quarters were strong — Snowflake's product revenue grew 34%, a third straight quarter of acceleration, and MongoDB's Atlas added a record $117m of year-on-year revenue to reach 75% of the total. But what is contracted is outrunning what is burned: MongoDB's remaining performance obligations grew 88% against 25% revenue growth. And the only dollar figure either company has ever attached to artificial-intelligence usage is Snowflake's $100m annualized run-rate, disclosed last December.
The businesses earn a re-rating. Nothing disclosed yet explains its pace.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
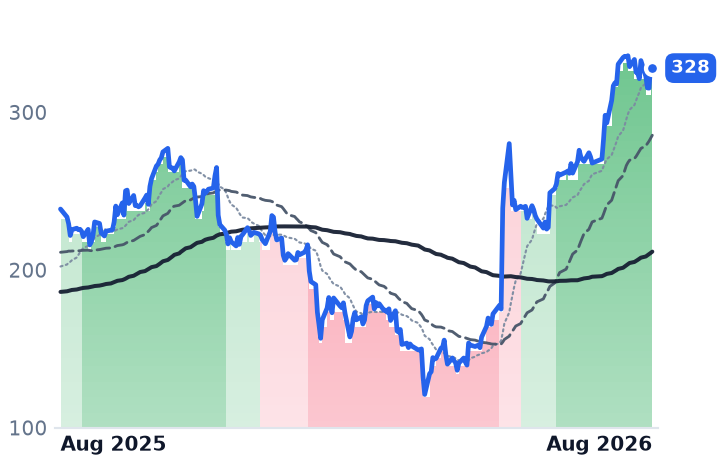
SNOW | Snowflake | Data & Analytics Platforms | 🌱 Emerging Bull | +10.0% | +37.4% |
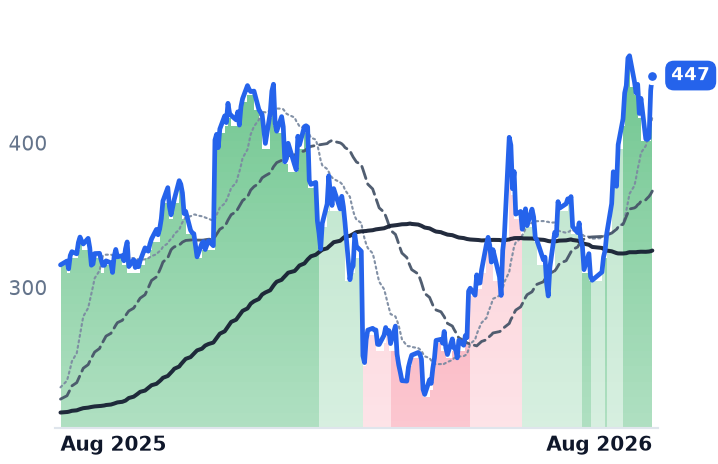
MDB | MongoDB | Data Management & Analytics | 🟢 Cont. Bull | +37.1% | +41.5% |
| Compared against · context, not the story | |||||
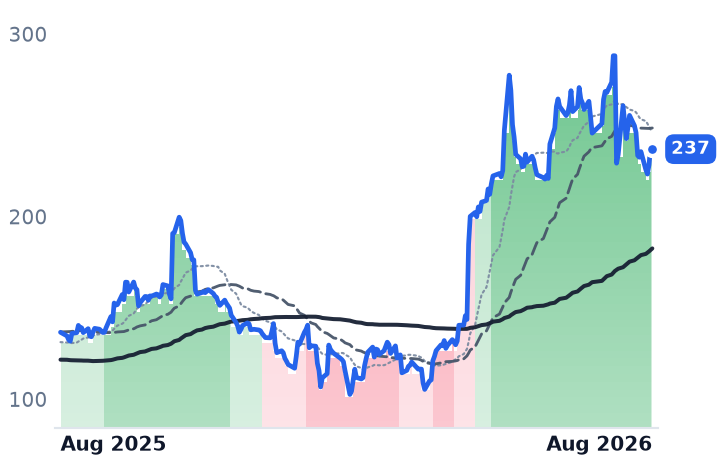
DDOG | Datadog | Data & Analytics Platforms | 🌱 Emerging Bull | −11.8% | +73.4% |
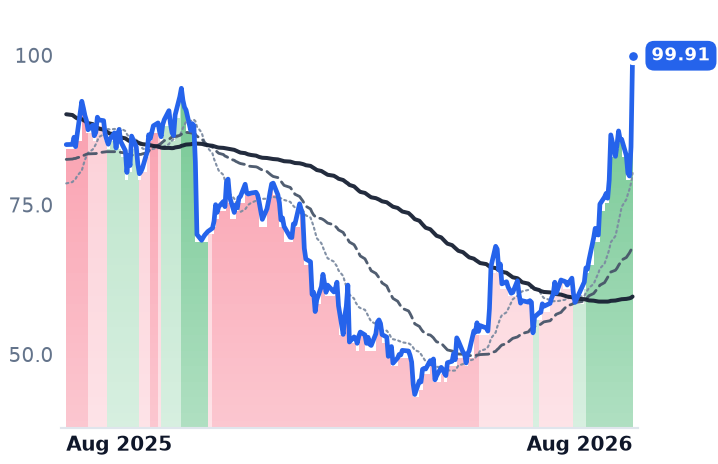
ESTC | Elastic | Data & Analytics Platforms | 🌱 Emerging Bull | +55.5% | +17.5% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SNOW | $113.7B | n/m | 169.5x | 22.6x | 18.6x | 33.6x | 27.7x | n/m | 1.0% |
MDB | $35.9B | n/m | 72.9x | 13.8x | 12.1x | 19.2x | 16.8x | — | 1.7% |
DDOG | $86.5B | 488.6x | 96.0x | 21.8x | 19.4x | 27.4x | 24.3x | 331.7x | 1.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ESTC | $10.4B | 27.6x | 30.8x | 5.8x | 5.2x | 7.6x | 6.9x | 159.3x | 3.4% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
SNOW | Revenue | +29.4% | +31.1% | +26.0% |
| EPS | +72.3% | +59.6% | +42.0% | |
MDB | Revenue | +23.1% | +21.5% | +18.0% |
| EPS | +59.1% | +27.3% | +19.7% | |
DDOG | Revenue | +31.7% | +22.3% | +22.9% |
| EPS | +25.3% | +17.0% | +22.2% | |
ESTC | Revenue | +17.6% | +15.0% | +14.5% |
| EPS | +30.3% | +28.2% | +18.8% |
Forward fiscal years only. Blank means no analyst coverage for that year.
MongoDB's July quarter lands after the close on Tuesday, the first financial statement the document-database company has published since late May. Snowflake, which sells the consumption-billed Data Cloud, follows a day later. Between the two prints sits every dollar of a summer re-rating that arrived without a single new disclosure.
That is the stake. Both companies bill by usage rather than by the employee seat, which means production artificial-intelligence workloads either show up as consumed revenue or they do not. The market has spent three months deciding they will. Snowflake now trades at 33.6 times trailing gross profit, against roughly 28x at the end of July and about 15.7x in early May. MongoDB has gone from 13.3x to 19.2x since late July — a 44% re-rating in a month against zero new financials. Neither company earns a meaningful profit, so gross profit is what there is to price.
The April quarters were good
Snowflake's product revenue reached $1.334bn in the quarter ended 30 April, up 34% year on year and accelerating for a third consecutive quarter. Net revenue retention rose to 126%, and customers spending more than $1m a year numbered 779, growing 29% while total customers grew about 20% — expansion concentrated where the compute is. Management raised the full-year product outlook to $5.84bn, telling investors on 27 May that "based on a combination of strength in our core data platform business and meaningful uplift from AI capabilities, including Coco and Snowflake Intelligence, we are increasing our FY 2027 outlook from 27% to 31% year-over-year growth," according to the call transcript.
MongoDB's Atlas managed-database service grew 29.4% to about $512.5m, a record $117m year-on-year dollar increase that carried it past a $2bn annualized run rate and to 75% of company revenue. One popular bear case can be retired: the self-managed Enterprise Advanced line, whose upfront licence recognition is often blamed for flattering reported growth, grew only 13% to $153.7m. It is a drag on the reported number, not a prop.
Booked is not burned
What both companies have signed is growing faster than what customers have burned. MongoDB's remaining performance obligations — contracted revenue not yet recognized — grew 88% to $1.5bn against 25% revenue growth. Snowflake's reached $9.205bn, up 37.7%, with only about half expected to convert to revenue inside twelve months. Commitments of that shape are a floor under a stock and a promise about future consumption; they are not consumption.
The missing number is a dollar figure for AI. Snowflake quantified adoption in the April quarter only in accounts — more than 13,600 using AI features — and its one disclosed dollar figure remains the $100m annualized AI run-rate from December 2025, roughly 2% of the product guide. MongoDB has disclosed none. Chief executive CJ Desai made the architectural case on the 28 May call — "Agentic workloads need memory that is transactional, high velocity, and able to retrieve the right context at the right time," he told analysts — while UBS analyst Karl Keirstead's customer checks found "limited evidence of material AI pull-through to MongoDB at this time". He raised his target to $460 from $350 on 24 August and kept a Neutral rating.
What the meter does in reverse
Datadog, the observability vendor billed on the same principle, lost a fifth of its value on 6 August after its largest customer, a nine-figure AI account running 17 of its products, renewed at reduced usage. Datadog beat the quarter and raised the full year for a third straight time; third-quarter growth guidance of about 29% was what mattered. Chief executive Olivier Pomel declined to name the client.
The two share moves have different textures. MongoDB's 37% gain over the past 30 sessions is a grind — strip its two best days and 17.6% remains. Snowflake's 10% is not: two sessions, 3 and 27 August, account for essentially all of it. Both sit inside a rotation out of semiconductors and into beaten-down software that has lifted the main software exchange-traded fund about 18% since 23 July.
The verdict splits. The businesses earn a re-rating: accelerating product revenue at Snowflake and record Atlas dollar adds at MongoDB are real, and the margin erosion bears expected is mild — Snowflake held its 75% non-GAAP product gross-margin guide, MongoDB's subscription margin slipped 60 basis points from a year earlier to 77.1%. What nothing yet explains is the pace. No disclosed consumption dollar justifies a 44% multiple expansion in four weeks, and Snowflake's own second-quarter guide of $1.415bn to $1.420bn implies growth stepping down toward 30%. Snowflake has also committed to spend a minimum $6bn with Amazon Web Services over five years, so its own capacity bill is contracted whether or not customers burn theirs.
Datadog's lesson is the one to carry into Tuesday and Wednesday: in a business paid by usage, a single account deciding to consume less is a guidance event. Both of these companies have spent the summer being priced as though nobody will.