

New-Engine Shipments Cut Kawasaki's Aerospace Profit and Held IHI's Segment to 4% Growth
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
The engine aftermarket is booming, and the Japanese partners who own slices of those engines are getting less of it than the group headlines suggest. IHI is paid a fixed percentage of the V2500, the PW1100G geared turbofan and several GE programs without owning a customer, and those two aftermarket positions alone added ¥4.3bn to June-quarter profit. But the same fixed share applies to newly built engines sold on thin build economics, and the delivery ramp diluted the mix.
Kawasaki said it outright: Aerospace Systems profit fell partly on "increased shipments of newly manufactured commercial aircraft engines," while the group's record quarter came from rolling stock, precision machinery and energy. Kratos is the mirror image — no installed base, and guidance for $85–105m of free cash flow use this year to build one, at 29x trailing gross profit against IHI's 7x.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
7013.T | IHI | Industrial - Machinery | ⚠️ Emerging Bear | — | — |
7012.T | Kawasaki Heavy Industries | Conglomerates | ⚠️ Emerging Bear | — | — |
KTOS | Kratos Defense & Security Solutions | Missiles, Weapons & Fire Control | ⚠️ Emerging Bear | +19.4% | −23.5% |
| Compared against · context, not the story | |||||
AVAV | AeroVironment | Unmanned Systems & ISR | 🔴 Cont. Bear | +4.8% | −40.1% |
GE | GE Aerospace | Large Diversified Primes | 🟢 Cont. Bull | −2.1% | +25.2% |
RTX | RTX | Large Diversified Primes | ⚠️ Emerging Bear | −1.9% | +32.4% |
SAF.PA | Safran | Aerospace & Defense | 🟢 Cont. Bull | +1.3% | +20.9% |
RR.L | Rolls-Royce | Aerospace & Defense | 🟢 Cont. Bull | +10.9% | +44.6% |
LMT | Lockheed Martin | Large Diversified Primes | ⚠️ Emerging Bear | −2.1% | +25.6% |
NOC | Northrop Grumman | Large Diversified Primes | ⚠️ Emerging Bear | +1.8% | −6.3% |
LHX | L3Harris Technologies | Avionics & Electronic Systems | ⚠️ Emerging Bear | −11.6% | −4.0% |
HII | Huntington Ingalls Industries | Naval & Shipbuilding | ⚠️ Emerging Bear | +1.7% | +7.6% |
BA | The Boeing | Large Diversified Primes | ⚠️ Emerging Bear | −1.4% | −11.8% |
7011.T | Mitsubishi Heavy Industries | Industrial - Machinery | ⚠️ Emerging Bear | +7.6% | +6.5% |
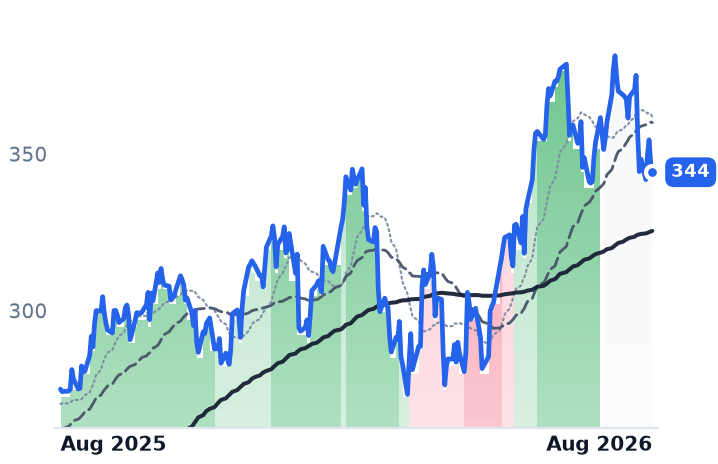
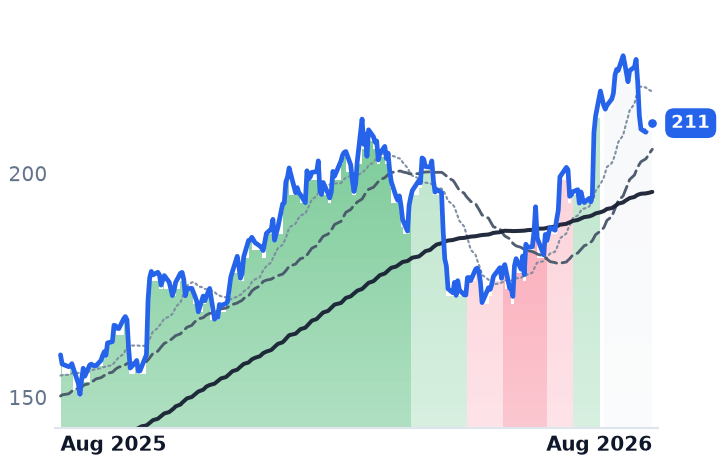
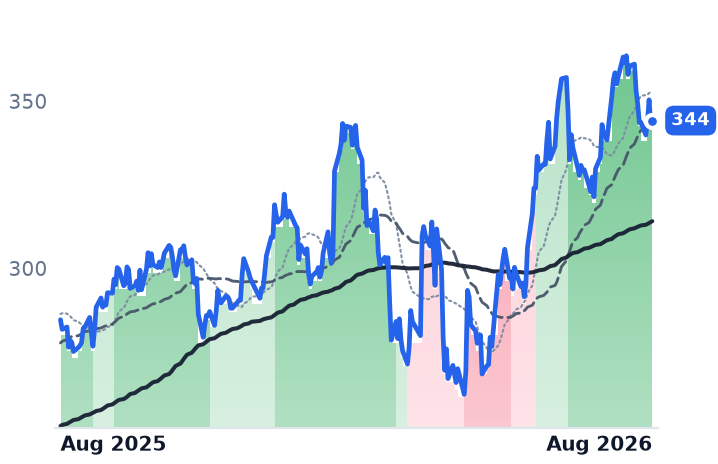
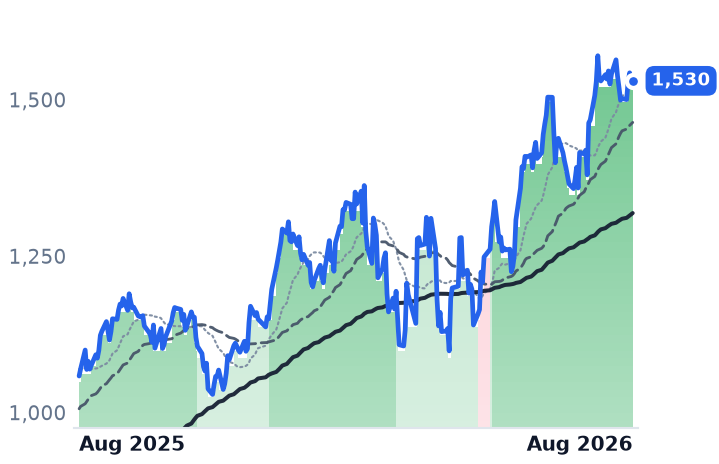
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
7013.T | $2.9T | 14.5x | 16.0x | 1.7x | 1.6x | 7.4x | 6.8x | 11.5x | -0.0% |
7012.T | $2.3T | 18.3x | 18.8x | 1.0x | 0.9x | 4.8x | 4.5x | 11.6x | 0.3% |
KTOS | $9.8B | 302.5x | 62.0x | 6.4x | 5.5x | 29.1x | 24.8x | 71.8x | -1.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AVAV | $7.5B | n/m | 45.6x | 3.8x | 3.4x | 15.0x | 13.5x | n/m | -1.6% |
GE | $355.4B | 40.2x | 43.3x | 7.0x | 7.1x | 19.8x | 19.9x | 29.9x | 1.0% |
RTX | $285.3B | 36.8x | 29.2x | 3.1x | 3.0x | 15.0x | 14.6x | 19.7x | 4.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SAF.PA | $143.4B | 37.0x | 33.1x | 4.3x | 3.9x | 31.3x | 28.8x | 24.3x | 3.6% |
RR.L | $126.5B | 42.5x | — | 5.5x | 5.3x | 19.2x | 18.8x | 19.0x | 3.4% |
LMT | $119.0B | 24.8x | 17.2x | 1.6x | 1.5x | 16.1x | 15.3x | 17.0x | 4.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NOC | $76.8B | 16.8x | 19.3x | 1.8x | 1.7x | 8.8x | 8.5x | 12.2x | 4.3% |
LHX | $51.6B | 27.8x | 23.2x | 2.3x | 2.2x | 8.8x | 8.6x | 16.5x | 5.4% |
HII | $12.9B | 21.2x | 18.8x | 1.0x | 1.0x | 8.0x | 8.0x | 12.9x | 8.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BA | $173.8B | 79.6x | — | 1.9x | 1.8x | 39.2x | 37.0x | 29.7x | -0.6% |
7011.T | $13.5T | 33.9x | 31.3x | 2.7x | 2.4x | 12.3x | 11.0x | 18.2x | 7.1% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
7013.T | Revenue | +2.9% | +11.2% | +5.5% |
| EPS | +29.8% | +43.9% | −14.4% | |
7012.T | Revenue | +7.9% | +9.8% | +6.5% |
| EPS | +17.3% | +24.3% | +18.0% | |
KTOS | Revenue | +34.7% | +23.3% | +21.7% |
| EPS | +57.7% | +34.4% | +28.7% | |
AVAV | Revenue | +140.3% | +15.9% | +15.0% |
| EPS | −5.6% | +13.3% | +37.2% | |
GE | Revenue | +20.6% | +11.1% | +9.2% |
| EPS | +26.7% | +15.0% | +13.9% | |
RTX | Revenue | +10.5% | +7.4% | +7.2% |
| EPS | +16.7% | +9.1% | +10.9% | |
SAF.PA | Revenue | +15.8% | +10.1% | +9.0% |
| EPS | +26.3% | +26.0% | +13.2% | |
RR.L | Revenue | +19.8% | +11.6% | +11.0% |
| EPS | +47.8% | +15.2% | +16.6% | |
LMT | Revenue | +6.1% | +5.4% | +5.5% |
| EPS | +38.4% | +7.1% | +6.2% | |
NOC | Revenue | +5.1% | +6.7% | +6.1% |
| EPS | +7.2% | +7.9% | +8.6% | |
LHX | Revenue | +3.2% | +7.3% | +7.0% |
| EPS | −18.5% | +12.2% | +13.9% | |
HII | Revenue | +7.3% | +6.0% | +6.9% |
| EPS | +14.7% | +16.8% | +16.4% | |
BA | Revenue | +10.8% | +14.6% | +9.6% |
| EPS | −98.6% | −3232.7% | +86.2% | |
7011.T | Revenue | −2.5% | +13.6% | +8.1% |
| EPS | +5.1% | +52.4% | +16.9% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The jet-engine aftermarket boom is not reaching the companies that own pieces of the engines. IHI, the Tokyo-listed heavy-industry group that holds fixed program shares in the IAE V2500, Pratt & Whitney's PW1100G geared turbofan and several GE Aerospace engines, lifted civil-engine revenue 27% to ¥109.4bn in the June quarter; operating profit at the aerospace, space and defense segment that houses it rose from ¥27.9bn to ¥29.1bn, a gain of 4%.
The gap is mechanical. A risk-and-revenue-sharing partner buys a fixed percentage of a program and is paid that percentage on everything the program sells — high-margin spare parts and newly built engines shipped on thin build economics alike. Departures were flat across the first half of 2026 while Safran's civil spare-parts sales rose 27.9% in dollars, and that deeper-repair cycle does flow through to partners automatically, with no customer relationship required. So does the opposite: LEAP deliveries hit a record 1,802 units in 2025 and rose 41% again in the first half of 2026. Owning both sides of that mix is what capped IHI's segment margin and pushed Kawasaki's aerospace profit down.
Paid without a customer, charged the same way
IHI holds workshare on GE's CF34, GE90, GEnx and Passport 20 alongside the V2500 and PW1100G — partner positions across all three Western propulsion primes. The V2500 and PW1100G aftermarket operations alone added ¥4.3bn to the quarter's profit, with spare parts up 15% in dollar terms before currency effects. Group operating profit rose 250.5% to ¥73.2bn and full-year guidance went up to ¥1.84trn of revenue and ¥250bn of operating profit, helped by a roughly ¥40bn property gain. "Operating profit reached a record high even excluding the real estate sale," chief financial officer Hiromi Oshima said on the August 5 call.
The same automatic share is why IHI's accounts once looked like this: in the year to March 2024, gross margin of 10.95%, a ¥70.1bn operating loss and a ¥68.2bn net loss. IHI produces the PW1100G high-pressure rotor, and when the powder-metal contamination defect surfaced it guided to an ¥80bn operating loss in place of a profit forecast. Gross margin has since recovered to 23.09%. A separate unquantified item sits open: subsidiary IHI Aerospace drew a five-month JAXA bidding suspension on June 2 over falsely reported costs.
Kawasaki's good quarter came from everything else
Kawasaki Heavy Industries — military airframes for Japan's defense ministry, rolling stock, robots, motorcycles — holds comparable partner positions, and they were the drag. Aerospace Systems profit fell on "a temporary decline in revenue" and "increased shipments of newly manufactured commercial aircraft engines". The record ¥35.7bn of quarterly business profit and the raise of full-year guidance to ¥180bn came from precision machinery, rolling stock and energy, plus tariff refunds and a weaker yen; powersports guidance was cut. Whatever Kawasaki is at 4.84x trailing gross profit — the cheapest of the three — it is not an aero-propulsion story this year.
Kratos is buying the installed base it doesn't have
Kratos Defense & Security Solutions builds low-cost expendable turbines and unmanned aircraft for the Pentagon, and it is the counter-case: revenue up 30.5% to $458.8m, gross margin down to 21.8%, and a GAAP operating loss of $1.6m. Guidance calls for $125–135m of capital spending and $85–105m of free cash flow use this year. "We are currently placing initial orders with our supply chain for the components for 3,000 small Kratos TDI Spartan turbojet engines," chief executive Eric DeMarco told investors on August 4, at an average selling price near $50,000. The GEK800 turbofan won a military type designation and a development contract as second-source propulsion for the Joint Air-to-Surface Standoff Missile on August 18. The shares fell 15.5% in the eight sessions after. Kratos trades at 29.1x trailing gross profit, roughly double the 14.95x paid for the unmanned-aircraft maker AeroVironment, and it is the only one of the three with no fleet to be paid from.
What the shares did
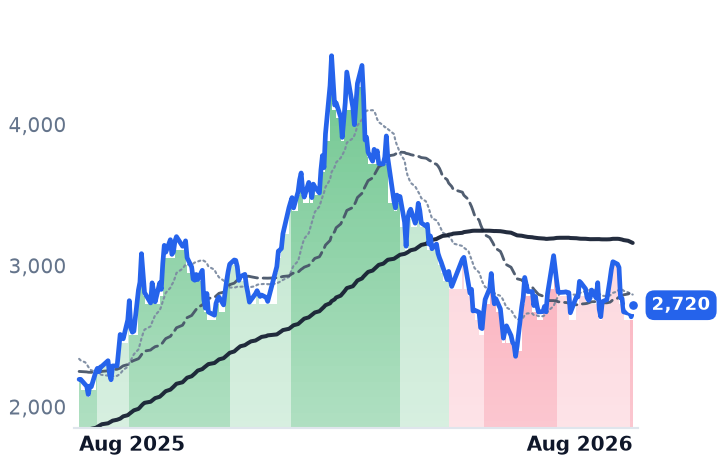
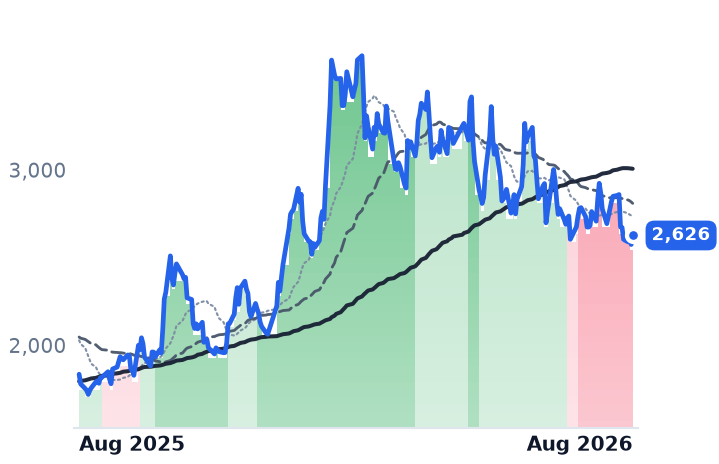
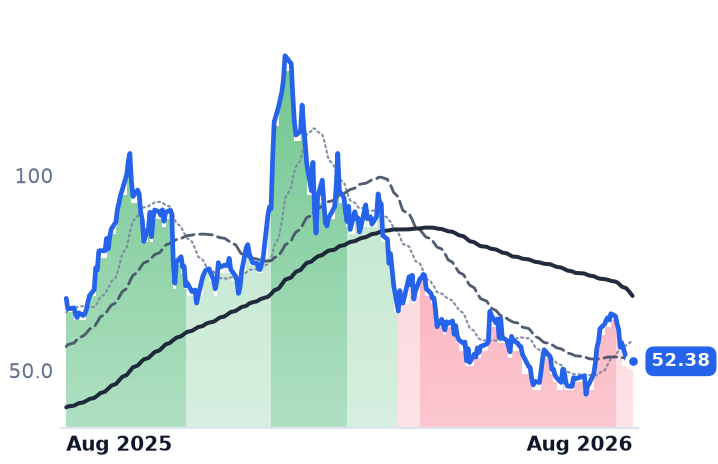
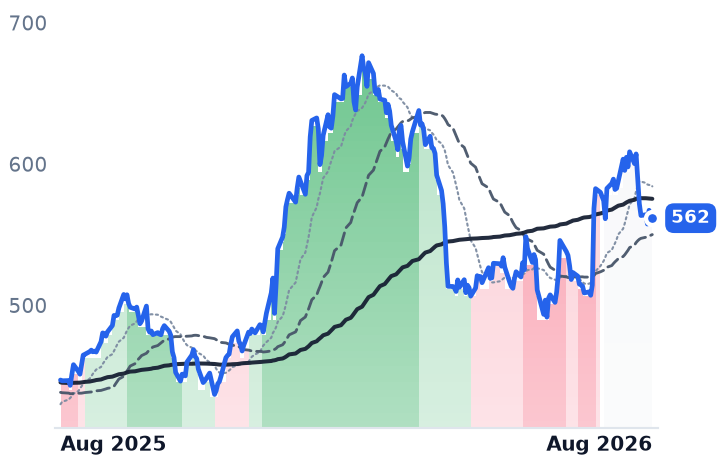
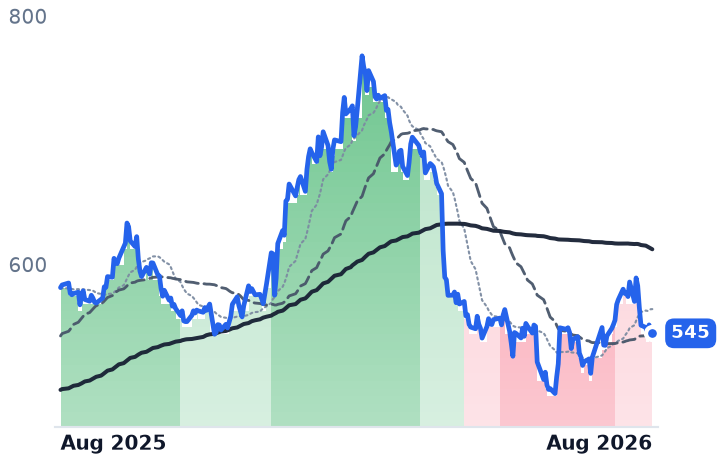
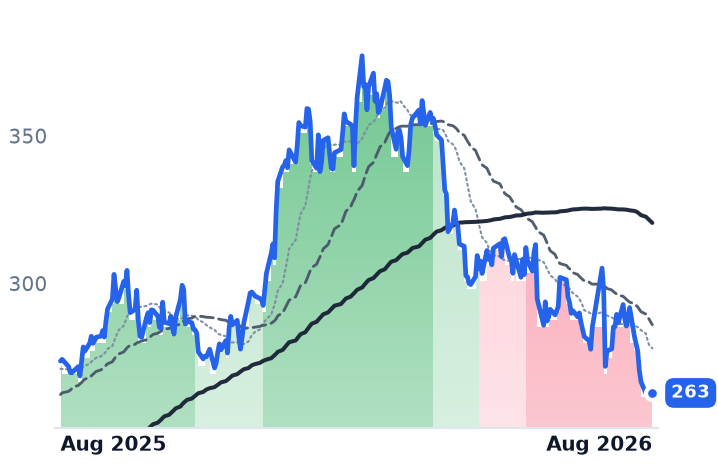
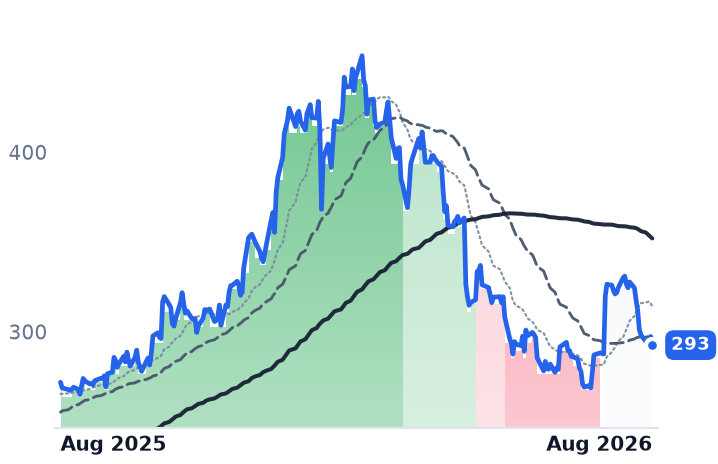
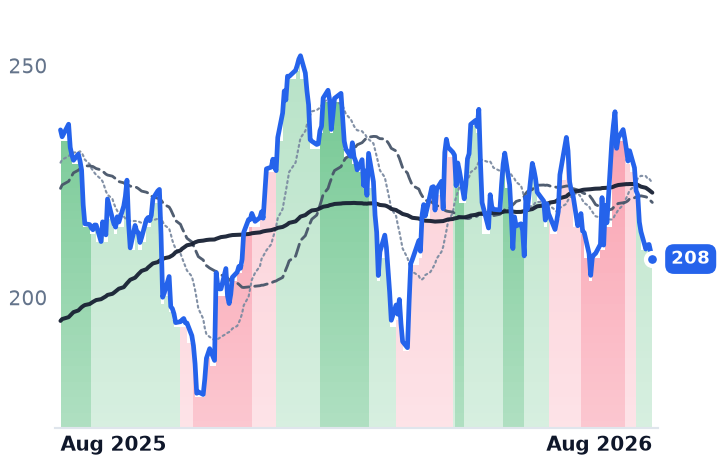
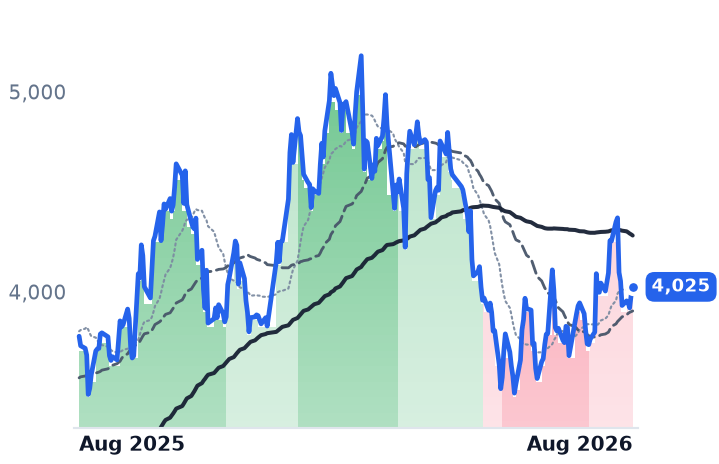
All three fell with the defense complex between August 14 and August 28 — L3Harris down 9.9%, Kratos 18.9%, IHI 10.2%, Kawasaki 8.2%, with AeroVironment the worst at 22.7%. The Japanese names' weakest session was August 19, when the Nikkei 225 fell 3.16% on a broad technology selloff. IHI is 36.8% below its February peak and trades at 15.97x forward earnings against consensus expecting earnings per share up 43.9% in the year to March 2027; Kratos is 43.2% below its own February high at 62x forward earnings.
The verdict the disclosures support is narrow. IHI's aftermarket annuity is real and arrives without effort — but the delivery ramp that is the primes' best news is a margin dilutant one tier down, and the same sentence that trimmed IHI's segment growth turned Kawasaki's aerospace profit negative. Neither Japanese name's August decline is explained by anything either company disclosed.
Being paid automatically means being charged automatically too. When Pratt & Whitney's powder-metal problem surfaced, IHI's share of the remedy arrived without anyone asking. Kratos does not have that exposure yet, for the same reason it has no annuity: there is no fleet out there carrying its name.