

Appian's Cloud Revenue Grew 23%. Pegasystems' Contract Value Grew 8%. August Paid Both.
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
A law firm opened a securities-fraud investigation into Pegasystems on 25 August over the quarter it reported in July — and the shares have risen since. That is the sharpest illustration of what drove enterprise software last month: price moved, and almost no new profit moved with it.
Pegasystems reported before the thirty-day window even opened, so the gain came with an unchanged denominator: its price against trailing gross profit went from 3.70x on 29 July to 4.49x. Appian's June quarter was genuinely good — cloud subscription revenue up 23%, adjusted earnings before interest, taxes, depreciation and amortization of $16.2m against a $5-8m guide, full-year guidance raised — but the print added only about 3% to its trailing gross profit while its multiple went to 5.25x from 3.07x in early May.
One company is being paid for execution at a price its own guidance decelerates below. The other is being paid for nothing it did.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
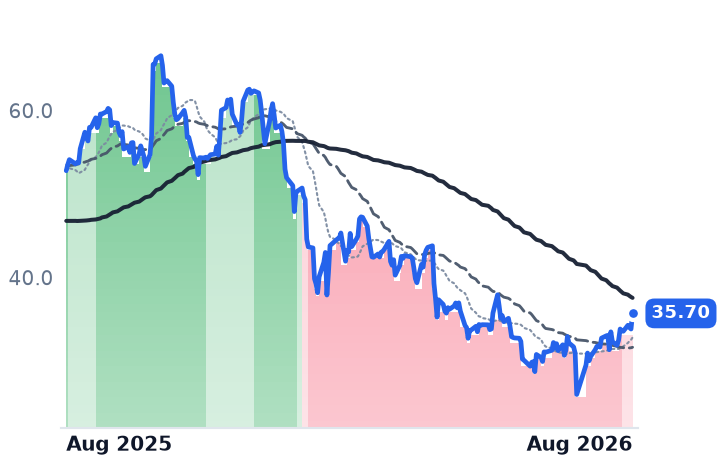
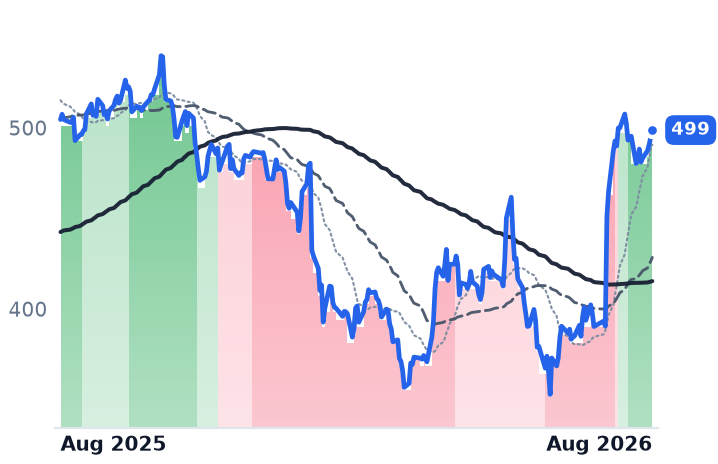
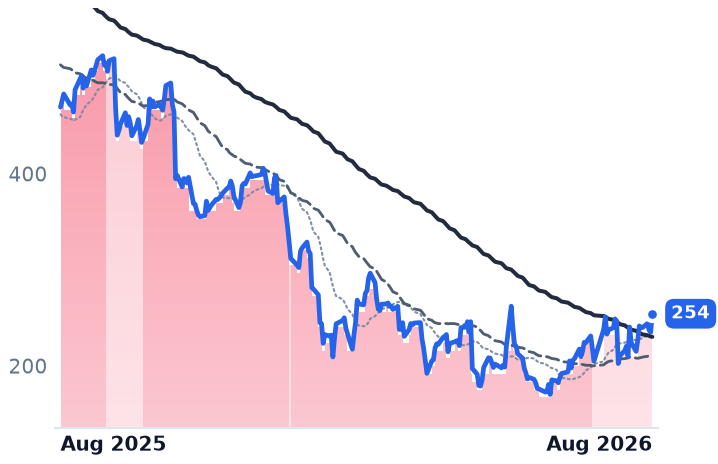
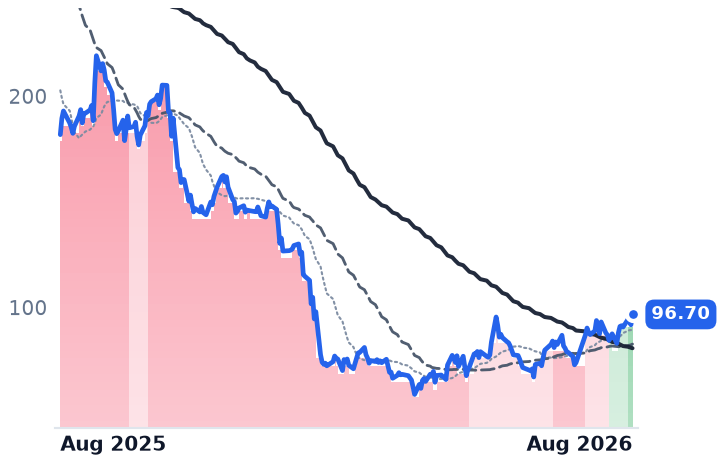
PEGA | Pegasystems | Low-Code & Process Automation | ⚠️ Emerging Bear | +20.9% | −32.4% |
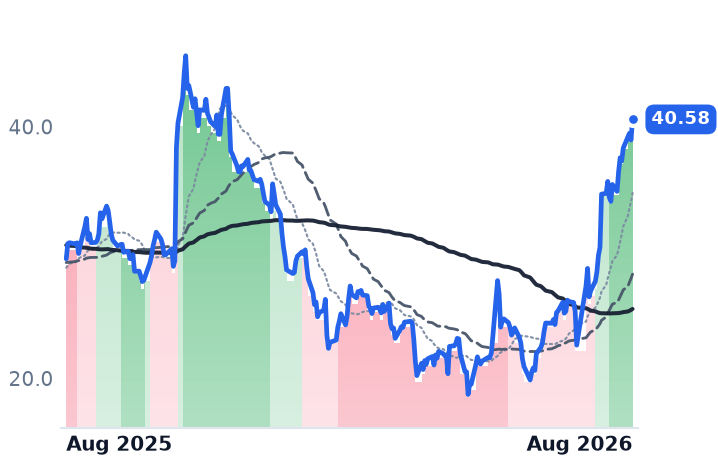
APPN | Appian | Low-Code & Process Automation | 🌱 Emerging Bull | +48.4% | +37.6% |
| Compared against · context, not the story | |||||
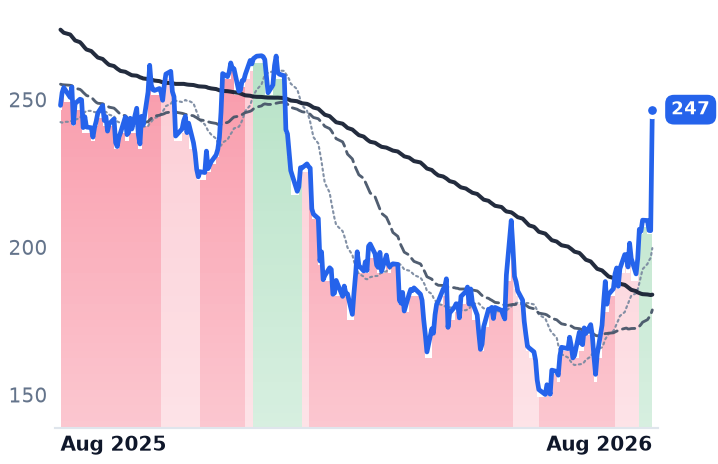
CRM | Salesforce | Customer Experience & CRM | 🔴 Cont. Bear | +35.9% | −0.6% |
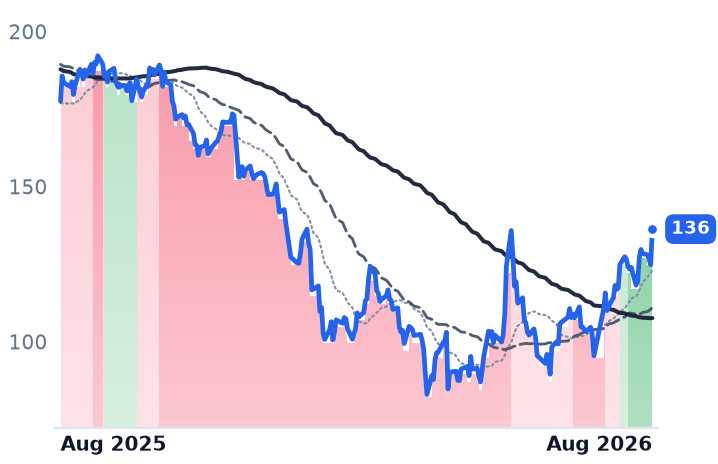
NOW | ServiceNow | Specialized Enterprise Solutions | 🔴 Cont. Bear | +23.2% | −23.2% |
MSFT | Microsoft | Cloud Infrastructure & Platforms | 🔴 Cont. Bear | +26.8% | −1.2% |
HUBS | HubSpot | Customer Experience & CRM | 🔴 Cont. Bear | +6.8% | −45.8% |
MNDY | monday.com | Other | 🌱 Emerging Bull | +11.0% | −46.8% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
PEGA | $5.9B | 18.9x | 14.6x | 3.4x | 3.1x | 4.5x | 4.1x | 29.3x | 8.5% |
APPN | $3.1B | n/m | 38.2x | 3.8x | 3.6x | 5.3x | 4.9x | 131.2x | 2.5% |
CRM | $168.4B | 18.7x | 14.5x | 3.8x | 3.7x | 5.0x | 4.7x | 12.4x | 9.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NOW | $132.8B | 79.8x | 31.6x | 9.0x | 8.2x | 12.1x | 11.0x | 39.8x | 3.4% |
MSFT | $3.7T | 27.5x | 25.2x | 11.1x | 9.4x | 16.3x | 13.9x | 18.2x | 1.8% |
HUBS | $12.1B | 83.8x | 17.8x | 3.5x | 3.3x | 4.2x | 4.0x | 40.2x | 6.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MNDY | $3.8B | 38.0x | 16.6x | 2.8x | 2.6x | 3.2x | 2.9x | 34.1x | 7.8% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
PEGA | Revenue | +8.8% | +9.2% | +8.7% |
| EPS | +18.0% | +7.8% | +6.2% | |
APPN | Revenue | +19.1% | +10.8% | +7.4% |
| EPS | +104.0% | +31.1% | +11.4% | |
CRM | Revenue | +9.3% | +11.1% | +9.4% |
| EPS | +17.4% | +20.2% | +10.4% | |
NOW | Revenue | +22.4% | +18.7% | +18.6% |
| EPS | +17.1% | +23.2% | +21.4% | |
MSFT | Revenue | +18.0% | +18.2% | +19.6% |
| EPS | +26.7% | +15.4% | +18.5% | |
HUBS | Revenue | +18.2% | +14.2% | +14.0% |
| EPS | +38.2% | +25.9% | +18.4% | |
MNDY | Revenue | +19.8% | +15.2% | +14.9% |
| EPS | +27.8% | +22.3% | +19.1% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Pomerantz LLP said on 25 August that it is investigating whether Pegasystems and certain of its officers or directors engaged in securities fraud, citing the July earnings miss and the company's disclosure that clients were stretching out decision cycles. Pegasystems — which sells workflow, case-management and customer-engagement software to banks, insurers, healthcare payers and government agencies — closed higher in the sessions that followed.
That sequence is the month in miniature. Over the thirty days to 27 August, Pegasystems rose 20.9% and Appian, a low-code automation platform sold into financial institutions, federal agencies, life sciences and insurance, rose 48.4%. Only one of the two put any new gross profit on the board inside that window, and the money at issue is whether the group is being repriced on bookings at all.
One good quarter, one bad one, three weeks apart
Appian's June quarter was the real thing. Revenue rose 19.1% to $203.3m and cloud subscription revenue rose 23% to $131.7m, with net expansion on the cloud base holding at 115%. Adjusted earnings before interest, taxes, depreciation and amortization came in at $16.2m against management's own $5-8m guide, and the full-year outlook went up to $845-853m of revenue. Eighty-five percent of new customers in the quarter bought artificial-intelligence-enabled tiers. The cost shows up above the operating line: gross margin fell to 71.2% from 74.3% a year earlier, which management attributed to the mix of AI products and the compute behind them.
Pegasystems' July quarter was the opposite. Growth in the annualized value of its contracted business slowed to 8% in constant currency; the cloud portion grew 22%, down from 27% the prior quarter. Operating margin fell to 4.0% in the June quarter from 20.7% in December, and net income dropped 55.7% to $13.3m even as revenue rose 9.4% — reported revenue lurches because the company books term licenses upfront, which is why contract value, not the income statement, is the growth measure that matters here. Founder and chief executive Alan Trefler called it a "max confusion moment" on the 22 July call, with buyers whipsawing between spending on AI and controlling its token costs. Management had budgeted a third of the year's net-new contract value into the first half, said the half significantly underachieved, and called the recovery "very difficult."
The month was multiple, not profit
Because Appian carries a trailing net loss, its price-to-earnings ratio measures nothing; gross profit is the comparable base. On that measure Pegasystems went from 3.70x on 29 July to 4.49x — and since it reported on 22 July, before the window opened, its entire advance is the multiple, with the denominator untouched. Appian went from 3.63x to 5.25x while its quarter added roughly 3% to the trailing gross profit base. Roughly nine-tenths of that 48% move is repricing.
The rest is sector weather. Reuters reported on 26 August that software shares have been on a roller coaster driven by AI uncertainty and by momentum and leveraged trading that amplify the swings, with January's drawdown following an Anthropic product launch that some managers feared would obsolete enterprise software — the same substitution fear sitting under both these multiples. The final session of the window was Salesforce's, already the sector's story that day, and it lifted ServiceNow 9.2% alongside it. Over the identical thirty days Salesforce rose 35.9% and Microsoft 26.8%: Pegasystems underperformed both. Appian beat them, and the excess is dated to its 7 August earnings gap, after which DA Davidson, Morgan Stanley and Citi all raised targets — to $34, $32 and $40. The shares have since closed above all three.
What each side has earned
Appian has earned part of its year: trailing gross profit grew 15.7%, so roughly 40% of the twelve-month gain is business and the balance is repricing. What it has not earned is the forward curve. At 38.2x forward earnings it is priced against a consensus that has revenue growth halving to 10.8% in 2027, and against its own guidance implying cloud growth decelerating to 20% from the 23% just printed. Pegasystems has earned none of the last thirty days — but it is not expensive on what it produces: 14.6x forward earnings against 18.9x trailing, on a trailing free-cash-flow yield of 8.5%, with $288m of first-half free cash flow and $360m spent on buybacks in the same six months.
The two are no longer a hedge against each other. A year ago the pair could be held as one bet on process automation; today the cheap name is rising on nothing it reported and the executing name is re-rating past its own forecast. Both need the same thing to hold: a print.
Pegasystems put two-thirds of its full-year net-new contract value into a second half whose first quarter management itself called a "lousy time for turnaround." That number arrives in October, and it will be the first company-specific fact anyone has had since the rally started.