

Dycom Set a Record $12.2bn Backlog, Guided the Next Quarter Below Consensus, Fell 11%
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
A contractor can raise its full-year revenue forecast, report the biggest quarter it has ever had and still lose nearly a quarter of its value in a week. Dycom's second quarter, reported 26 August, grew revenue 45.6% to $2.01bn and beat on adjusted earnings; what moved the shares was a third-quarter forecast whose $4.56 midpoint sat 4.8% under consensus. Every other contractor in the complex rose that day.
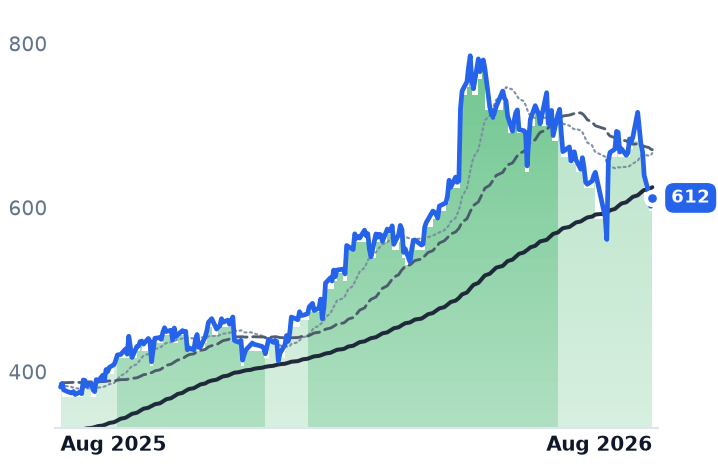
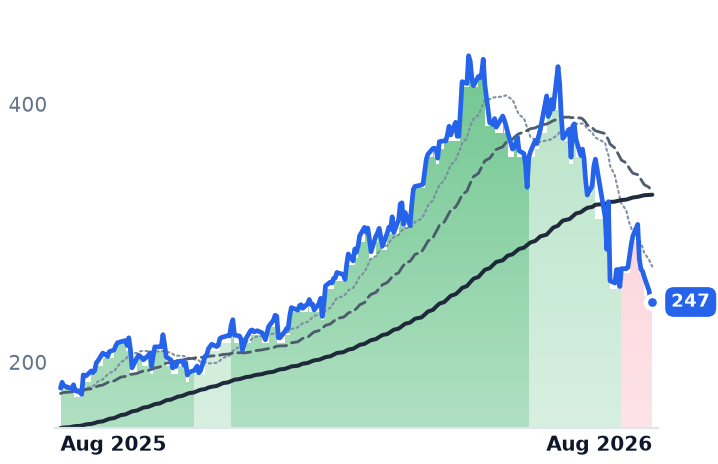
The split running through this rung of the artificial-intelligence build is between what has been booked and what converts soon. MYR Group's order book is a record $3.16bn and its management has already guided second-half segment margins below the June quarter's actuals. IES Holdings, whose 2-for-1 split took effect 24 August, grew revenue 39.6% at a record 27.4% gross margin and has risen over the past month.
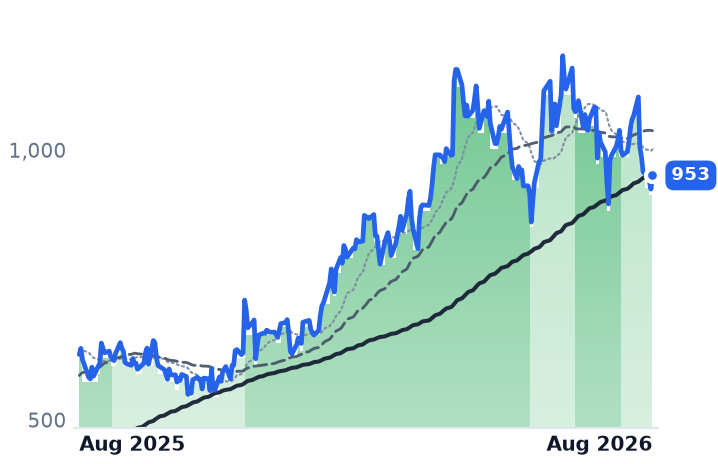
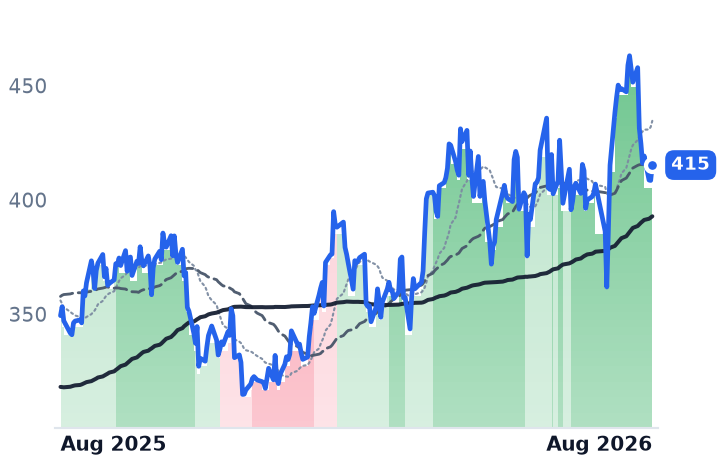
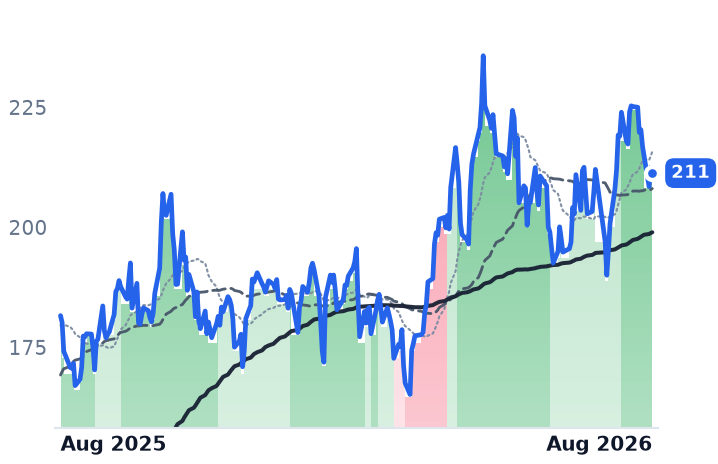
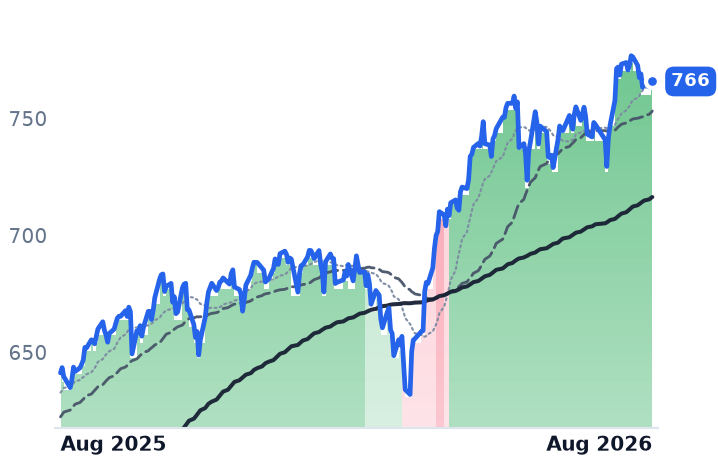
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
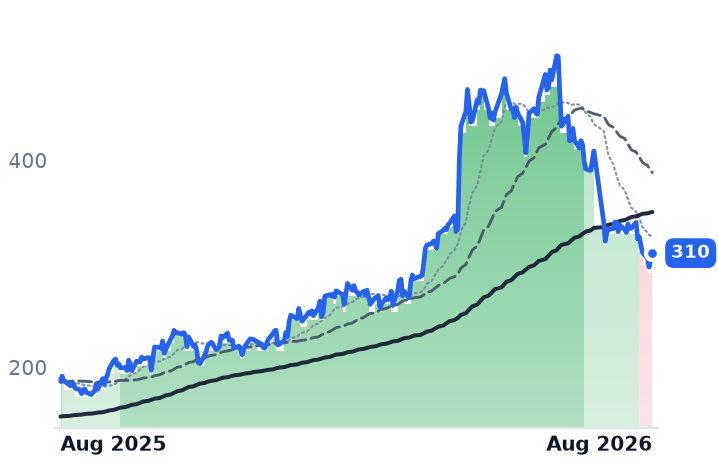
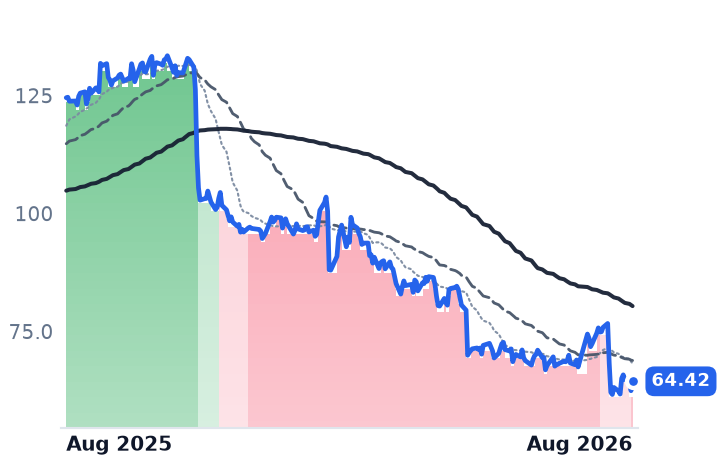
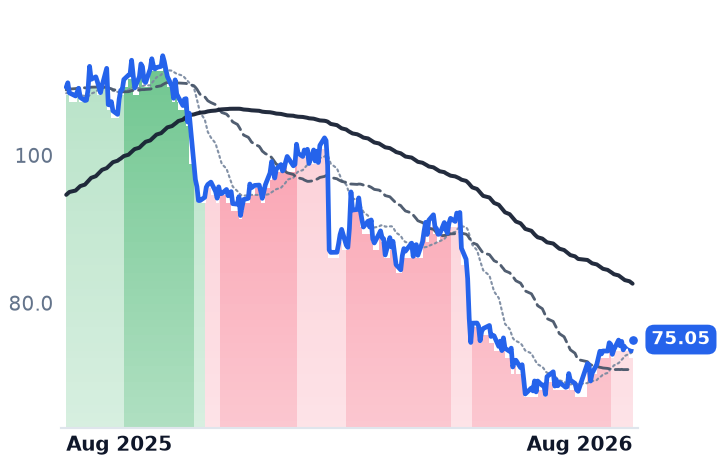
MYRG | MYR | Electrical & Power Infrastructure | 🟢 Cont. Bull | −8.9% | +66.1% |
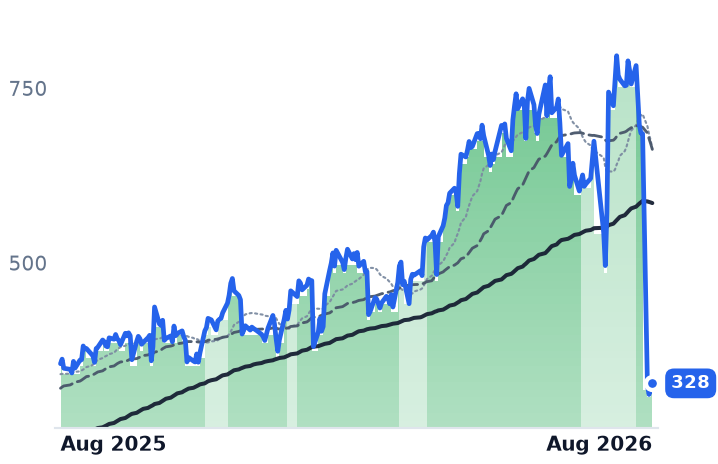
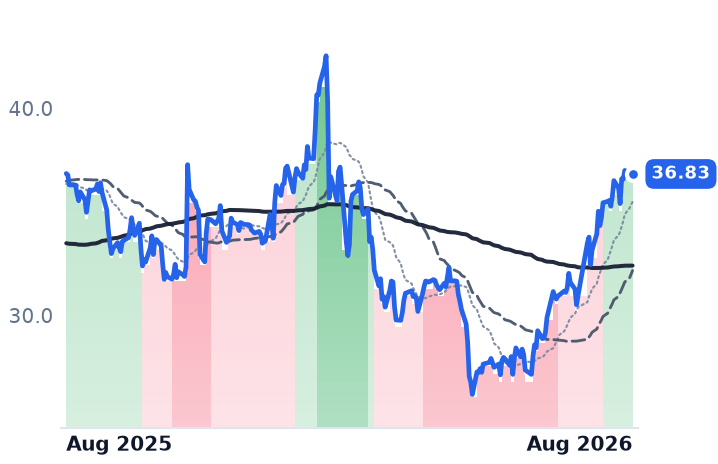
IESC | IES | MEP & Building Systems | 🟢 Cont. Bull | −39.7% | −7.9% |
| Compared against · context, not the story | |||||
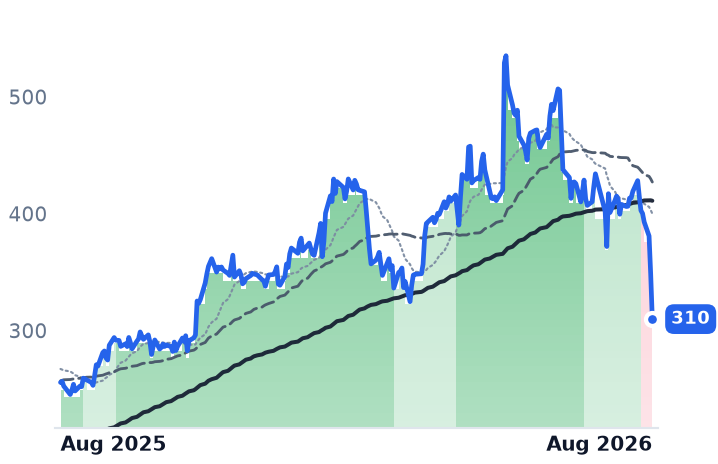
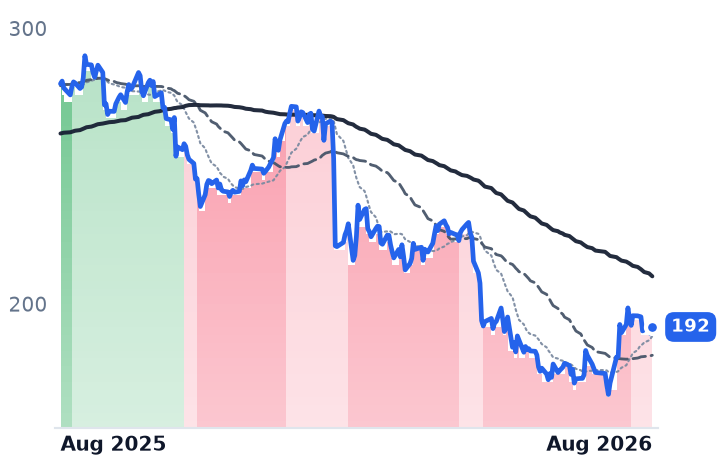
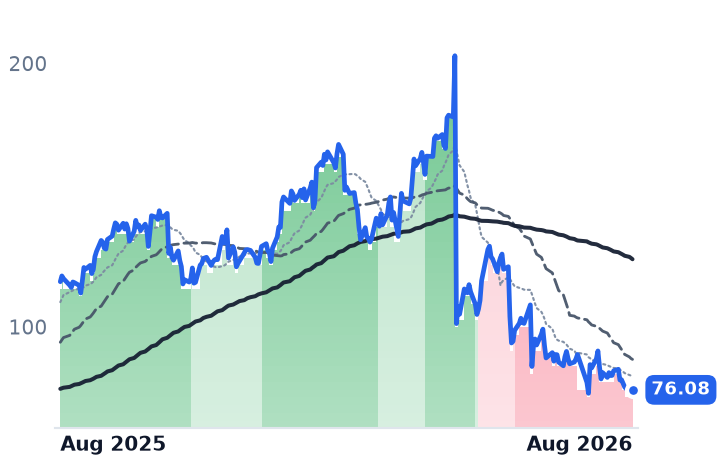
DY | Dycom Industries | Electrical & Power Infrastructure | 🟢 Cont. Bull | −22.9% | +21.2% |
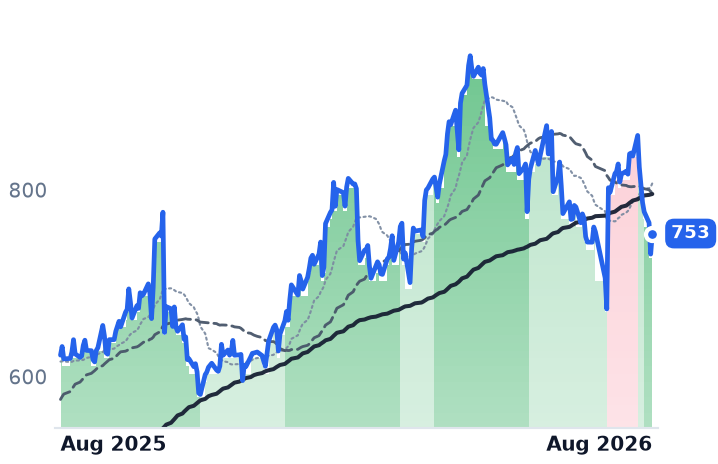
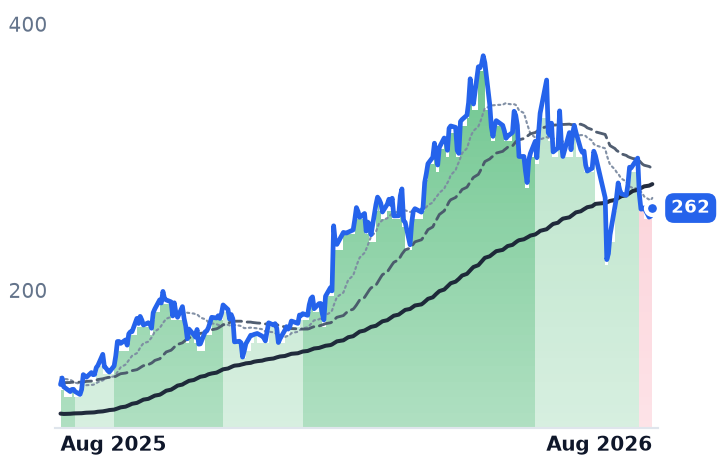
EME | EMCOR | Electrical & Power Infrastructure | 🟢 Cont. Bull | +6.7% | +20.9% |
ACM | Aecom | Design & Engineering Consulting | 🔴 Cont. Bear | −13.5% | −48.3% |
TTEK | Tetra Tech | Design & Engineering Consulting | 🔴 Cont. Bear | +9.9% | −0.1% |
STN | Stantec | Design & Engineering Consulting | 🔴 Cont. Bear | +4.5% | −31.3% |
WSP.TO | WSP Global | Engineering & Construction | 🔴 Cont. Bear | +9.7% | −31.5% |
PWR | Quanta Services | Electrical & Power Infrastructure | 🟢 Cont. Bull | +4.0% | +60.5% |
MTZ | MasTec | Electrical & Power Infrastructure | 🟢 Cont. Bull | −21.1% | +37.0% |
PRIM | Primoris Services | Energy & Power Project Solutions | ⚠️ Emerging Bear | −3.6% | −35.1% |
VRT | Vertiv | Data Center Power & Thermal | 🟢 Cont. Bull | −2.9% | +102.6% |
GEV | GE Vernova | GE Vernova Integrated | 🟢 Cont. Bull | +1.0% | +53.4% |
ETN | Eaton | Power & Propulsion Systems | 🟢 Cont. Bull | +7.5% | +18.9% |
NVDA | NVIDIA | AI & Data Center GPUs | 🟢 Cont. Bull | +7.2% | +16.3% |
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | +3.4% | +19.4% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DY | $11.8B | 37.0x | 23.7x | 1.9x | 1.5x | 9.6x | 7.9x | 13.4x | 3.7% |
MYRG | $4.8B | 29.2x | 25.5x | 1.2x | 1.1x | 9.7x | 8.9x | 16.2x | 4.0% |
IESC | $13.1B | 28.7x | 28.3x | 3.3x | 3.1x | 12.6x | 11.9x | 21.8x | 1.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
EME | $34.3B | 24.3x | 23.6x | 1.8x | 1.7x | 9.4x | 8.6x | 14.9x | 3.4% |
ACM | $8.3B | 29.3x | 16.3x | 0.5x | 1.1x | 9.5x | 19.7x | n/m | 2.4% |
TTEK | $9.6B | 22.2x | 23.5x | 1.9x | 2.2x | 10.1x | 11.7x | 15.6x | 5.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
STN | $8.4B | 23.0x | 16.5x | 1.4x | 1.2x | 3.3x | 2.7x | 12.3x | 5.7% |
WSP.TO | $23.1B | 23.3x | 14.9x | 1.3x | 1.4x | 7.3x | 8.1x | 13.3x | 7.5% |
PWR | $96.1B | 72.3x | 38.2x | 2.9x | 2.4x | 20.3x | 16.9x | 33.7x | 2.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MTZ | $21.1B | 41.4x | 28.6x | 1.3x | 1.2x | 11.4x | 10.0x | 21.9x | 1.2% |
PRIM | $4.2B | 29.9x | 34.9x | 0.6x | 0.6x | 6.7x | 6.7x | 16.6x | 2.1% |
VRT | $100.8B | 58.0x | 39.0x | 8.8x | 7.2x | 23.4x | 19.2x | 40.1x | 2.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
GEV | $254.8B | 27.1x | 31.1x | 6.2x | 5.5x | 30.5x | 27.3x | 28.4x | 4.9% |
ETN | $162.8B | 42.5x | 31.0x | 5.4x | 5.0x | 15.1x | 13.8x | 28.4x | 2.8% |
NVDA | $5.5T | 34.3x | 25.0x | 21.5x | 13.9x | 29.0x | 18.7x | 28.3x | 2.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
DY | Revenue | +17.1% | +40.1% | +11.3% |
| EPS | +39.5% | +47.1% | +20.3% | |
MYRG | Revenue | +22.9% | +15.5% | +11.4% |
| EPS | +72.5% | +18.4% | +22.2% | |
IESC | Revenue | +27.7% | +48.1% | +18.8% |
| EPS | +76.1% | +16.3% | +17.1% | |
EME | Revenue | +21.4% | +10.9% | +8.3% |
| EPS | +30.1% | +13.0% | +13.2% | |
ACM | Revenue | −1.6% | +7.2% | +5.8% |
| EPS | −24.1% | +55.1% | +18.1% | |
TTEK | Revenue | −3.5% | +4.3% | +1.8% |
| EPS | +4.1% | +10.2% | +11.4% | |
STN | Revenue | +12.6% | +6.0% | +4.8% |
| EPS | +17.0% | +11.8% | +12.3% | |
WSP.TO | Revenue | +18.9% | +7.5% | +6.9% |
| EPS | +19.5% | +14.6% | +13.8% | |
PWR | Revenue | +40.6% | +16.7% | +12.5% |
| EPS | +57.5% | +17.8% | +16.7% | |
MTZ | Revenue | +30.5% | +20.3% | +14.5% |
| EPS | +43.0% | +34.8% | +28.0% | |
PRIM | Revenue | −3.4% | +12.0% | +10.4% |
| EPS | −60.0% | +138.8% | +21.4% | |
VRT | Revenue | +37.0% | +29.7% | +21.9% |
| EPS | +62.8% | +36.4% | +27.1% | |
GEV | Revenue | +23.9% | +14.8% | +15.1% |
| EPS | +322.3% | −19.0% | +39.6% | |
ETN | Revenue | +19.6% | +10.6% | +9.4% |
| EPS | +12.2% | +18.2% | +16.4% | |
NVDA | Revenue | +65.1% | +84.2% | +43.2% |
| EPS | +59.0% | +91.7% | +42.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Dycom Industries reported the largest quarter in its history on Wednesday, and the shares closed down 11%. The West Palm Beach contractor — 19,556 people who engineer, place and splice the fibre, coaxial and copper that carriers and utilities bury, plus cell sites and buried-utility locating — grew contract revenue 45.6% to $2.01bn, earned $5.29 of adjusted profit a share against $4.72 expected, and carried a record $12.2bn of backlog into the second half.
What priced the stock was the quarter in front of it. Dycom lifted its full-year revenue range to $7.48–7.66bn but guided third-quarter adjusted earnings to $4.33–4.79, a $4.56 midpoint that sits 4.8% below the $4.79 analysts carried. That is the whole disagreement: order books at these contractors have lengthened until the backlog no longer maps onto the coming twelve months — EMCOR told investors in July that only about three-quarters of its book now converts within a year, against 85% historically — so the near quarter is the only part of the book anyone is actually paying for.
The one margin that compressed
"Demand across our portfolio is stronger than ever, fueled by a generational deployment of digital infrastructure that is projected to go well into the next decade," chief executive Dan Peyovich said on 26 August. The demand is not in dispute. The unit economics are: in the quarter ended 2 May, Dycom's gross margin was 14.00% against 15.03% a year earlier, growth arriving at a thinner rate. It is the only name here where that happened — and Dycom sells telecom fibre, not data-center electrical work. The de-rating also began before the disclosure: the stock fell 8.6% on 25 August with nothing announced, making the five-session decline 23.1%. At Wednesday's $309.80 close it changes hands near 18.7x forward earnings, against 23.7x before the fall.
On the day itself, EMCOR rose 3.0%, AECOM 3.2%, GE Vernova 2.7% and MYR Group 2.6%. Only Dycom fell.
A record book that is not the transmission book
MYR Group, the 135-year-old electrical contractor from Henderson, Colorado, is down 30.6% over three months on numbers that read nothing like it: June-quarter revenue up 20.1% to $1.082bn, gross margin at an eight-quarter high of 13.19%, operating income up 73.4%, and backlog at a record $3.16bn. Two things explain part of the gap. The quarter benefited from favourable project closeouts, and management guided full-year segment margins to the midpoints of its 8–11% transmission and 6–9% commercial ranges — under the 9.4% and 8.5% the quarter delivered. And the growth is not the interconnection bottleneck everyone cites: transmission and distribution revenue rose 4% to $524m while commercial and industrial work rose 42% to $558m. The largest transmission awards, including two Xcel Energy projects worth over $200m combined, do not reach the field until the second half of 2027.
The contractor that did not de-rate
IES Holdings' quoted price halved on 24 August because a two-for-one split distributed after the close on 21 August took effect. Adjusted for it, the Houston electrical and technology-systems contractor is up 18.6% over thirty days. Its June quarter ran a record 27.41% gross margin on revenue up 39.6%, with backlog up 91% to $4.5bn and Communications — its data-center network work — up 51% to $453.1m. "For the third quarter of fiscal 2026, we delivered a 40% increase in revenue and a 60% increase in operating income compared with the third quarter of fiscal 2025," chief executive Matt Simmes said on 31 July. It trades at 28.3x forward earnings against 28.7x trailing — almost no growth priced beyond this fiscal year — on a forward number carried by a single analyst.
The verdict
The scarcity rent in electrical labour is not being competed away; three of these four contractors expanded gross margin into the June quarter. What is being repriced is duration. Dycom earns a piece of its fall — its margin genuinely thinned and its own guide undershot — but a 23% week against a raised year and a record book prices something the disclosure does not contain. MYR Group's decline is doing more rational work, because the company itself said the second half moderates.
MYR Group's next report is expected in late October, and management has already said where the margins land: the middle of its ranges, below what June delivered. The shares have spent three months arguing about a number the company disclosed a month ago.