

Centrus Booked $4.5bn of Enrichment Orders for Capacity It Won't Build Until 2029
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
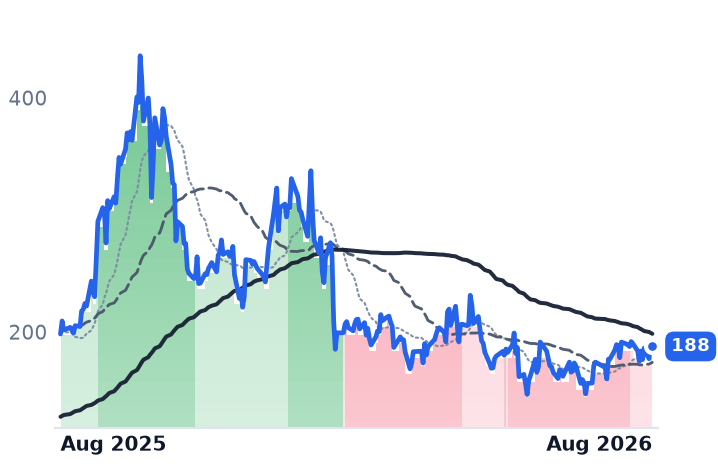
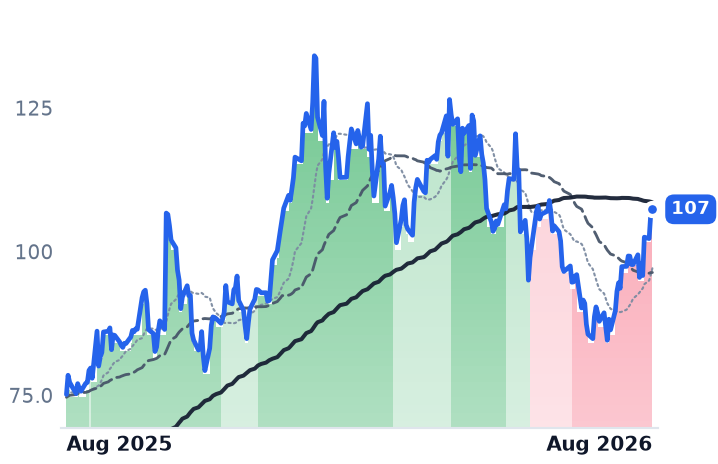
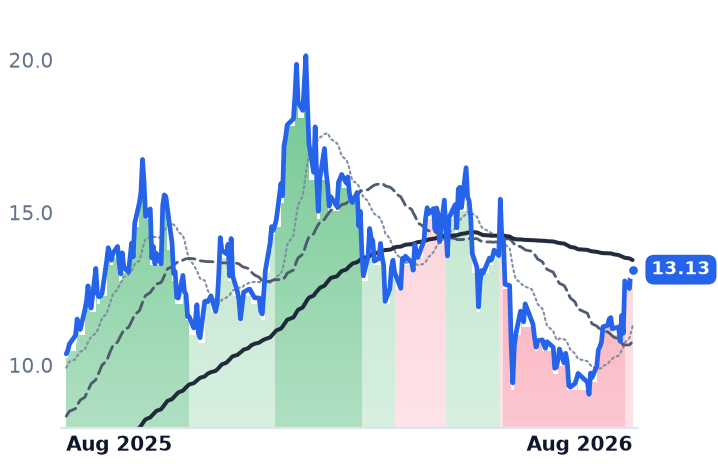
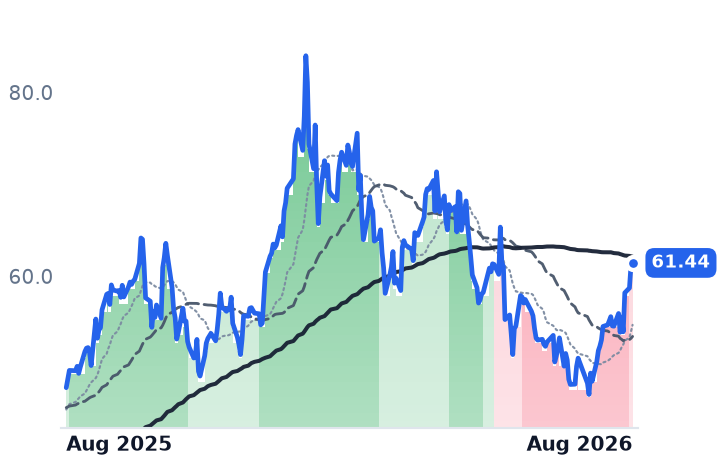
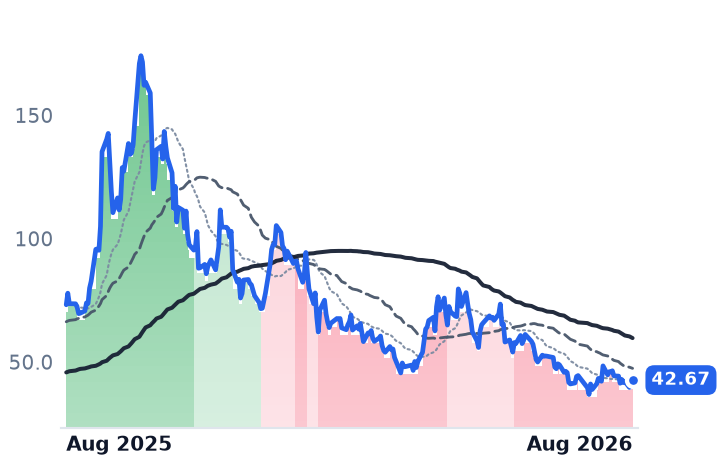
August's uranium rally paid the three rungs of the nuclear fuel chain in inverse order to how much of their output is already sold. Uranium Energy, which reported no sales at all last quarter and describes itself as 100% unhedged, rose 39.1% over thirty days; Cameco, with deliveries of more than 28m pounds a year locked in for five years, rose 20.2%; Centrus, the enricher, rose 10.6% and is still lower than it was a year ago.
The disclosure supports that ordering. Cameco realized US$67.79 a pound against a spot indicator at US$89.50, and its uranium segment's adjusted earnings before interest, taxes, depreciation and amortization fell to $252m from $352m. Centrus grew revenue 14% mostly by reselling natural uranium while enrichment volumes fell 23% and operating income fell 69%. The backlog that nearly doubled belongs to the 2030s; the valuation has not moved since May.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
LEU | Centrus Energy | Uranium | ⚠️ Emerging Bear | +10.6% | −5.4% |
CCJ | Cameco | Uranium | ⚠️ Emerging Bear | +23.5% | +42.9% |
UEC | Uranium Energy | Uranium | ⚠️ Emerging Bear | +39.1% | +26.6% |
| Compared against · context, not the story | |||||
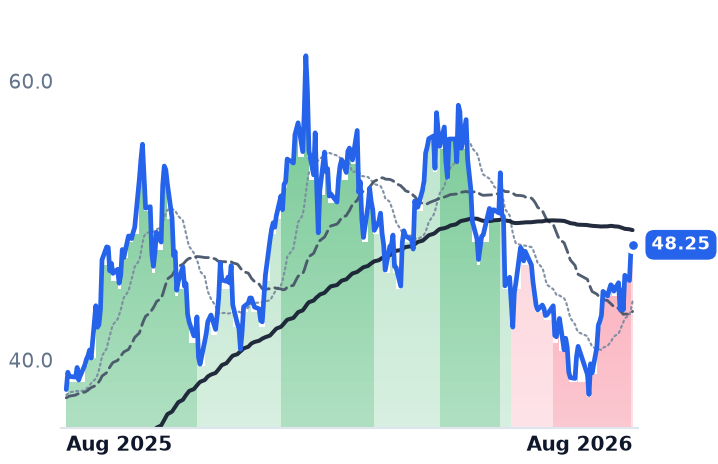
URA | Global X - Uranium ETF | Asset Management | ⚠️ Emerging Bear | +23.9% | +27.4% |
URNM | Sprott Uranium Miners ETF | Asset Management | ⚠️ Emerging Bear | +27.1% | +28.4% |
OKLO | Oklo | Emerging & Specialized Energy | 🔴 Cont. Bear | +7.8% | −41.7% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
LEU | $3.6B | 74.8x | 75.3x | 7.5x | 7.6x | 32.2x | 32.5x | 39.4x | -6.2% |
CCJ | $46.8B | 182.3x | 69.8x | 18.7x | 13.1x | 67.8x | 47.5x | 75.2x | 0.8% |
UEC | $6.5B | n/m | — | 321.7x | 64.7x | 760.1x | 152.9x | n/m | -1.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
URA | $3.9B | — | — | — | — | — | — | — | — |
URNM | $1.1B | — | — | — | — | — | — | — | — |
OKLO | $7.3B | n/m | — | — | — | — | — | n/m | -3.8% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
LEU | Revenue | +4.9% | +0.1% | −9.8% |
| EPS | −44.4% | +15.9% | −15.6% | |
CCJ | Revenue | +4.1% | +10.7% | +6.8% |
| EPS | +7.1% | +70.8% | +25.0% | |
UEC | Revenue | −59.3% | +272.6% | +157.9% |
| EPS | +56.8% | −79.8% | −647.6% | |
OKLO | Revenue | — | +241.0% | +577.4% |
| EPS | +50.0% | +10.3% | +16.5% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Centrus Energy, the only American-owned uranium enricher, closed its June quarter with $4.5bn of orders on its books running out to 2040 — and then turned in the weakest month of the three companies that mine, convert and enrich the fuel every reactor project presupposes.
That inversion is the story of the last five weeks in nuclear fuel. The names rose in almost exact reverse order to how much of their production is already contracted, which means the money went to unsold pounds sitting in a warehouse rather than to signed deliveries. What is at stake is whether the data-center power deals that made nuclear a growth industry have yet turned into revenue for anyone who supplies the fuel. On the evidence of these three income statements, they have not.
From the 28 July close to 26 August, Uranium Energy — an in-situ recovery producer with projects in Texas, Wyoming and Arizona — gained 39.1%, the Global X Uranium fund 23.9%, Cameco 20.2% and Centrus 10.6%. Over twelve months Cameco is up 42.6% and Centrus is down 5.4%. Roughly half the month's move landed in one session, 21 August, when Uranium Energy traded 16.6m shares against a three-to-six-million daily norm. The rate backdrop argues against a duration-driven bid: long US rates hit a 19-year high on 18 August, and the Jackson Hole symposium opened on 27 August with new Federal Reserve chair Kevin Warsh pledging a policy "regime change".
The backlog and the machine
Centrus sells separative work units — the measure of enrichment effort — and natural uranium to utilities, and is building the American Centrifuge at Piketon, Ohio. Second-quarter revenue rose 14% to $176.1m, but gross profit fell 7.4% to $49.9m and operating income fell 69% to $10.4m. The mechanism is visible in the segment detail: enrichment volumes fell 23% while enrichment pricing rose only 3%, and the revenue growth came from reselling $53.4m of natural uranium at a thinner margin, with unit costs up 13%.
Against that, the order book. Enrichment backlog stands at $3bn, of which $2.4bn now sits under definitive agreements rather than contingent ones, and a supply contract with the small-reactor developer X-energy was signed on 6 August. "This was another strong quarter of financial and operational progress for Centrus that included a number of commercial wins for our future enrichment business," chief executive Amir Vexler said on 6 August. The operative word is future: commercial production is guided to begin in 2029, and management, bound by non-disclosure agreements, would not give volumes or pricing on the new contracts. Consensus revenue troughs at $424.1m in 2028 before recovering. The shares cost 75.3x forward earnings, with 2026 consensus earnings per share 44% below what was reported for 2025, and 32.2x trailing gross profit — essentially the 32.6x of mid-May, even though the backlog nearly doubled in between. Cash is not the constraint: $1.9bn on hand, no reliance on equity.
The scarcity argument is also thinning. The Department of Energy split $2.7bn of enrichment task orders across General Matter, Centrus and Orano Federal Services, while Urenco USA adds 2.1m separative work units in New Mexico.
The contracted and the unhedged
Cameco, which mines uranium and refines it into reactor fuel and owns 49% of Westinghouse, realized US$67.79 a pound in the quarter, up 18% year on year but roughly a fifth below spot and about 30% below the US$97 long-term indicator. Its uranium segment's earnings before interest, taxes, depreciation and amortization fell to $252m from $352m, which the company attributes to "contracting discipline." Its market-related contracts carry ceilings around $160 escalated, capping how much of any spike reaches the accounts, and its committed volumes run above the 28m-pound average through 2028 and below it in 2029 and 2030 — thinning precisely where the new-build case starts. The offset is Westinghouse, which confidentially filed for an initial public offering on 31 July. Cameco now costs 67.8x trailing gross profit against 38.6x on 18 May, on a market value 7% smaller.
Uranium Energy is the pure expression of what the month rewarded. It sold nothing at all in the quarter to 30 April, posting a $52.3m net loss, while holding 1.456m pounds of purchased uranium and 276,516 pounds produced at Irigaray, kept back to preserve "full exposure to uranium prices through its 100% unhedged strategy." When it does sell, that pays: 200,000 pounds went at $101 a pound in the prior quarter, against a quarterly average spot price of $80.76. At 4.53x book, liquid assets and metal together account for about 15% of the $6.50bn market value.
What the advance has earned
The spot indicator rose 4.7% since mid-July to US$89.50 — a six-month high, still below January's $100.25 peak. Equities moved five to eight times that. What the businesses earned is one line: Cameco's realized price, rising 18%. Everything else reported this quarter went the other way, and the demand story cited to justify the re-rating remains unbuilt — 80.4% of the roughly 9.8 GW committed to hyperscalers has not reached commercial operation, and the nearest thing to a named fuel supplier for a data center is Centrus's letter of intent with Oklo for 2029 deliveries. Washington's 50% tariffs on Canadian goods, imposed 22 August, arrived after the volume spike, not before it; uranium is off the retaliation list for now, and Cameco's Blind River refinery is the asset most exposed if that changes.
So the rally is a bid for uncommitted pounds and the option to sell them, and it is being made in a market where the most contracted seller is the one whose segment profit shrank. Centrus is the odd position: penalized on 2026 earnings that consensus says will fall, and not yet paid for a book that nearly doubled. Its first new centrifuge is due to be completed at Oak Ridge before the year is out. Until a machine spins, the order book is a promise about the 2030s being priced by a spot market having a good August.