

SiTime and Semtech Each Cleared $100m of Data-Center Revenue in a Single Quarter
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
The clock chips and copper drivers that sit in the last two metres of an artificial-intelligence rack have been sold for two years as content-per-rack promises. August's two earnings prints turned them into shipped revenue: SiTime's communications, enterprise and data-center line reached $101m, up 181% year on year and 64% of the company, while Semtech booked a record $100m data-center quarter and guided the next one up 160%.
Both businesses accelerated on every line that matters — SiTime's gross margin went to 63.0% from 51.9%, Semtech's operating income doubled and its net leverage fell to 1.1x. Both stocks are nonetheless below where they traded in May. The de-rating is doing different work in each: SiTime started from the richest valuation of the group, Semtech from the cheapest of the profitable names.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
SITM | SiTime | RF & Wireless | 🟢 Cont. Bull | +21.6% | +150.0% |
SMTC | Semtech | RF & Wireless | 🟢 Cont. Bull | +26.5% | +142.2% |
| Compared against · context, not the story | |||||
MTSI | MACOM Technology Solutions | RF & Wireless | 🟢 Cont. Bull | +8.3% | +108.2% |
MXL | MaxLinear | RF & Wireless | 🟢 Cont. Bull | +8.3% | +281.4% |
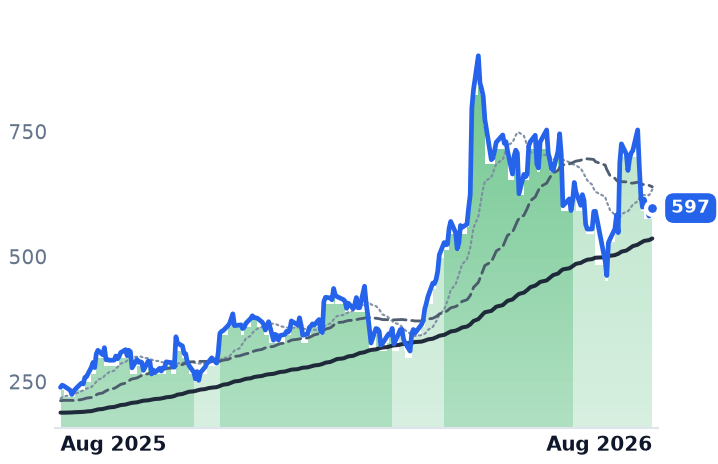
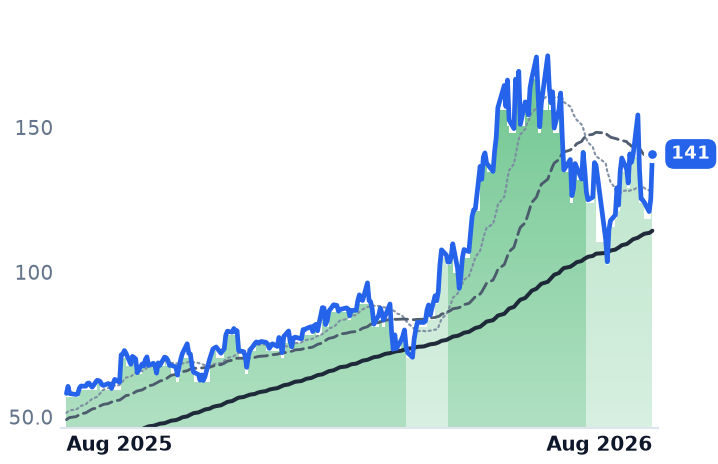
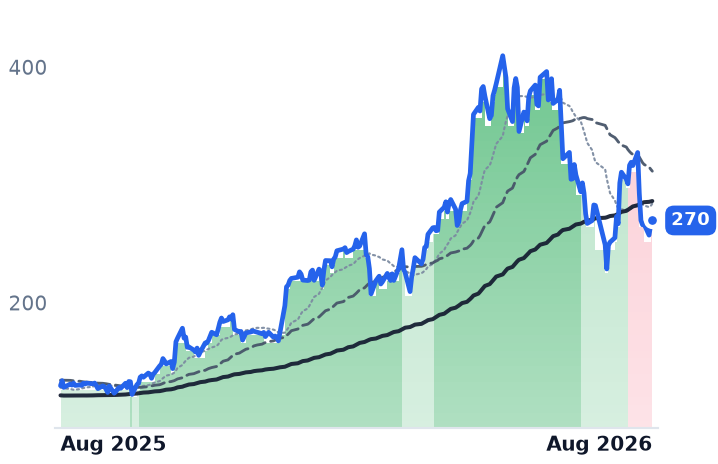
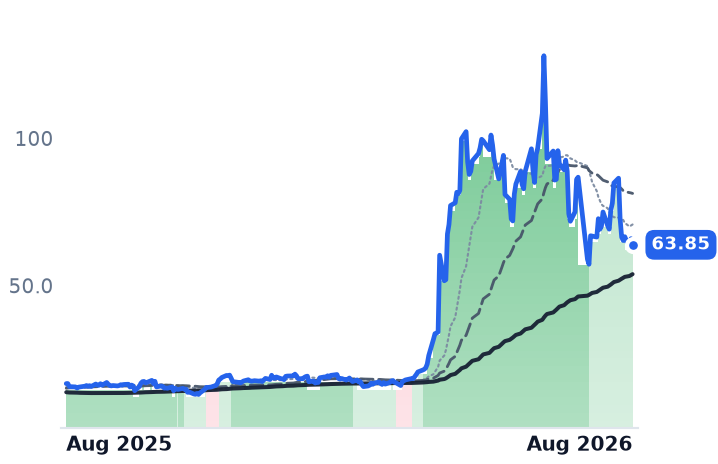
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SITM | $15.8B | — | 53.1x | 33.7x | 18.0x | 57.4x | 30.7x | 292.9x | 0.4% |
SMTC | $13.1B | 85.0x | 49.2x | 11.2x | 9.4x | 21.5x | 18.0x | 113.3x | 1.4% |
MTSI | $20.3B | 83.3x | 48.4x | 17.5x | 15.4x | 30.9x | 27.2x | 59.2x | 0.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MXL | $6.0B | n/m | 38.1x | 10.6x | 8.2x | 18.5x | 14.2x | n/m | 0.1% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
SITM | Revenue | +177.5% | +54.9% | +27.3% |
| EPS | +296.4% | +32.7% | +34.9% | |
SMTC | Revenue | +15.6% | +33.2% | +22.6% |
| EPS | +119.3% | +68.8% | +50.4% | |
MTSI | Revenue | +37.0% | +35.7% | +16.5% |
| EPS | +58.9% | +53.8% | +17.5% | |
MXL | Revenue | +58.5% | +30.5% | +20.4% |
| EPS | +505.3% | +54.0% | +22.8% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Two suppliers to the last two metres of an artificial-intelligence rack — the clock signals that keep a fabric of accelerators in step, and the copper and optical links that move data between them — reported August quarters in which data-center revenue crossed a $100m run rate for the first time.
That rung of the rack has until now been sold mostly as slideware: design wins, served-market sizing, content-per-server arithmetic with revenue dated years out. What the two prints establish is that the content is being invoiced. It also sets up the harder question, because over the three months to 26 August both stocks fell.
The timing bill, in dollars
SiTime makes silicon micro-electro-mechanical-system (MEMS) resonators, oscillators and clock chips, sold through distributors into infrastructure, automotive and consumer markets. Its communications, enterprise and data-center segment produced $101m in the June quarter, up 181% year on year and 34% sequentially — a ninth consecutive quarter of triple-digit growth, and 64% of a company that took total revenue up 126.5% to $157.4m. Gross margin reached 63.0%, against 51.9% a year earlier, and the company posted $8.2m of operating income where it had lost $24.6m.
Chief executive Rajesh Vashist put a figure on the mechanism on the August 5 call: hyperscaler synchronization requirements for elite temperature-compensated oscillators are adding "several hundred dollars of content per data center rack." The displacement is not a price argument. Quartz resonators fail roughly 50 times faster than silicon in the vibration of a fan-cooled server hall, and timing content now sits on accelerators, switches, network cards, optical modules and smart cables alike. Quartz still held about 72% of the timing market in 2025, with SiTime and Microchip the only merchant MEMS sellers.
SiTime closed its purchase of Renesas's Timing Product Division on July 1, paying $1.5bn in cash funded with $1.35bn of zero-coupon convertible notes. The carve-out runs about 70% gross margins and is guided to roughly $85m in the September quarter; combined guidance is $285–295m at approximately 68% gross margin.
Copper, booked out
Semtech designs analog and mixed-signal chips — optical transceiver drivers and receivers, and the linear equalizers inside active copper cables. Its data-center segment set a record at $100m in the quarter to July 26, up 91% year on year and 39% sequentially, on 800-gigabit volumes, 1.6-terabit CopperEdge and the start of the 1.6T FiberEdge ramp. Company gross profit grew 37.2% against revenue's 32.7%, and operating income more than doubled to $55.8m.
"We are at the center of one of the most significant infrastructure build-outs in history," chief executive Hong Hou told investors on August 25. The backlog supports it: the rest of fiscal 2027 is fully booked and more than 70% of the following year already is. October-quarter guidance is $410m, with data-center revenue up 160% year on year.
Two caveats survive. GAAP net income of $160.1m includes a $101.4m tax benefit; adjusted earnings were $0.71 a share. And CopperEdge's power advantage — up to 90% less than digital-signal-processor alternatives — is now contested, since Marvell has added its own active copper linear equalizers. The old objection, debt, is largely gone: net leverage is 1.1x, with $204m of cash against $503m of principal, and annualized interest expense below $3m against $75m the prior year.
The shares went the other way
Semtech rose 12.4% on August 26 on four times its recent volume, with UBS, Roth and Morgan Stanley all lifting targets; SiTime rose 25.5% on August 6. Both moves came after their own prints. Yet from May 26 to August 26 SiTime fell 19.7% and Semtech 14.4%, because between August 17 and 24 both — along with MACOM and MaxLinear — dropped 21% to 27% in five sessions with no discoverable company news. The likelier reading is the broad chip de-risking in which semiconductor stocks shed more than $1trn.
The obvious test — that a general radio-frequency and industrial recovery, rather than rack content, was lifting the group — fails. MACOM's data-center segment reached $137.6m, up 40% sequentially and accounting for roughly three-quarters of this fiscal year's growth; it trades at 27.2x forward gross profit. MaxLinear's infrastructure line reached about $85m, up 145%, entirely on its Keystone 4-level pulse-amplitude-modulation processors at hyperscalers, and it is still loss-making at the operating line at 14.2x forward gross profit. Same mechanism, no industrial cycle underneath it.
What the decline is doing
The businesses earn none of the three-month decline and the valuations explain much of it. SiTime is the most expensive of the four on price to forward gross profit at 30.7x, and 53x forward earnings against consensus growth near a third — a rich multiple compressing on an accelerating business. Semtech, at 18.0x forward gross profit, is the cheapest of the three profitable names, and its 49x forward earnings sits roughly level with consensus earnings compounding near 50%. Little in the reported numbers explains why it de-rated at all; the August 26 session began closing that gap.
The constraint ahead is not demand. "With the strong booking momentum and record backlog, we see the capacity we have secured may not be enough," Hou said of the second half of fiscal 2028 — the same sentence, in a different accent, that the optics suppliers have been saying all month.