

CrowdStrike's Record Quarter Re-Priced Cybersecurity. Palo Alto Reports September 1.
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
CrowdStrike's July quarter, published on 26 August, is the first hard disclosure the security rally has had to lean on — and it delivered: revenue up 25.8% in a fourth consecutive quarter of acceleration, net new annual recurring revenue up 51% to a record $332.8m, and subscription gross margin higher, not lower, than a year ago. The next session the whole listed security complex rose, Palo Alto among it, on no numbers of its own.
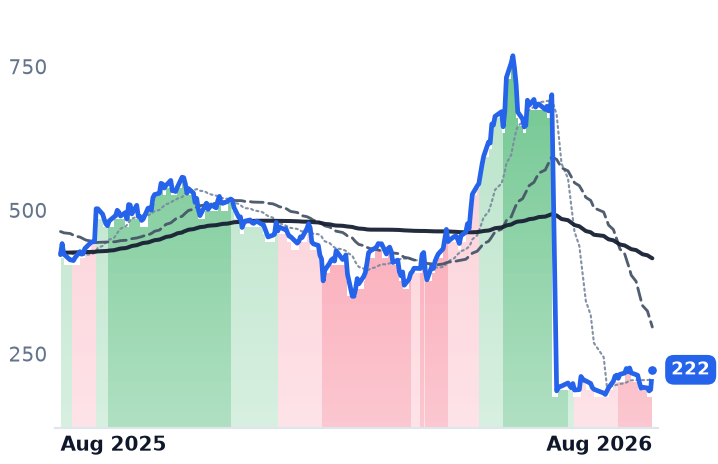
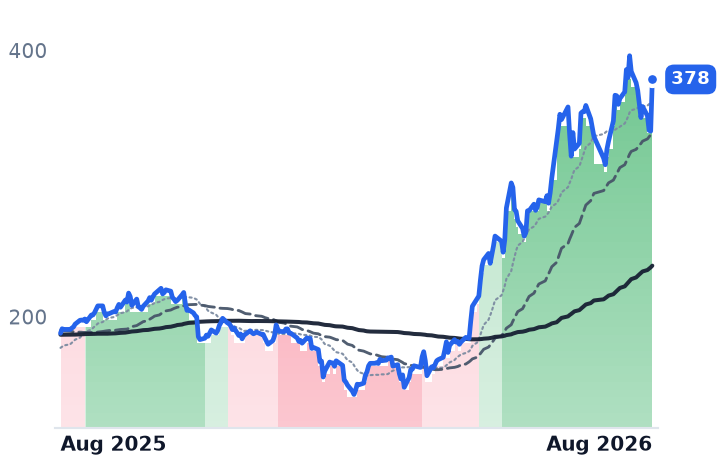
The business case is now documented for one of the two and still hypothetical for the other. CrowdStrike's trailing gross profit grew 26% over the past year; its price to that gross profit went from 32 times in early May to 57 times. Palo Alto's re-rating is steeper still on an income statement last updated in April. Its fiscal fourth quarter lands on 1 September.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
CRWD | CrowdStrike | Cybersecurity & Threat Protection | ⚠️ Emerging Bear | +22.3% | −47.4% |
PANW | Palo Alto Networks | Cybersecurity & Threat Protection | 🌱 Emerging Bull | +18.6% | +101.6% |
| Compared against · context, not the story | |||||
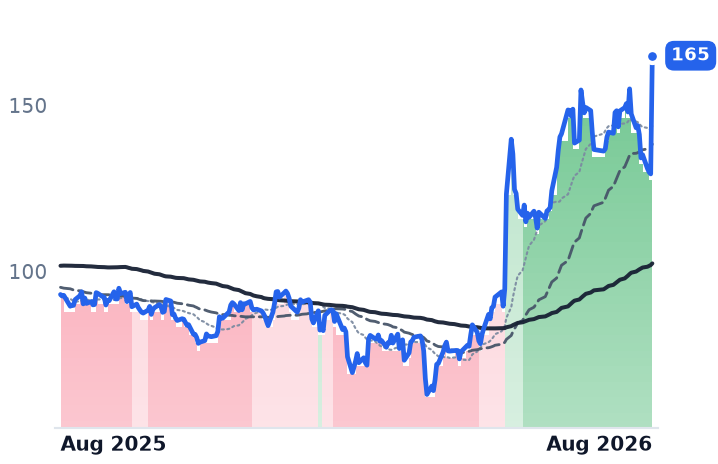
OKTA | Okta | Identity & Access Management | 🌱 Emerging Bull | +21.1% | +77.3% |
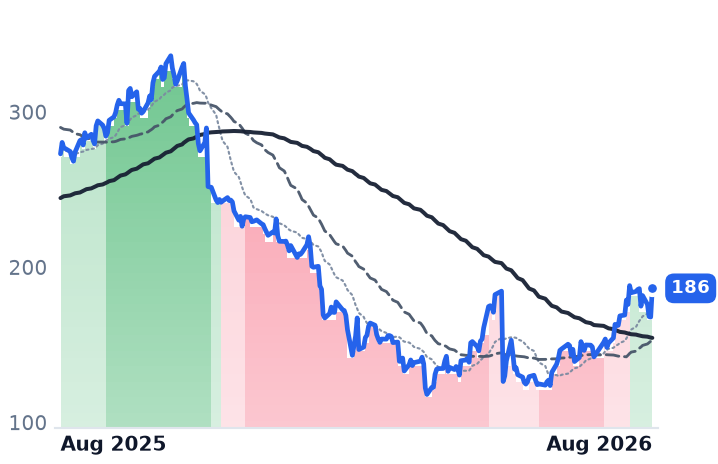
ZS | Zscaler | AI & Data Intelligence | 🔴 Cont. Bear | +22.9% | −31.7% |
FTNT | Fortinet | Network Security Appliances | 🌱 Emerging Bull | +11.7% | +114.3% |
NET | Cloudflare | Network & Application Delivery | 🟢 Cont. Bull | +15.0% | +47.9% |
S | SentinelOne | Cybersecurity & Threat Protection | 🌱 Emerging Bull | +21.3% | +29.7% |
RBRK | Rubrik | Other | 🌱 Emerging Bull | +47.6% | +20.5% |
SAIL | SailPoint | Identity & Access Management | 🔴 Cont. Bear | +31.3% | +1.7% |
TENB | Tenable | Cybersecurity & Threat Protection | 🌱 Emerging Bull | +18.8% | +21.9% |
QLYS | Qualys | Cybersecurity & Threat Protection | 🌱 Emerging Bull | — | +40.4% |
CHKP | Check Point Software Technologies | Cybersecurity & Threat Protection | 🔴 Cont. Bear | −2.4% | −29.6% |
MSFT | Microsoft | Cloud Infrastructure & Platforms | 🔴 Cont. Bear | +26.8% | −1.2% |
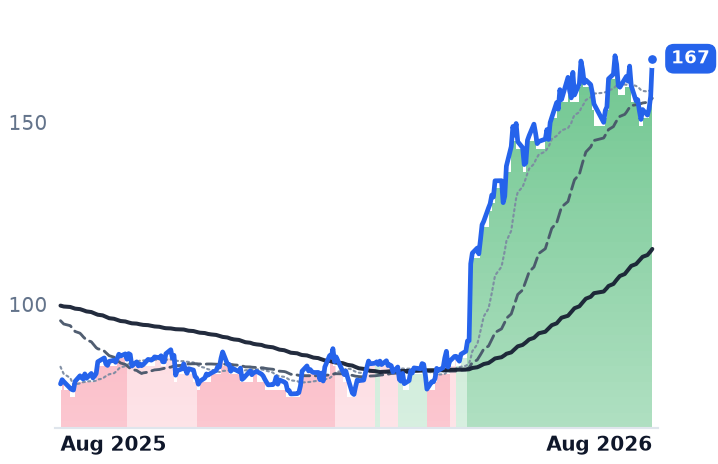
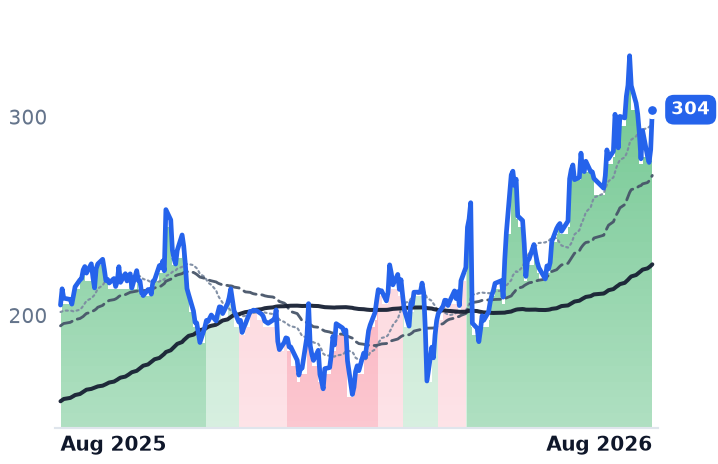
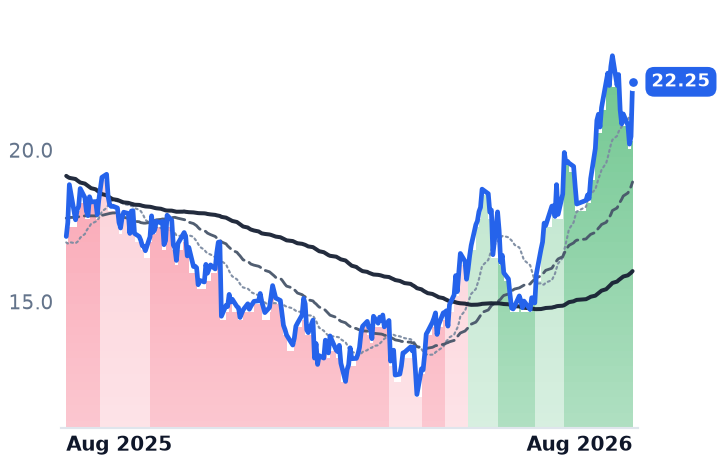
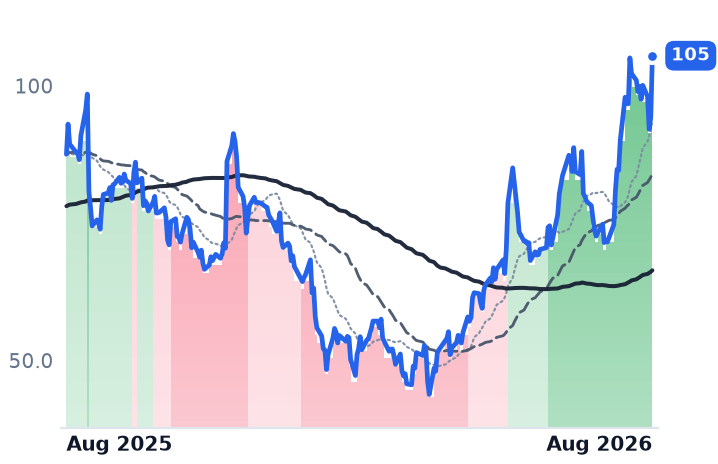
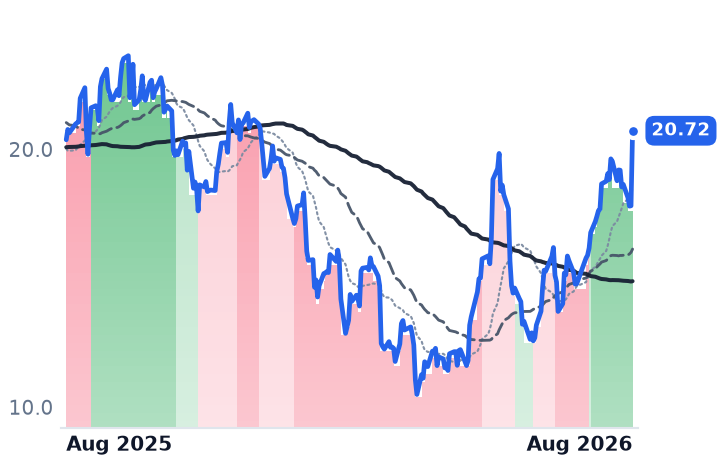
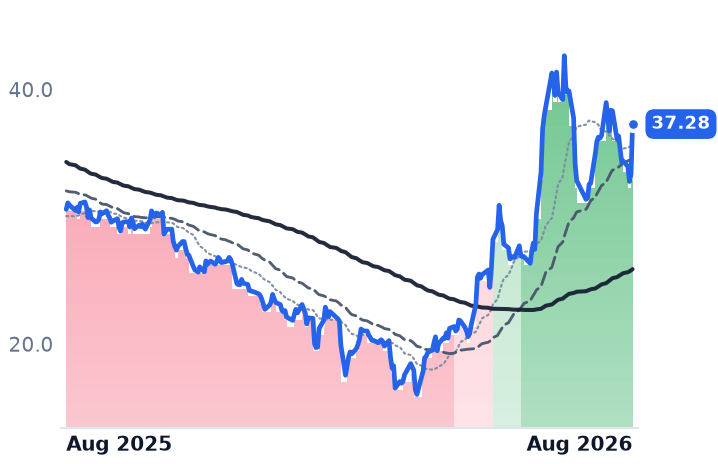
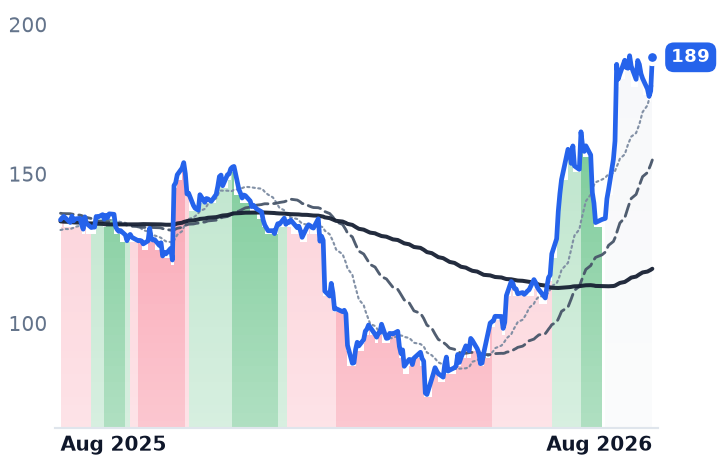
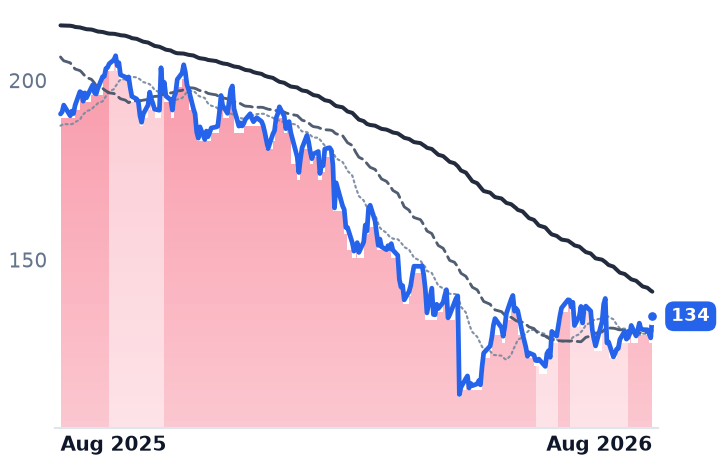
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CRWD | $232.1B | — | 185.2x | 43.0x | 39.0x | 57.2x | 51.9x | 667.4x | 0.7% |
PANW | $312.0B | 321.7x | 93.2x | 29.4x | 22.6x | 40.9x | 31.4x | 136.8x | 1.4% |
OKTA | $22.3B | 79.5x | 34.9x | 7.3x | 7.0x | 9.3x | 8.9x | 57.7x | 4.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ZS | $29.7B | n/m | 40.1x | 9.4x | 7.6x | 12.2x | 9.9x | 251.1x | 3.2% |
FTNT | $117.4B | 55.9x | 46.8x | 15.6x | 14.5x | 19.4x | 18.1x | 39.7x | 2.7% |
NET | $101.0B | n/m | 225.8x | 40.2x | 35.2x | 55.4x | 48.5x | — | 0.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
S | $7.2B | n/m | 61.3x | 6.9x | 6.0x | 9.3x | 8.1x | n/m | 0.6% |
RBRK | $20.6B | n/m | 322.3x | 14.5x | 12.5x | 17.9x | 15.5x | n/m | 1.5% |
SAIL | $10.9B | n/m | — | 9.7x | — | 14.6x | — | 833.4x | 1.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TENB | $2.4B | n/m | 11.0x | 2.3x | 2.2x | 3.0x | 2.8x | 23.3x | 11.1% |
QLYS | $3.2B | 15.9x | 11.9x | 4.6x | 4.4x | 5.6x | 5.3x | 11.4x | 9.2% |
CHKP | $12.9B | 12.3x | 11.9x | 4.7x | 4.6x | 5.5x | 5.4x | 14.3x | 10.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MSFT | $3.7T | 27.5x | 25.2x | 11.1x | 9.4x | 16.3x | 13.9x | 18.2x | 1.8% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
CRWD | Revenue | +22.2% | +23.7% | +21.9% |
| EPS | −1.2% | +32.6% | +26.5% | |
PANW | Revenue | +24.3% | +21.2% | +14.2% |
| EPS | +15.3% | +8.9% | +17.6% | |
OKTA | Revenue | +12.0% | +10.0% | +9.5% |
| EPS | +24.3% | +11.7% | +10.9% | |
ZS | Revenue | +25.2% | +16.9% | +16.7% |
| EPS | +29.0% | +11.2% | +17.6% | |
FTNT | Revenue | +19.8% | +11.3% | +10.9% |
| EPS | +27.0% | +9.4% | +13.3% | |
NET | Revenue | +33.7% | +28.7% | +27.5% |
| EPS | +38.0% | +32.5% | +35.3% | |
S | Revenue | +22.4% | +19.9% | +17.6% |
| EPS | +723.4% | +83.7% | +43.0% | |
RBRK | Revenue | +48.7% | +28.4% | +21.5% |
| EPS | −90.5% | −278.6% | +106.1% | |
TENB | Revenue | +8.4% | +7.1% | +6.9% |
| EPS | +27.0% | +10.5% | +10.1% | |
QLYS | Revenue | +8.6% | +7.0% | +6.6% |
| EPS | +8.6% | +9.2% | +5.3% | |
CHKP | Revenue | +3.2% | +6.0% | +5.6% |
| EPS | −7.5% | +9.6% | +9.1% | |
MSFT | Revenue | +18.0% | +18.2% | +19.6% |
| EPS | +26.7% | +15.4% | +18.5% |
Forward fiscal years only. Blank means no analyst coverage for that year.
CrowdStrike, which sells cloud-delivered endpoint, identity and cloud-workload protection as subscriptions to its Falcon platform, reported its July quarter after the close on 26 August: revenue of $1.47bn, up 25.8%, and net new annual recurring revenue of $332.8m, a record and up 51%. The next session, twelve listed security vendors rose together. Palo Alto Networks, which has published no financial statement since April, rose 11.4% of them.
That is the stake this week. A sector that has roughly doubled since the start of May had, until Wednesday night, almost no fresh audited evidence underneath it. CrowdStrike has now supplied some. Palo Alto supplies its own after the close on Tuesday, 1 September.
What CrowdStrike actually disclosed
Revenue growth accelerated for a fourth straight quarter, from 22.2% three quarters ago to 25.8%. Gross profit grew faster than revenue, up 27.7%, as gross margin widened 111 basis points to 74.6%. The number that matters most against the long shadow of the July 2024 outage is the subscription line: GAAP subscription gross margin was 78%, up from 77% a year earlier. The discounting embedded in post-outage customer packages is not visible in the economics.
Underneath, ending ARR reached $5.84bn, up 25%. Commitments through Falcon Flex, the pooled-licensing construct that lets customers draw down across modules, exceeded $2.29bn and more than doubled year on year. Next-generation security information and event management — the log-analytics business CrowdStrike is taking from Splunk-era incumbents — reached $695m of ARR, up 60%. The company said its separately priced AI detection and response module nearly tripled its ARR in a single quarter. Management raised the full-year outlook for net new ARR growth by 630 basis points, to 34% at the midpoint, the second consecutive quarterly raise.
"We are in an arms race," co-founder and chief executive George Kurtz told investors on the 26 August call. "AI is driving more cyber attacks. AI is driving more cyber spending."
The mechanism has a name and a date
The budget shift is traceable. Anthropic's release of its Mythos model, capable of exploiting previously unknown software vulnerabilities, converted AI from a claim on security budgets into a source of them; Kurtz called it "the Mythos moment." Black Hat in early August had already pushed both names to records. On 27 August, 116 companies and entities including OpenAI, Anthropic, Microsoft and AMD signed a letter stating that "We have a limited window to strengthen cyber defenses." Okta reported the same evening as CrowdStrike and rose 27.5%. Microsoft, the largest incumbent competitor in endpoint and security operations, rose 0.8%.
Palo Alto's evidence is four months old
In its April quarter, Palo Alto's revenue rose 31.1% — but $388m of it came from the acquired CyberArk and Chronosphere businesses, leaving organic growth near 14%. Purchase accounting cut gross margin 5.4 points to 67.6%, gross profit grew 21.5% against that 31% headline, and GAAP operating income swung to a loss of $183m from a profit of $219m. The organic evidence that does hold up is contractual: next-generation security ARR grew 28% excluding acquisitions, and remaining performance obligations 23% — both running well ahead of organic revenue, which is what longer contracts look like rather than deeper discounts. "Q3 was a standout quarter," chairman and chief executive Nikesh Arora said on 2 June, "with accelerating organic bookings growth as customers turn to us to secure their AI deployments at scale." Guidance for the quarter now due calls for next-generation security ARR of $8.90bn to $8.95bn.
What the price has done with it
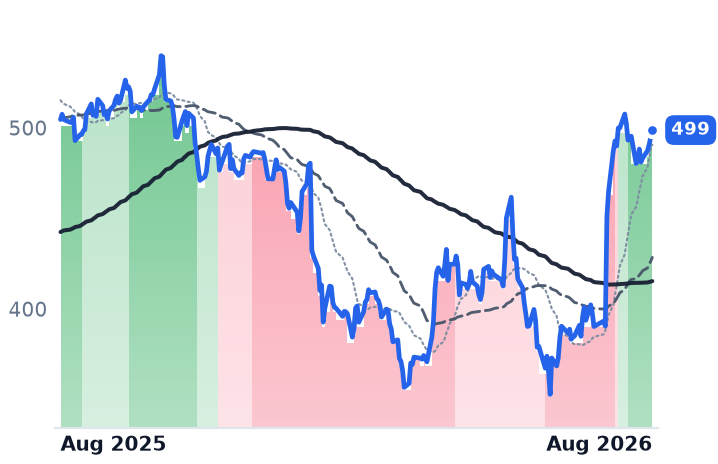
CrowdStrike's four-for-one split on 2 July makes its chart misleading; adjusted, the shares are up 95% since 1 May, in line with the group. Its price to trailing gross profit has gone from 32 times on 3 May to 57 times, against gross-profit dollars up 26% over the past year. Palo Alto's went from 20 times to 41 times on gross profit up 17%, and its forward price-to-earnings ratio is 93 times consensus for fiscal 2027 — a year in which consensus has earnings growing 8.9%, down from 15.3%.
So: CrowdStrike earned its business move and has been paid roughly three times over for it. Palo Alto's re-rating is identically shaped and rests on a print that has not happened. The demand mechanism is common to both and looks real; the distinction now is disclosure. One company has shown the money arriving in ARR, in margin and in raised guidance. The other has shown a backlog from April and a promise.
Tuesday settles half of it. If Palo Alto's fourth quarter holds acquisition-adjusted growth near where April left it, the sector's summer will look like the market pricing a budget cycle early. If it does not, Palo Alto will have doubled on somebody else's earnings call.