

Wi-Fi 7 Replacement Wave Lifted Campus Orders 20% at Cisco and Hewlett Packard Enterprise
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Both Cisco and Hewlett Packard Enterprise are riding an office-network replacement cycle neither had to invent, and neither is being paid for it where it counts. HPE's Networking segment — the home of the Juniper acquisition — more than doubled reported revenue but grew about 10% on a like-for-like basis, and its operating margin fell to 21.6% from 25.0%. The profit dollars came from servers and AI systems instead.
At Cisco the split runs the other way: hardware carried an 18% revenue quarter while annualized recurring revenue grew 3%. And charged for the debt it took on to buy Juniper, HPE at 22.2 times earnings before interest, tax, depreciation and amortization is no longer cheaper than Cisco. HPE reports again on September 2.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
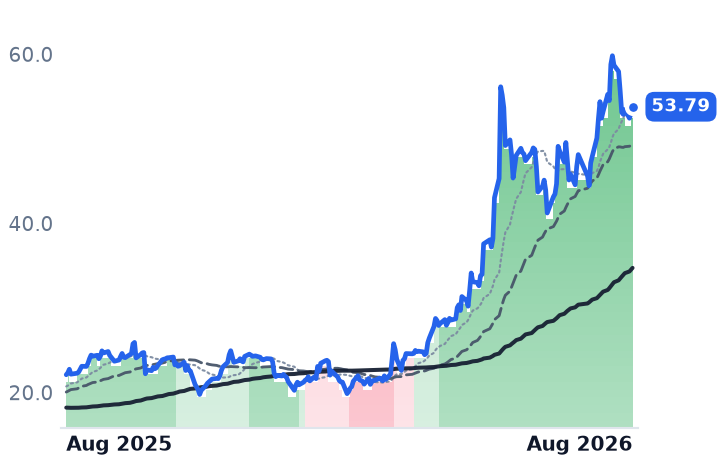
HPE | Hewlett Packard Enterprise | Enterprise Storage & Software | 🟢 Cont. Bull | +18.0% | +143.3% |
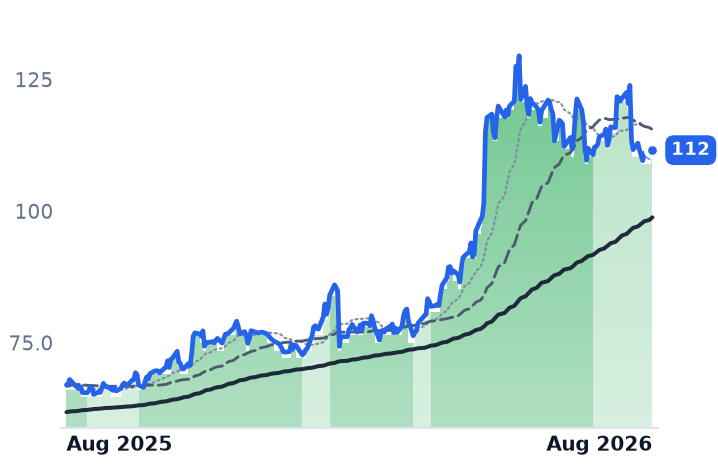
CSCO | Cisco Systems | Enterprise Networking Infrastructure | 🟢 Cont. Bull | −2.6% | +66.5% |
| Compared against · context, not the story | |||||
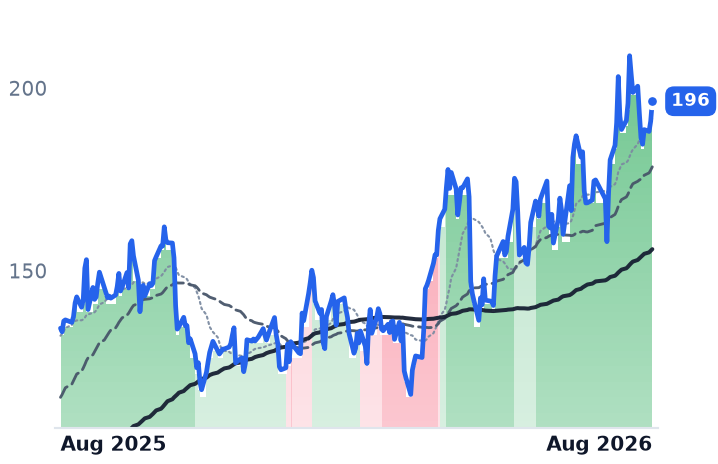
ANET | Arista Networks | Cloud Networking | 🟢 Cont. Bull | +15.7% | +46.3% |
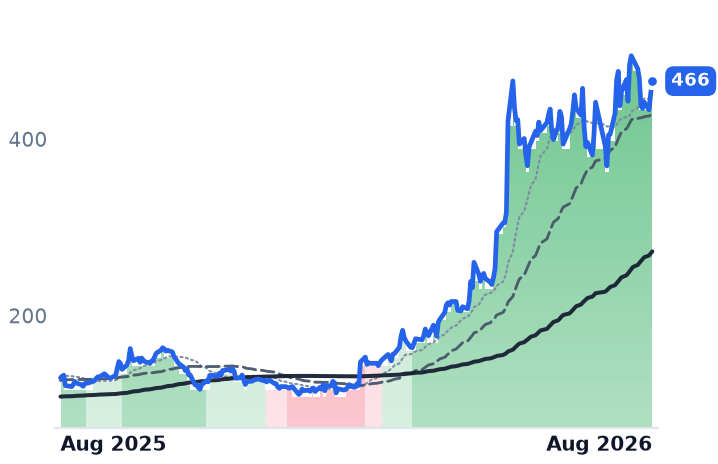
DELL | Dell Technologies | Enterprise Storage & Software | 🟢 Cont. Bull | +18.8% | +259.5% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
HPE | $73.1B | 50.7x | 16.1x | 1.9x | 1.6x | 5.7x | 4.9x | 22.2x | 5.5% |
CSCO | $442.9B | 33.4x | 21.9x | 7.0x | 6.1x | 10.8x | 9.4x | 23.2x | 3.1% |
ANET | $237.5B | 58.8x | 45.9x | 22.5x | 18.7x | 35.8x | 29.8x | 46.1x | 2.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DELL | $308.2B | 36.3x | 24.6x | 2.3x | 1.8x | 12.1x | 9.3x | 22.2x | 3.1% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
HPE | Revenue | +30.5% | +11.6% | +5.8% |
| EPS | +81.3% | +18.7% | +10.1% | |
CSCO | Revenue | +11.1% | +16.2% | +7.1% |
| EPS | +12.9% | +19.7% | +9.2% | |
ANET | Revenue | +42.4% | +30.0% | +23.9% |
| EPS | +42.4% | +27.2% | +22.5% | |
DELL | Revenue | +16.2% | +55.3% | +14.9% |
| EPS | +27.3% | +89.4% | +21.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Networking's headlines this month belonged to the racks behind artificial-intelligence training clusters, where Nvidia took the lead in data-center Ethernet switching revenue. The disclosures underneath those headlines describe something quieter and, for two incumbents, larger: the office wiring closet is in the middle of a hardware replacement wave, and it lifted orders at Cisco and Hewlett Packard Enterprise by roughly a fifth in their most recent quarters.
That is the half of networking neither company can outsource to a hyperscaler order book. For HPE — the Houston server, storage and networking group run by Antonio Neri — campus and branch is the business it paid about $40.00 a share, some $14bn in cash, to enlarge when it bought Juniper Networks. For Cisco, which sells campus and data-center switching, enterprise routing, wireless, security and observability software, chief executive Chuck Robbins named campus refresh as one of four legs of what he called a networking "super cycle" on the August 12 call. The question is what the refresh actually earns.
The mechanism is a radio standard
Wi-Fi 7 took 39.7% of enterprise wireless-LAN access-point revenue in the fourth quarter of 2025, up from 10.25% a year earlier, and Dell'Oro expects the curve to be steeper than any prior generation because there is no intermediate product for buyers to wait for — every new access point needs multi-gigabit switching beneath it. A second force inflates the same order line without adding units: component shortages created by AI data-center construction have pushed through repeated price increases on campus switches. The enterprise network equipment market as a whole is forecast to grow about 11.8% this year, to $93.39bn — slower than either company's campus orders grew.
HPE: the revenue arrived, the margin did not
HPE's Networking segment reported $2.7bn of revenue in the quarter to April 30, up 148.2% — almost entirely acquired. Routing contributed $775m against $1m a year earlier. Strip the arithmetic of the acquisition and normalized Networking revenue grew 10%, with campus and branch orders at a record and up more than 20% on the same basis. Segment operating margin fell to 21.6% from 25.0% — a figure distinct from the 13.3% group non-GAAP operating margin reported the same day. Juniper is diluting networking profitability while it is being absorbed.
The profit dollars came from elsewhere. The merged Cloud & AI segment — servers, hybrid cloud and financial services — turned $7.707bn of revenue at a 12.4% margin into roughly $956m of segment operating profit, against about $581m from Networking. Chief financial officer Marie Myers told investors HPE expects to exceed its $200m fiscal 2026 synergy target, with $600m of annual run-rate savings targeted by fiscal 2028; she located the savings in "workforce transformation" and process simplification rather than in networking product economics. Diluted shares rose 8.3% year over year, and $1.35bn of mandatory convertible preferred converts into roughly 68m to 84m common shares around September 2027.
Cisco: the boxes grew, the software didn't
Cisco's July-quarter revenue rose 17.6% to $17.252bn, with networking product revenue up 28% and campus switching orders up 20%. Its recurring franchise is the flat part: annualized recurring revenue reached $32.1bn, up 3%, observability revenue grew 6%, and remaining performance obligations of $46.7bn grew 7%. Contracted future revenue is compounding at a fraction of recognized revenue. "You should expect a slight gross margin headwind as we move through FY 2027 as we address these very high growth opportunities," chief financial officer Mark Patterson said on August 12, attributing it to hardware mix.
What the two disclosures settle
The campus wave is real and both companies are capturing it above market growth. Neither is being repriced for it. HPE's shares have risen 139% in twelve months against 35% growth in trailing gross profit; at 5.71 times trailing gross profit it looks half Cisco's 10.84 times, but on enterprise value to earnings before interest, tax, depreciation and amortization — which charges HPE for the Juniper borrowings — it trades at 22.2 times against Cisco's 23.2. The cheapness is an artifact of where the debt sits. Cisco, meanwhile, has de-rated toward 21.9 times forward earnings from roughly 18 times in May while its hardware accelerated and its software stalled, which is a legitimate verdict on mix rather than on demand.
HPE reports fiscal third-quarter results on September 2, the second quarter with Juniper fully inside the segment. Normalized Networking growth and that 21.6% margin are the two lines that say whether the campus refresh is a business HPE bought or a business it is still paying for.