

Vertiv Stopped Disclosing Backlog After Entering 2026 With $15bn on the Books
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Vertiv's June quarter beat guidance and raised the full year, and the shares fell 17.3% that day. The reason was an absence: the release carried no backlog figure and no orders number, after the company entered 2026 headlining a $15bn book. Orders are where its case lives — the claim that liquid cooling and 800-volt power raise the dollars of content it sells per megawatt of computing load, well before that content ships.
nVent did the opposite, disclosing a $2.5bn backlog and 47% organic growth against 53% reported, with its infrastructure vertical up more than 100% organically. Advanced Energy's sequential upside came from semiconductor plasma power, up 27% quarter on quarter, while its data-center revenue slipped 1%.
All three raised guidance. Only nVent's twelve-month share gain is mostly backed by gross-profit growth.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
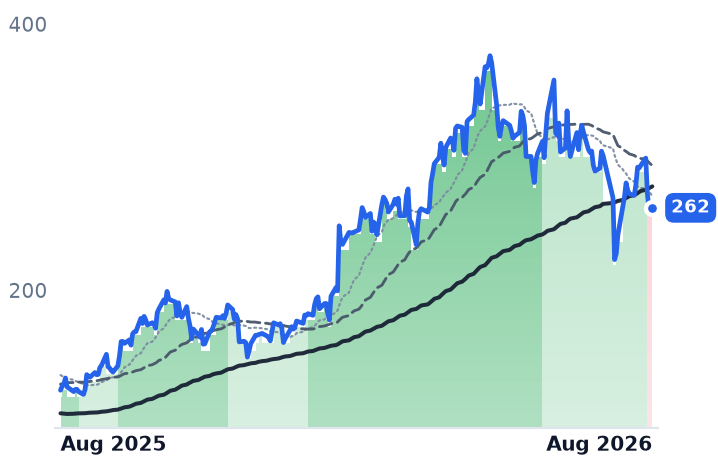
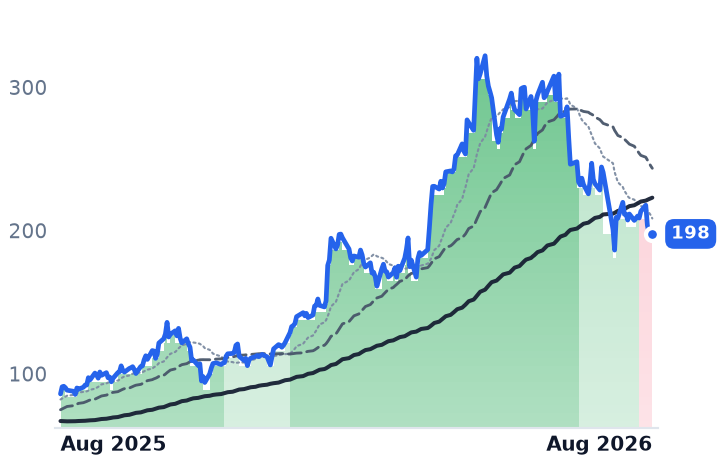
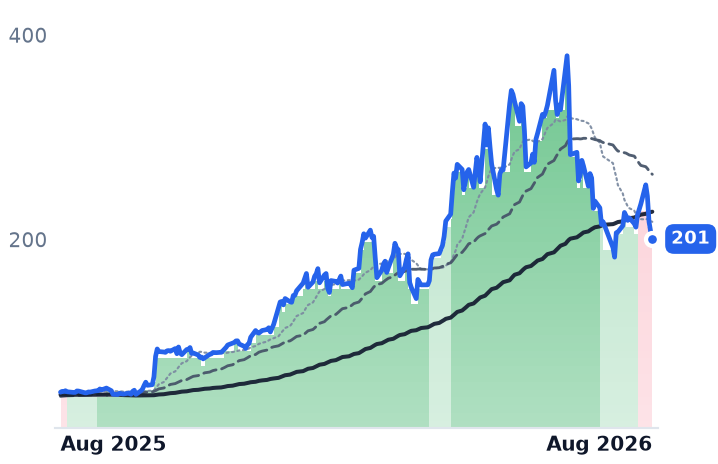
VRT | Vertiv | Data Center Power & Thermal | 🟢 Cont. Bull | −2.8% | +109.7% |
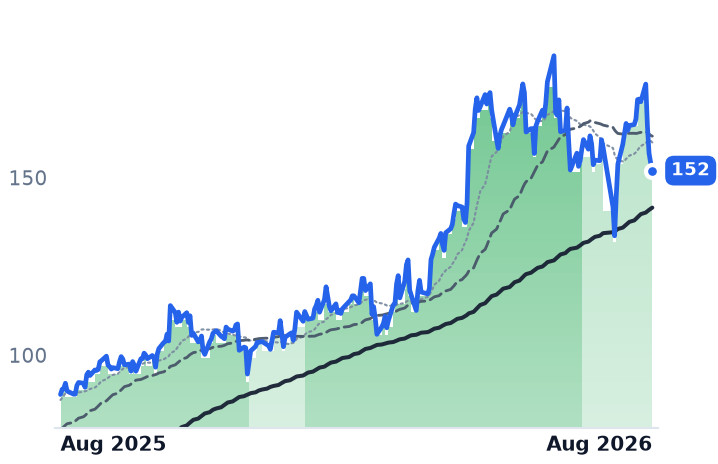
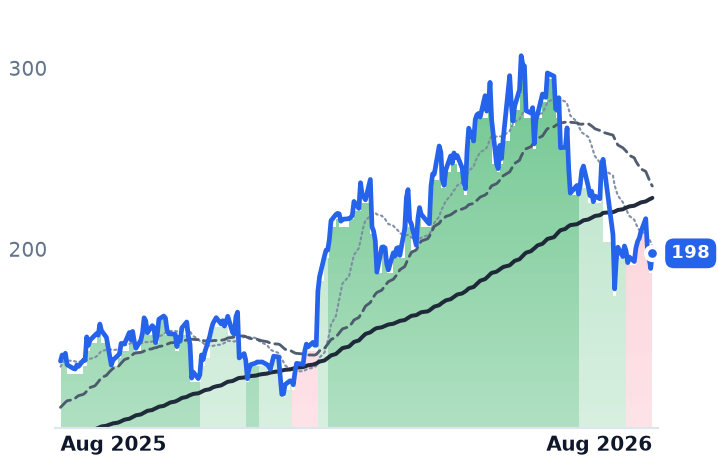
NVT | nVent Electric | Data Center Power & Thermal | 🟢 Cont. Bull | +7.2% | +70.9% |
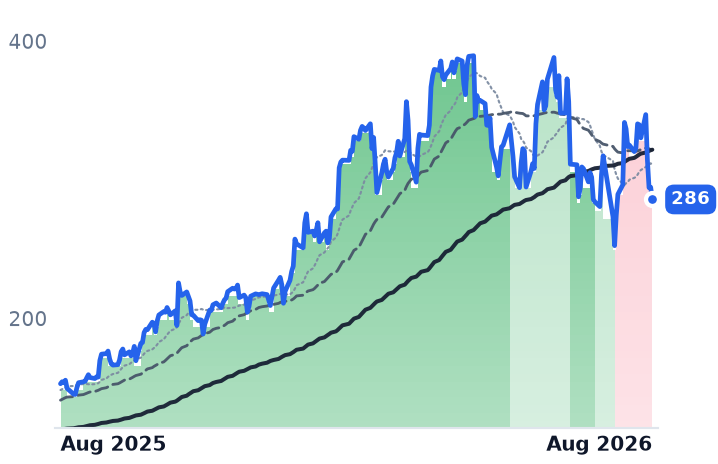
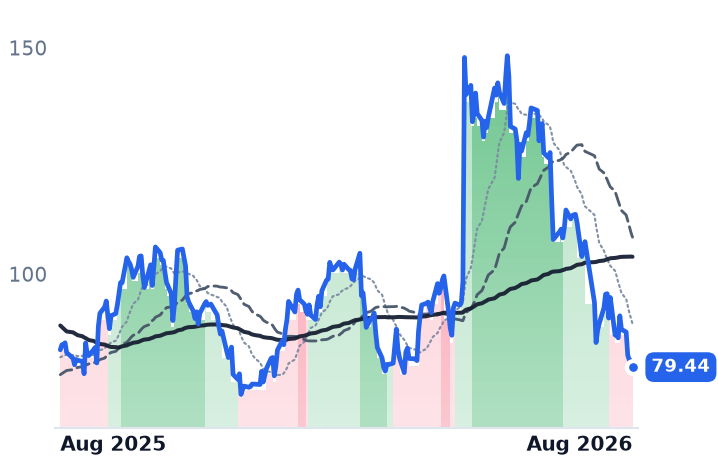
AEIS | Advanced Energy Industries | Data Center Power & Thermal | ⚠️ Emerging Bear | +4.5% | +87.0% |
| Compared against · context, not the story | |||||
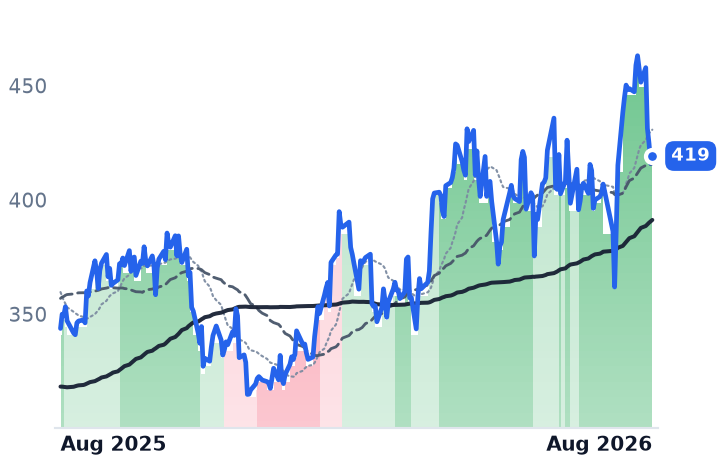
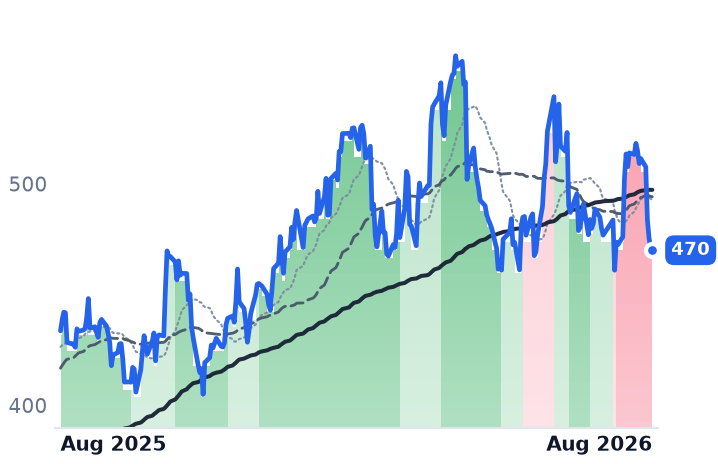
ETN | Eaton | Power & Propulsion Systems | 🟢 Cont. Bull | +8.5% | +22.0% |
POWL | Powell Industries | Electrical Distribution & Switchgear | 🟢 Cont. Bull | −1.7% | +129.8% |
MOD | Modine Manufacturing | Thermal & Powertrain Components | 🟢 Cont. Bull | −5.0% | +43.1% |
AAON | AAON | HVAC Systems | 🌱 Emerging Bull | −15.3% | −4.6% |
HUBB | Hubbell Incorporated | Electrical Distribution & Switchgear | ⚠️ Emerging Bear | −2.8% | +8.4% |
VICR | Vicor | Other | 🟢 Cont. Bull | +4.4% | +295.5% |
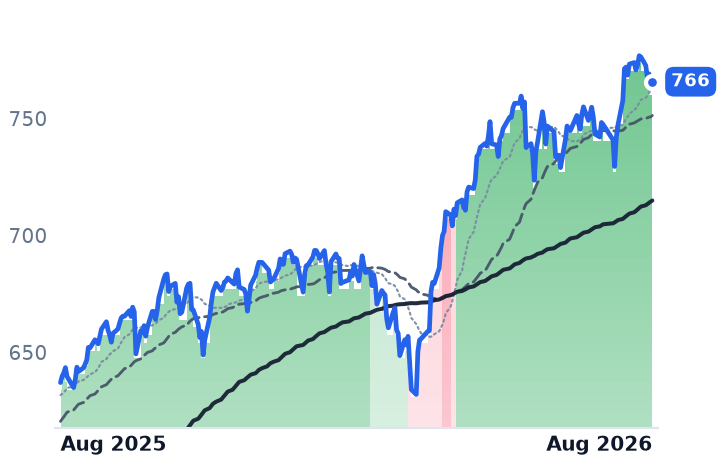
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | +3.4% | +20.2% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
VRT | $100.8B | 58.0x | 39.0x | 8.8x | 7.2x | 23.4x | 19.2x | 40.1x | 2.9% |
NVT | $24.6B | 41.2x | 29.9x | 5.1x | 4.5x | 13.8x | 12.3x | 25.8x | 2.4% |
AEIS | $11.4B | 49.5x | 25.4x | 5.6x | 4.7x | 14.1x | 11.9x | 37.7x | 0.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ETN | $162.8B | 42.5x | 31.0x | 5.4x | 5.0x | 15.1x | 13.8x | 28.4x | 2.8% |
POWL | $7.2B | 37.7x | 36.5x | 6.2x | 6.0x | 20.7x | 20.0x | 26.4x | 3.4% |
MOD | $14.3B | 146.4x | 34.3x | 5.0x | 3.7x | 20.9x | 15.7x | 57.0x | 0.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AAON | $6.5B | 40.9x | 33.6x | 3.4x | 2.8x | 13.2x | 11.1x | 21.8x | -1.8% |
HUBB | $24.8B | 27.7x | 23.0x | 4.0x | 3.6x | 11.3x | 10.3x | 20.3x | 3.6% |
VICR | $9.1B | 62.9x | 58.4x | 19.2x | 15.1x | 33.9x | 26.6x | 67.8x | 0.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
VRT | Revenue | +37.0% | +29.7% | +21.9% |
| EPS | +62.8% | +36.4% | +27.1% | |
NVT | Revenue | +41.5% | +19.4% | +14.7% |
| EPS | +52.7% | +27.3% | +19.8% | |
AEIS | Revenue | +36.0% | +24.1% | +17.2% |
| EPS | +79.8% | +35.1% | +22.0% | |
ETN | Revenue | +19.6% | +10.6% | +9.4% |
| EPS | +12.2% | +18.2% | +16.4% | |
POWL | Revenue | +8.8% | +25.8% | +14.5% |
| EPS | +12.7% | +24.1% | +32.7% | |
MOD | Revenue | +22.6% | +21.8% | +19.1% |
| EPS | +33.4% | +52.5% | +31.7% | |
AAON | Revenue | +64.7% | +16.7% | +13.6% |
| EPS | +67.7% | +51.2% | +27.9% | |
HUBB | Revenue | +17.1% | +9.7% | +5.7% |
| EPS | +12.2% | +11.7% | +10.7% | |
VICR | Revenue | +33.1% | +55.6% | +22.2% |
| EPS | +58.9% | +73.2% | +33.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Vertiv Holdings, which builds the uninterruptible power supplies, busway, rack power distribution units and thermal loops inside data centers under the Liebert and Geist brands, reported a June quarter on 29 July that beat its own earnings guidance and lifted full-year revenue guidance to $14bn. It also left out the two numbers it had led with all year. The release carried no backlog figure and no orders number, after a year-ago quarter headlined with $8.5bn of backlog and a book-to-bill near 1.2x. The shares fell 17.3% that session, from $269.56 to $223.04.
The omission matters because the orders line is where Vertiv's argument is supposed to be visible. The company's pitch is that direct-to-chip cooling and higher-voltage power distribution raise the dollars of equipment it sells per megawatt of computing load — content booked long before it is shipped. Strip out orders and backlog and the business is judged on revenue that has decelerated: up 30.1% in the March quarter, up 24.1% in June to $3.274bn.
What Vertiv did say
The profit side was not the problem. Gross profit rose 45.5% as gross margin widened 555 basis points to 37.7%, operating margin reached 19.5% from 17.2%, and free cash flow of $925m came in at more than 150% conversion, leaving the company in a net cash position. Vertiv told the SEC that sales of $3,274m reflected 18% organic growth, and attributed the shortfall against roughly $3.38bn of consensus to temporary supply-chain congestion and the timing of multi-phase projects.
On content, chief executive Giordano Albertazzi was explicit. "As a number of viable power architectures expand, and AC and DC coexist to deliver on the 800 VDC, Vertiv's content opportunity per megawatt expands, and we're leading this transition," he said on the call. Asked whether the 800-volt direct-current offering could reach the top of a $3.25m–$3.75m per-megawatt range, he answered: "We are pretty convinced about that." The timing is the catch — that architecture is in customer validation this year for 2027 deployment, with a medium-voltage DC uninterruptible supply behind it for 2028. The franchise is real, and it includes a collaboration with Nvidia on an 800-volt rack and pod architecture; what went missing is the metric that verifies customers are buying it yet.
nVent printed the number
nVent Electric, which sells enclosures, busbar and liquid-cooling hardware through electrical distributors and data-center installers, disclosed a $2.5bn backlog and grew 52.8% reported against 47% organic — the EPG acquisition contributed seven points. Its infrastructure vertical grew more than 100% organically and now runs near 60% of first-half sales, against 12% at the 2018 spin. Full-year organic guidance went to 32–34% from 21–23%. Chief executive Beth Wozniak said data-center sales should exceed $2bn in 2026, more than double last year, with "a significant contribution coming from liquid cooling." That mix costs something at the gross line — gross margin slipped to 37.9% from 38.6% — while operating margin rose to 20.4% from 16.3%. Tariffs are now put at about $100m for the year, up from $80m, because volumes grew. nVent's own reading is that liquid cooling is still only 10–15% of data-center cooling, which is why it doubled capacity at Blaine, Minnesota and announced a second plant there.
Advanced Energy Industries, which makes plasma power supplies for wafer processing and DC-DC modules for servers, is the check on whether this is one story. Revenue rose 30.0% with gross margin at 41.1%, but semiconductors were 48% of sales and up 27% sequentially, while data-center computing at 33% of sales fell 1% sequentially. Its own 800-volt revenue is not expected until late 2027.
How much of the year was earned
Over twelve months to 21 August, Vertiv rose 107.0%, Advanced Energy 93.0% and nVent 72.7%. Split those into gross-profit growth and change in price paid per dollar of gross profit, and the group separates. nVent grew trailing gross profit 37.9% while its multiple went from roughly 11.0x to 13.8x — about 60% earned, the most of the three. Vertiv split its gain almost evenly, gross profit up 42.5% against a move from 16.1x to 23.4x. Advanced Energy earned least: a $1.15bn convertible lifted diluted shares 11.9%, leaving gross profit per share up around 20%.
The recent weakness is mostly not company-specific. In four sessions from 17 to 21 August, when the 30-year Treasury yield topped 5.33%, Vertiv fell 12.5%, nVent 13.8% and Advanced Energy 17.6% against the S&P 500 tracker's 0.9%, with Eaton down 8.4% and Vicor down 20.9%. None of the three reported anything in that window. All three have de-rated since spring even as gross profit grew — Vertiv from 32.5x price to trailing gross profit in May to 23.4x now, against 19.2x forward; nVent sits at 13.8x trailing and 12.3x forward, Advanced Energy at 14.1x and 11.9x.
Demand is confirmed on every line these companies still publish. What the quarter changed is which company can be checked. nVent's re-rating rests on disclosed organic infrastructure growth and a printed backlog; Advanced Energy's data-center line went sideways for a quarter while semiconductor equipment carried it. Vertiv stakes the most on content per megawatt and, this quarter, supplied nothing that shows customers ordering it.
Vertiv has guided the September quarter to $3.75bn, up 40%. That number will arrive; whether the backlog line arrives with it is the question the July release opened.