

Palo Alto's Stock Doubled While Its Gross Profit Grew 5% in Six Months
Prompt v1.4
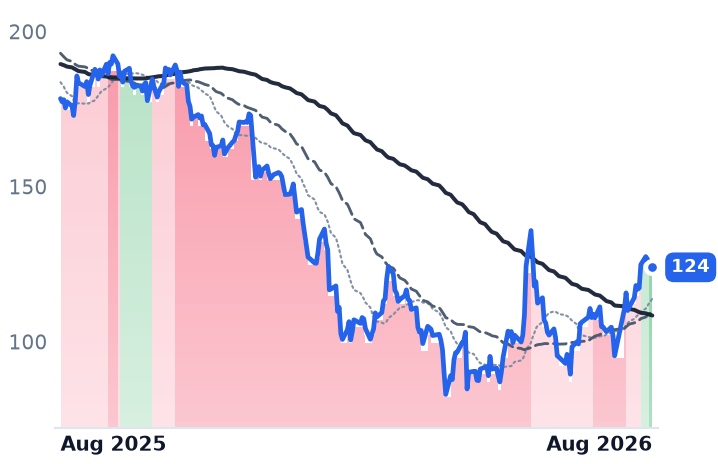
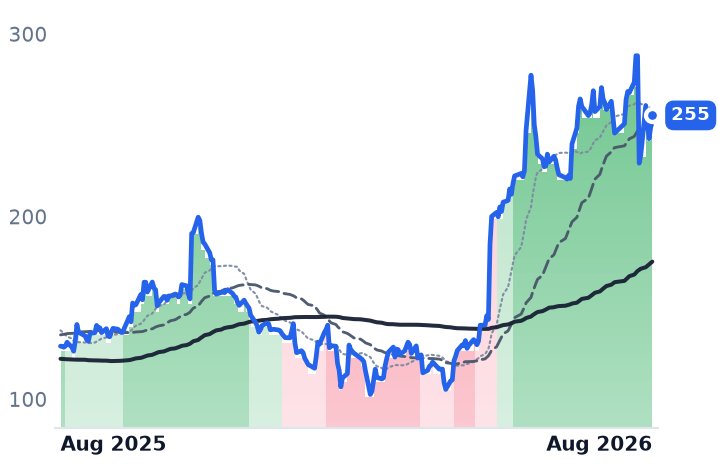
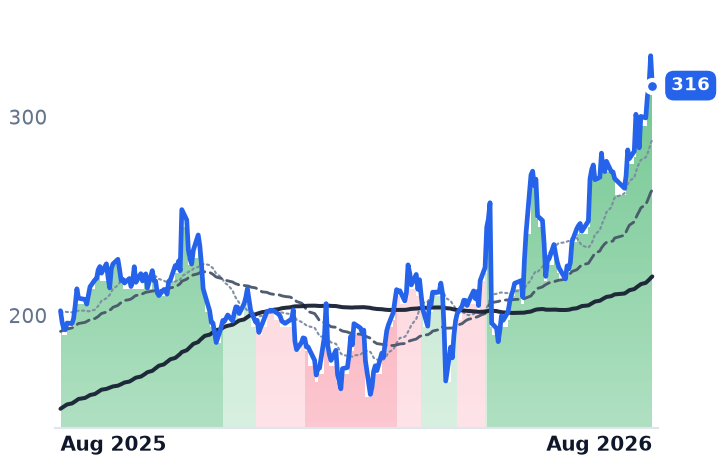
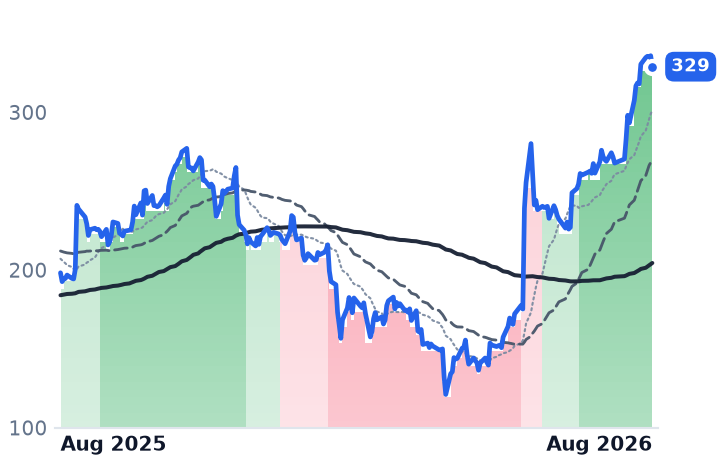
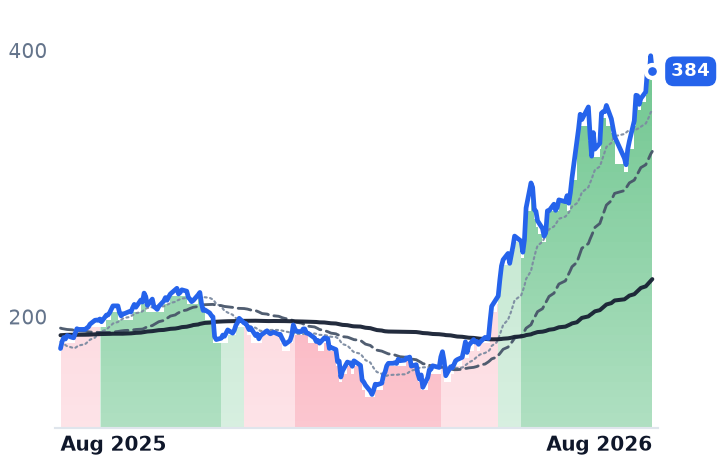
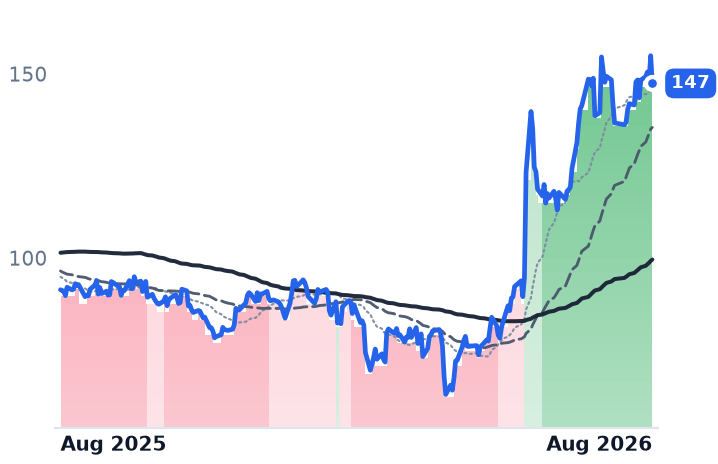
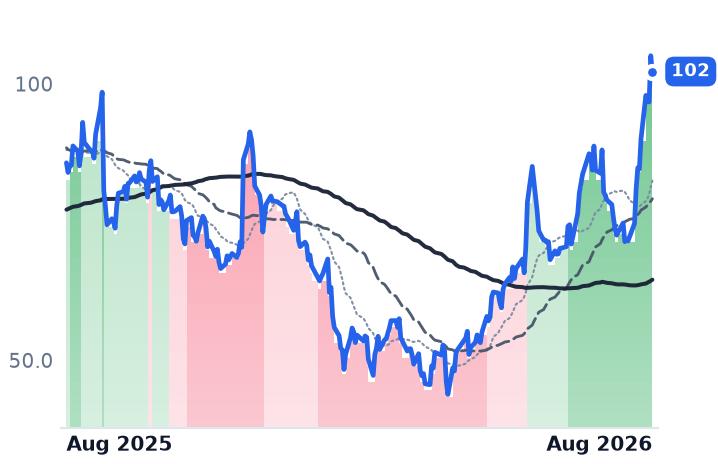
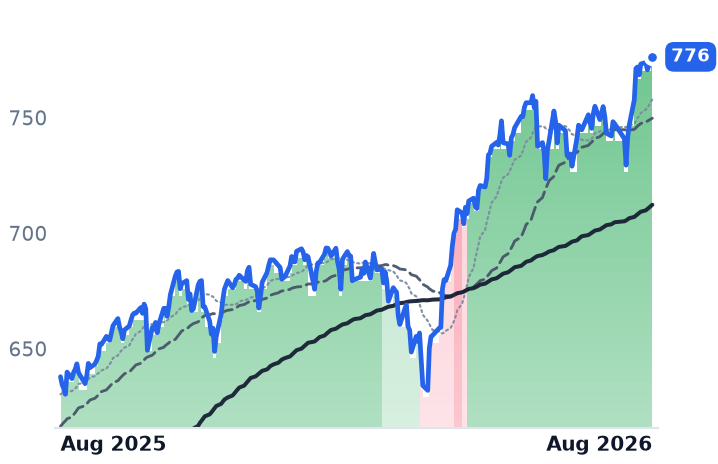
Enterprise software was sold in early 2026 on the theory that AI agents would eat software seats. Since mid-February seven of the names at the center of that trade have risen a median 80%, against 13.9% for the S&P 500 — and the businesses underneath grew trailing gross profit a median 13%.
Every one of the seven now costs more per dollar of gross profit than it did in February, from about 8% more at ServiceNow to 119% at Palo Alto Networks, whose gross profit grew 4.9%. Four of them did earn something: ServiceNow, Datadog, Cloudflare and Snowflake all posted faster revenue growth than a year ago. Okta is guiding to 9-10% growth for the year, and Rubrik has decelerated four quarters running. Four of the seven have published no financials since spring.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
NOW | ServiceNow | Sales, Service & Customer Management | 🔴 Cont. Bear | +20.1% | −30.5% |
DDOG | Datadog | Data, Analytics & Intelligence | 🟢 Cont. Bull | −1.2% | +97.9% |
NET | Cloudflare | Cybersecurity & Threat Protection | 🟢 Cont. Bull | +13.7% | +56.0% |
SNOW | Snowflake | Data, Analytics & Intelligence | 🟢 Cont. Bull | +22.3% | +65.9% |
PANW | Palo Alto Networks | Cybersecurity & Threat Protection | 🟢 Cont. Bull | +7.1% | +118.1% |
OKTA | Okta | Identity & Access Management | 🌱 Emerging Bull | −1.3% | +61.3% |
RBRK | Rubrik | Storage, Backup & Data Management | 🌱 Emerging Bull | +29.5% | +19.3% |
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | +4.4% | +21.7% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NOW | $105.8B | 72.8x | 25.8x | 6.9x | 6.5x | 9.4x | 8.9x | 32.6x | 4.5% |
DDOG | $95.4B | 539.3x | 105.9x | 24.1x | 21.3x | 30.3x | 26.8x | 365.7x | 1.2% |
NET | $128.1B | n/m | 286.2x | 51.0x | 44.7x | 70.3x | 61.5x | — | 0.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SNOW | $97.3B | n/m | 124.4x | 17.9x | 15.4x | 26.7x | 23.0x | n/m | 1.2% |
PANW | $256.9B | 682.3x | 75.0x | 22.4x | 18.1x | 31.8x | 25.8x | 166.8x | 1.6% |
OKTA | $28.2B | 99.8x | 42.9x | 9.2x | 8.7x | 11.7x | 11.2x | 66.7x | 3.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
RBRK | $21.8B | n/m | 210.2x | 14.1x | 12.9x | 17.6x | 16.1x | n/m | 1.5% |
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
NOW | Revenue | +22.6% | +18.5% | +18.1% |
| EPS | +13.5% | +21.6% | +22.2% | |
DDOG | Revenue | +31.8% | +22.4% | +22.8% |
| EPS | +25.4% | +17.0% | +22.1% | |
NET | Revenue | +33.7% | +28.4% | +27.0% |
| EPS | +38.1% | +32.6% | +34.3% | |
SNOW | Revenue | +29.4% | +35.7% | +29.0% |
| EPS | +72.3% | +82.9% | +36.4% | |
PANW | Revenue | +24.3% | +24.0% | +14.3% |
| EPS | +15.5% | +10.7% | +16.1% | |
OKTA | Revenue | +12.0% | +10.8% | +9.9% |
| EPS | +24.3% | +14.1% | +10.6% | |
RBRK | Revenue | +48.7% | +32.0% | +21.5% |
| EPS | −90.5% | −389.4% | +53.1% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Enterprise software spent the first half of 2026 being priced as a casualty of artificial intelligence. The argument was simple: if AI agents do the work that software licenses used to do, seat counts fall and revenue follows. Investors sold the sector hard enough that the episode acquired a nickname on this desk's own reading — the SaaSpocalypse. Then, from mid-February, they bought it back.
Seven companies at the intersection of software and the data-center buildout have risen a median 80% over six months: ServiceNow, which sells the workflow platform large enterprises run IT, HR and customer-service processes on; Datadog, which monitors cloud applications and bills by host and by log ingested; Cloudflare, which runs a global edge network selling security, content delivery and serverless compute; Snowflake, which sells data warehousing by the consumption credit; and three security names — Palo Alto Networks in firewalls, Okta in identity, Rubrik in backup and cyber-recovery. The S&P 500 rose 13.9% over the same stretch.
The businesses did not do that. Trailing gross profit — revenue less the cost of delivering the service, and the cleanest measure of scale when four of the seven report negative earnings — grew a median 13% over those six months. The best performer on that measure was Rubrik, at 21.1%. Every one of the seven now costs more per dollar of gross profit than it did in February: roughly 8% more at ServiceNow, 43% at Cloudflare, 55% at Rubrik, 57% at Snowflake, 59% at Okta, 77% at Datadog and 119% at Palo Alto.
What actually got better
Four of the seven have real operating news behind them. ServiceNow's revenue growth accelerated four quarters running, from 20.7% to 24.0%, reaching $3.99bn in the June quarter. Contracted revenue due within twelve months reached $13.2bn, up 21%, with subscription revenue 150 basis points above guidance, on a 98% renewal rate; annual contract value from AI products crossed $1bn. Yet management raised the full-year subscription guide by only $15m, to $15.770bn, and said roughly half the beat was an on-premise pull-forward from the third quarter. Gross margin fell to 70.7% from 77.5% a year earlier as the Moveworks and Armis acquisitions consolidated.
Datadog grew 35.6%, its fastest since 2022, with net revenue retention in the low 120s and free cash flow of $279m at a 25% margin. It then fell about 19% in one session on 6 August after disclosing that its largest AI customer renewed a nine-figure contract but will cut usage from the third quarter, taking guided growth down to 28-29%. That is consumption billing working in reverse.
Cloudflare accelerated from 30.7% to 35.9% and reported dollar-based net retention of 120%, up six points year on year, with remaining performance obligations up 38% and the full-year guide raised to about $2.87bn. It is also the most expensive name here, at 61.4x trailing gross profit and a 0.34% free-cash-flow yield.
Snowflake re-accelerated to 33.5% growth on $1.39bn of revenue — in a quarter reported on 27 May. It has published nothing since, while analysts raised targets through early August. Its operating margin is -23.4%.
Where the numbers don't follow
Palo Alto's headline 31.1% revenue growth in its April quarter came after three quarters near 15%, and gross profit rose only 21.5% as gross margin fell to 67.6% from 72.9%; operating income swung to -$183m. The step-change is acquisition arithmetic, not organic re-acceleration. The shares hit records after the Black Hat conference in August, and the company does not report again until 1 September.
Okta is decelerating — 12.7% to 11.2% across four quarters — and has guided the current fiscal year to 9-10% growth, its slowest since listing. It is the cheapest of the seven at 10.6x trailing gross profit, with a 3.7% free-cash-flow yield and expanding gross margin. Rubrik has slowed for four straight quarters, from 51.2% to 39.0%, though its operating margin improved to -13.6%; it has reported nothing since 4 June and is nonetheless the largest gainer of the past month.
The single session that carried the month
On 4 August all seven rose together, an average of 5.24% in one day — roughly 40% of the group's entire thirty-day gain. That was a market-wide rally that took the S&P 500 to a record, up 1.79%, with the main software exchange-traded fund adding nearly 5%. Strip that session out and Okta is down about 6% over the month and Palo Alto up about 3%.
The uptrends are also younger than they look. Cloudflare has held its 50-day average above its 200-day since 5 May, 68 trading sessions. ServiceNow only crossed on 12 August, after 148 consecutive sessions in a downtrend that ran from late October to May — and it remains the only one of the seven lower than a year ago, down 27%.
The setup
Where it stands — Seven software names have re-rated a median 80% in six months on gross profit that grew about 13%. Would confirm — Snowflake, Okta and Palo Alto printing revenue growth at or above their last reported rates in the next three weeks. Would invalidate — Datadog's third-quarter growth landing below the guided 28-29%, or Okta's fiscal-year guide staying at 9-10%. Watch next — Snowflake reports 25 August, Okta 26 August, Palo Alto Networks 1 September. Valuation — Price to trailing gross profit spans 10.6x at Okta to 61.4x at Cloudflare; forward sits below trailing for all seven.