

AI Data-Center Money Splits: Banks and Landlords Rally, Private Lenders Sink on Record Fees
Prompt v1.1
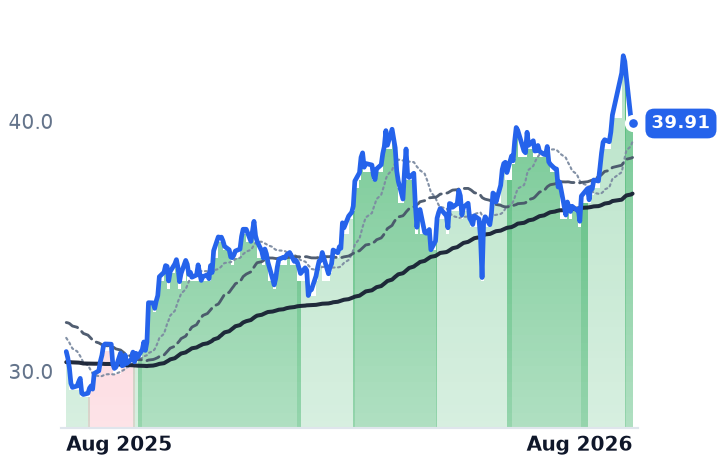
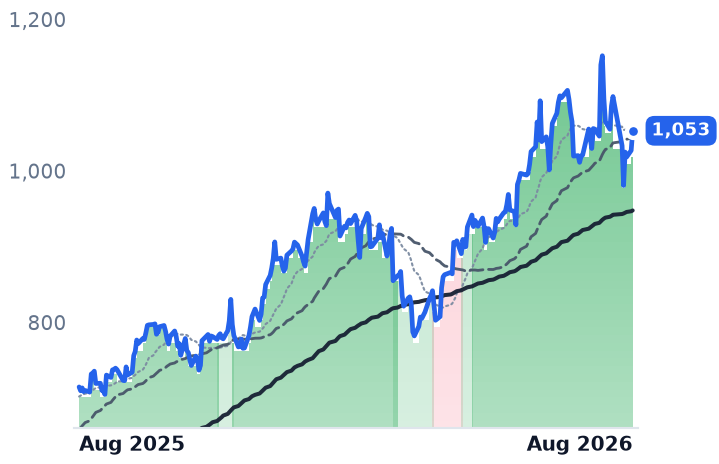
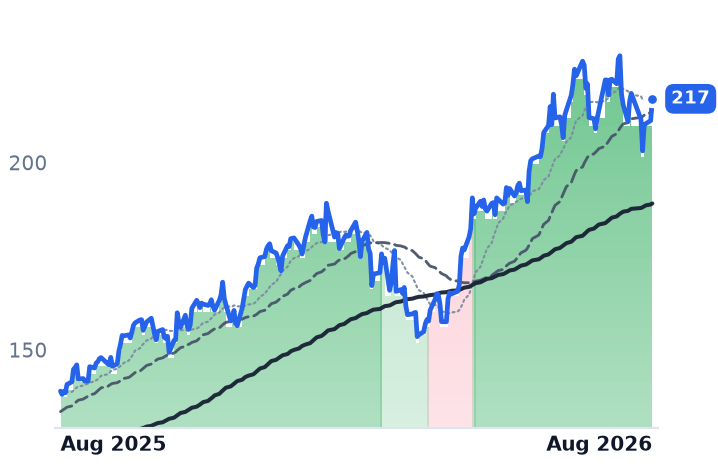
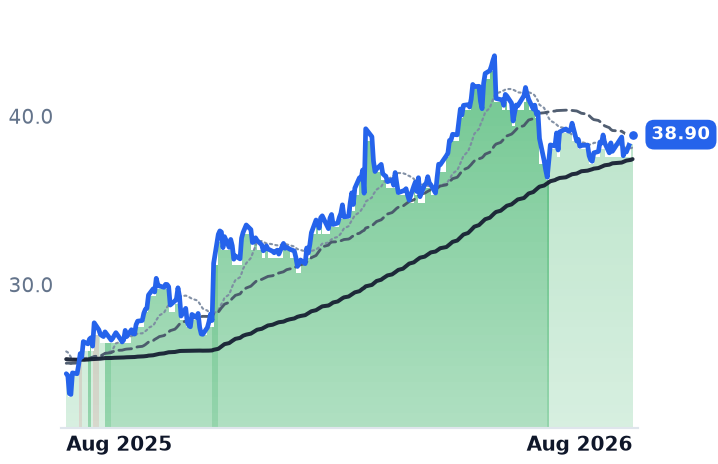
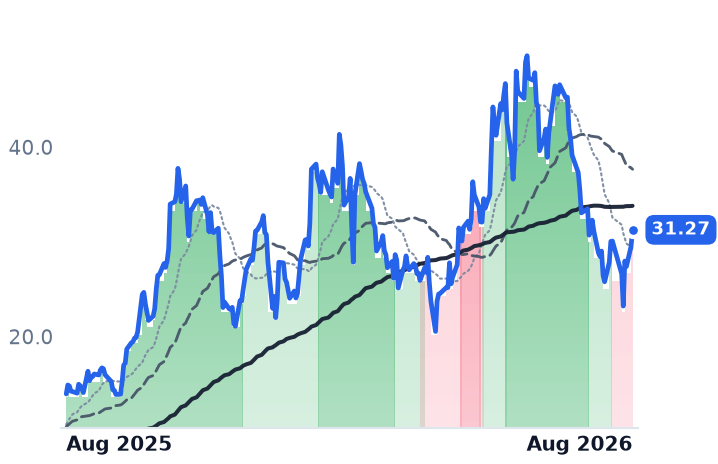
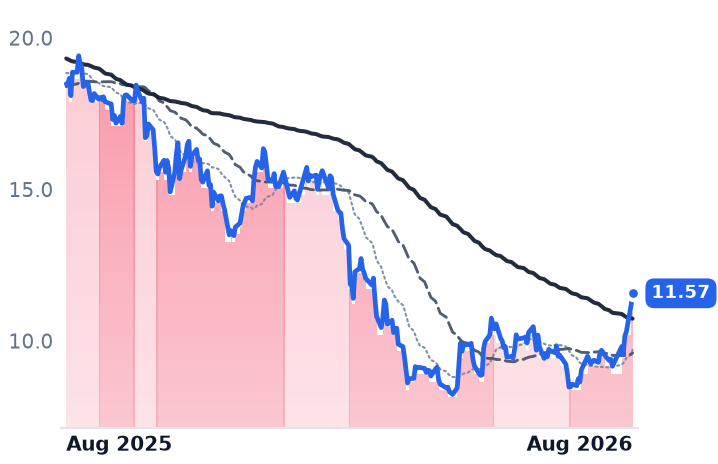
The firms that finance AI data centers have diverged sharply for a year: Goldman Sachs, Morgan Stanley and Brookfield Infrastructure are up 27-47% while Blackstone, KKR, Apollo, Ares, Brookfield Asset Management and Carlyle fell 12-29% — even as those six reported accelerating fee income and disclosed billions in new data-center lending.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
BIP | Brookfield Infrastructure Partners | Global Infrastructure | 🟢 Cont. Bull | +7.0% | +29.6% |
GS | The Goldman Sachs | Investment Banking | 🟢 Cont. Bull | −0.2% | +47.3% |
MS | Morgan Stanley | Investment Banking | 🟢 Cont. Bull | −2.3% | +56.2% |
HASI | HA Sustainable Infrastructure Capital | Middle-Market Credit | 🟢 Cont. Bull | +1.6% | +57.4% |
BX | Blackstone | Alternative Investors | 🔴 Cont. Bear | +11.2% | −17.9% |
KKR | KKR | Alternative Investors | 🔴 Cont. Bear | +12.8% | −25.1% |
APO | Apollo Global Management | Alternative Investors | 🔴 Cont. Bear | +9.0% | −5.1% |
BAM | Brookfield Asset Management | Alternative Investors | 🔴 Cont. Bear | +10.5% | −13.1% |
ARES | Ares Management | Alternative Investors | 🔴 Cont. Bear | +17.3% | −22.2% |
CG | The Carlyle | Alternative Investors | 🔴 Cont. Bear | +15.0% | −14.6% |
CRWV | CoreWeave | Cloud Compute & Infrastructure | 🌱 Emerging Bull | +6.3% | −13.3% |
NBIS | Nebius | Software Development & Design | 🟢 Cont. Bull | +6.0% | +316.7% |
APLD | Applied Digital | Cloud & Computing Infrastructure | 🟢 Cont. Bull | −6.7% | +124.2% |
OWL | Blue Owl Capital | Alternative Investors | 🔴 Cont. Bear | +21.9% | −37.4% |
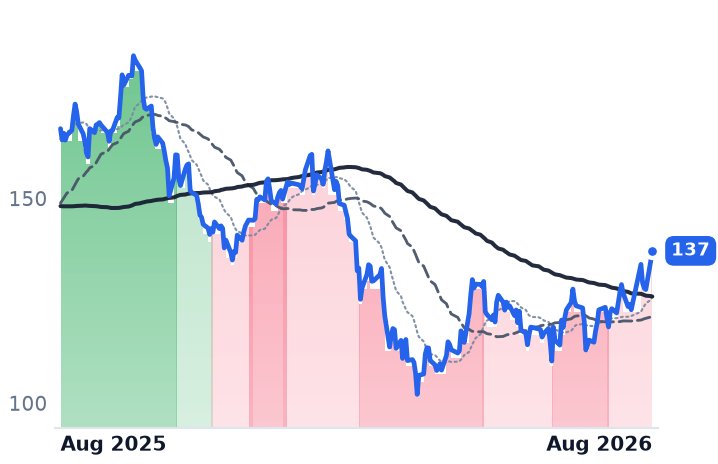
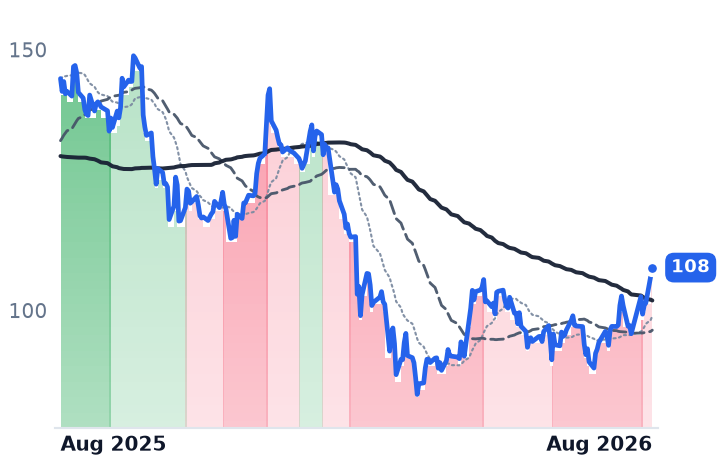
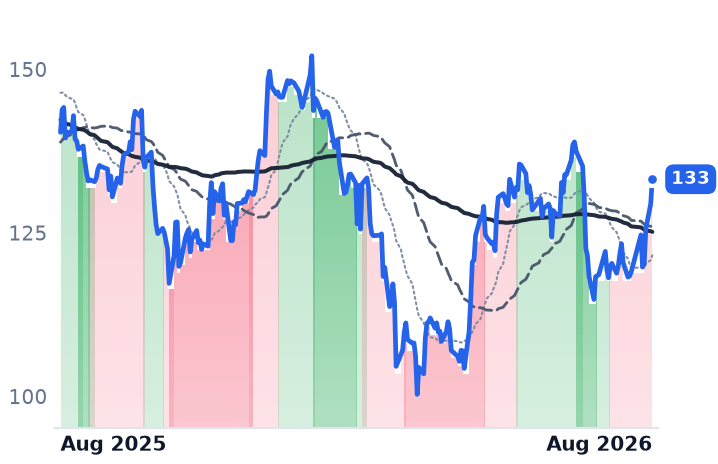
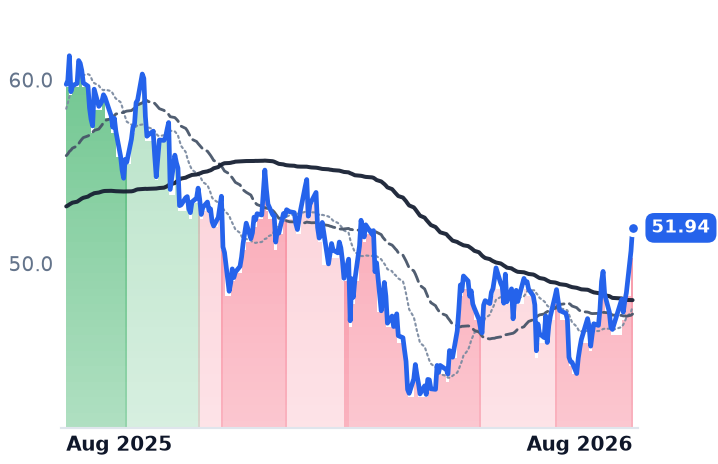
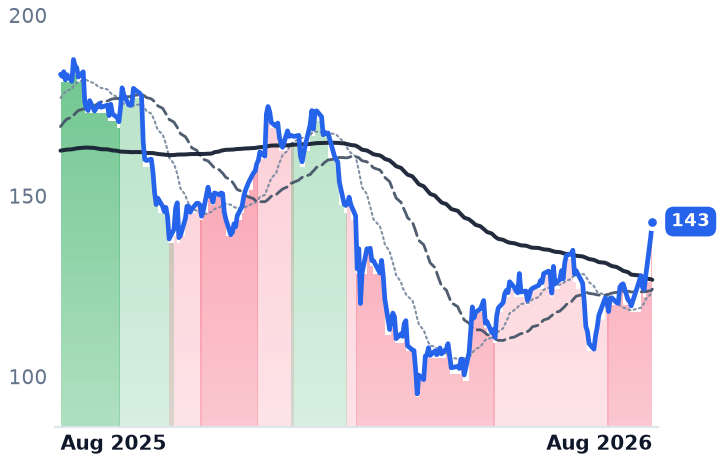
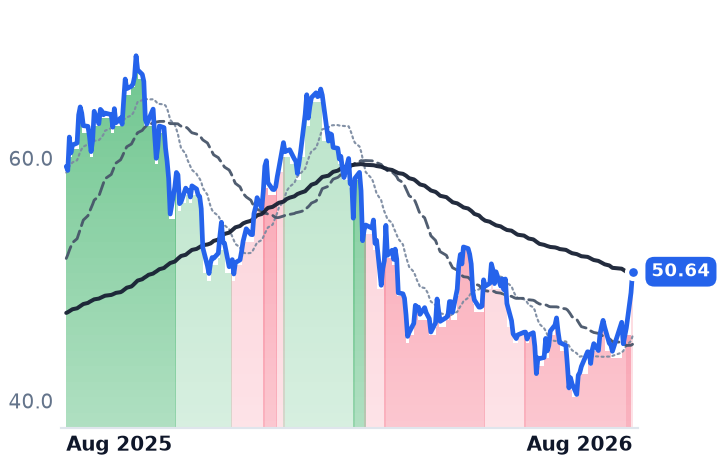
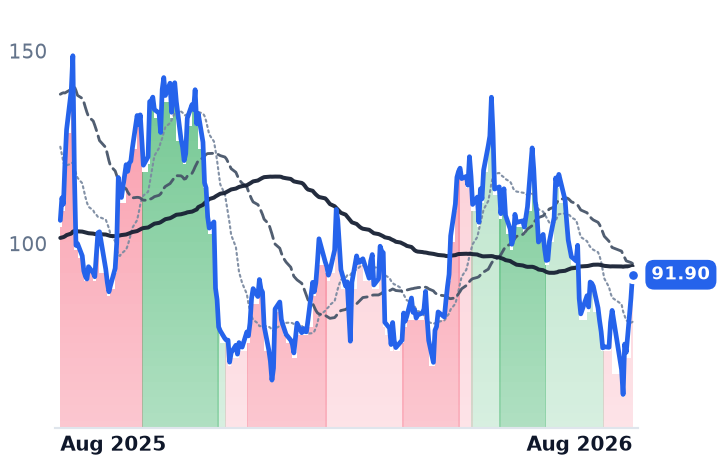
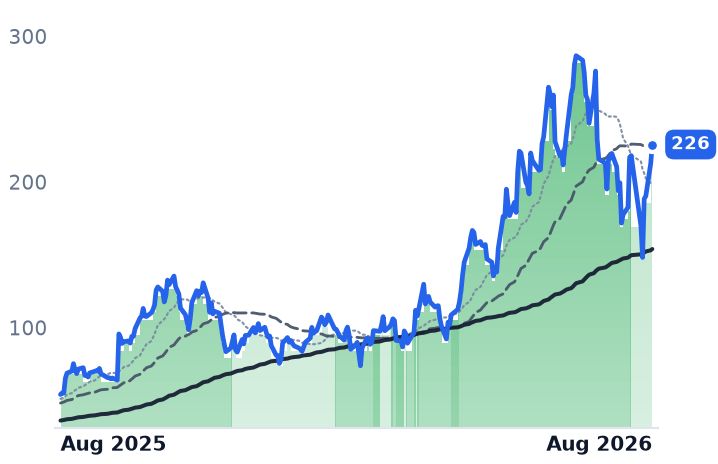
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BIP | $16.7B | 50.6x | 64.0x | 0.7x | 1.0x | 2.5x | 3.7x | 7.0x | -3.4% |
GS | $306.6B | 15.8x | 14.9x | 2.6x | 4.3x | 4.5x | 7.5x | 27.4x | -13.5% |
MS | $342.8B | 17.5x | 16.9x | 2.7x | 4.2x | 4.5x | 7.0x | 24.1x | -4.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
HASI | $5.1B | 61.0x | 13.3x | 11.1x | 11.0x | 40.2x | 39.8x | n/m | 4.1% |
BX | $135.0B | 24.8x | 18.6x | 8.4x | 9.3x | 9.5x | 10.5x | 17.4x | 3.3% |
KKR | $81.1B | 26.9x | 14.2x | 3.8x | 7.1x | 17.1x | 31.7x | 12.4x | 2.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
APO | $68.6B | 25.8x | 13.6x | 1.9x | 3.0x | 2.3x | 3.5x | 5.9x | 11.6% |
BAM | $72.2B | 26.3x | 24.9x | 13.1x | 11.7x | 17.1x | 15.3x | 19.2x | 3.4% |
ARES | $41.6B | 55.3x | 21.6x | 6.5x | 7.7x | 10.4x | 12.3x | 22.0x | 2.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CG | $17.7B | 48.7x | 13.7x | 4.5x | 4.8x | 6.3x | 6.7x | 35.2x | -11.3% |
CRWV | $35.3B | n/m | — | 4.6x | 2.8x | 6.9x | 4.1x | 20.4x | -38.7% |
NBIS | $41.3B | 661.5x | — | 30.5x | 12.3x | 41.0x | 16.6x | 43.1x | -14.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
APLD | $4.7B | n/m | — | 5.5x | 4.9x | 27.2x | 24.3x | n/m | -94.8% |
OWL | $14.4B | 77.6x | 10.4x | 4.8x | 5.1x | 7.9x | 8.3x | 19.4x | 9.2% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
BIP | Revenue | +112.0% | −44.9% | +8.3% |
| EPS | −46.5% | +88.2% | −29.9% | |
GS | Revenue | +20.6% | +2.7% | +1.8% |
| EPS | +42.8% | +4.7% | +5.3% | |
MS | Revenue | +16.6% | +5.5% | +5.6% |
| EPS | +30.4% | +5.9% | +8.1% | |
HASI | Revenue | +19.3% | +11.0% | +13.4% |
| EPS | +12.0% | +10.3% | +9.4% | |
BX | Revenue | +13.8% | +25.5% | +5.2% |
| EPS | +11.9% | +24.3% | +10.4% | |
KKR | Revenue | +43.7% | +8.6% | +25.4% |
| EPS | +28.7% | +15.2% | +14.4% | |
APO | Revenue | +26.9% | +16.3% | +14.0% |
| EPS | +10.4% | +22.4% | +15.5% | |
BAM | Revenue | +13.4% | +16.6% | +11.6% |
| EPS | +11.6% | +17.7% | +17.0% | |
ARES | Revenue | +17.8% | +19.4% | +9.7% |
| EPS | +17.1% | +24.2% | +18.1% | |
CG | Revenue | −1.7% | +36.3% | +9.0% |
| EPS | −10.1% | +41.6% | +15.4% | |
CRWV | Revenue | +150.7% | +106.7% | +61.6% |
| EPS | +208.9% | −49.2% | −141.7% | |
NBIS | Revenue | +508.0% | +260.2% | +88.0% |
| EPS | +65.5% | +69.1% | −94.1% | |
APLD | Revenue | +98.7% | +124.3% | +102.9% |
| EPS | −24.3% | +125.1% | −41.3% | |
OWL | Revenue | +6.2% | +10.5% | +15.5% |
| EPS | +7.9% | +11.5% | +14.6% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Every AI data center needs someone to write the check before the chips arrive. Over the past year, the businesses doing that writing have split into two camps with opposite stock-market outcomes. Investment banks Goldman Sachs and Morgan Stanley, plus infrastructure owner Brookfield Infrastructure Partners, have rallied 27% to 47%. Meanwhile the six largest private-equity and credit managers actually underwriting the debt and equity behind hyperscaler and "neocloud" data-center buildouts — Blackstone, KKR, Apollo Global Management, Brookfield Asset Management, Ares Management and Carlyle — have fallen 12% to 29%, even though every one of them told investors this summer that their fee income from managing money is growing 20% to 38% a year.
The lenders, in brief. Blackstone (BX) is the world's largest alternative-asset manager, with a data-center platform now valued at $185 billion including its QTS colocation business and a new $35 billion financing partnership with Broadcom for AI-chip deployment. KKR runs Helix, a $10 billion-plus vehicle backed by Nvidia and Vistra built to fund hyperscaler power and compute needs. Apollo Global Management (APO) co-anchored that same $35 billion Broadcom financing platform. Ares Management (ARES) operates Ada Infrastructure, seven data-center campuses totaling roughly 1 gigawatt of compute, with a dedicated digital-infrastructure fund closing later this year. Carlyle (CG) and Brookfield Asset Management (BAM) are diversified private-equity and infrastructure managers with smaller, less-detailed AI-financing disclosures. Brookfield Infrastructure Partners (BIP) directly owns roughly 50 data centers plus fiber and power assets. Goldman Sachs (GS) and Morgan Stanley (MS) are investment banks earning advisory and financing fees on the buildout. Hannon Armstrong (HASI) is a smaller climate-infrastructure lender.
Fundamentals versus the tape: a real divergence. For the six PE-style managers, the numbers do not match the stock reaction. Blackstone's fee-related earnings rose 22% and infrastructure assets under management 40% in its latest quarter; KKR's fee-related earnings per share rose 34% with $72 billion of committed capital still to start earning fees; Ares posted a record $36 billion fundraising quarter and 20% fee-earnings growth. None of that shows up in the share prices. Instead, the selloff traces to a separate scare: Apollo-managed business-development company MidCap Financial cut its dividend and marked down its portfolio roughly 3% on weak software loans, and fears that AI could obsolete private-equity-owned software companies hit the whole group this year. A separate scare in neocloud financing — CoreWeave's funding partner Blue Owl stumbling on a Pennsylvania data-center project — spread investor anxiety about AI-infrastructure lending broadly, dragging even firms with growing, well-disclosed data-center books. This is the pattern the desk should flag most: business fundamentals accelerating while the stock discounts credit stress that, so far, sits elsewhere in the portfolio.
Where the credit risk is real. It isn't imaginary. KKR's own management flagged that hyperscaler data-center loan spreads have recently widened and large deals are showing "indigestion," prompting more selectivity. Separately, tenant quality is starting to price differently: loans against data centers anchored by investment-grade hyperscaler tenants price tighter and need less equity per megawatt than those anchored by speculative-grade neoclouds. Ares, for its part, reports direct-lending non-accruals below 2% with underlying portfolio earnings still growing — evidence the deterioration is early and selective, not systemic, at least in disclosed vehicles.
The banks and the landlord look supported. Goldman and Morgan Stanley both posted record quarters built partly on AI-financing activity — Goldman's advisory revenue rose 17% on $1.2 trillion of announced deals, Morgan Stanley raised its 2026 AI data-center capital-spending forecast to $850 billion — and both trade at forward price-to-earnings multiples roughly flat to trailing (14-17x), meaning the market isn't pricing aggressive further upside, just current results. Brookfield Infrastructure's Data segment funds from operations rose 36%, but roughly $1.2 billion of its year-to-date cash came from selling stakes in a colocation IPO rather than new leases — a genuine but partly one-off contribution to the number behind its recent upgrade to a stronger uptrend.
The thin one. Hannon Armstrong's public disclosures mention data centers only in passing, tied to clean power rather than any specific committed lending; it was itself downgraded from a strong to a mild uptrend in the past month, suggesting its inclusion in any "data-center financing" grouping does more marketing work than balance-sheet work.
Technicals. As of August 3, the six PE-style managers all carry bearish trend readings (Ares strongly so, the other five mildly) despite 30-day bounces of 6-14% tied to rate-cut optimism rather than data-center news specifically, as seen when Apollo and KKR both surged more than 4% in a session on easing private-credit stress. Goldman, Morgan Stanley and Brookfield Infrastructure carry strong uptrends; Hannon Armstrong a milder one. Valuation gaps are stark: Apollo's price-to-earnings falls from 38x trailing to 15x forward, Ares from 61x to 24x, Carlyle from 32x to 13x — pricing in continued double-digit fee growth that, so far, is exactly what these firms have delivered.
The setup
Where it stands — Six AI data-center lenders trade near multi-year-low fee-growth-adjusted multiples while fee income and disclosed committed capital both expanded last quarter. Would confirm — Fee-related earnings growth stays above 20% and non-accruals in affiliated private-credit BDCs remain below 2% next quarter. Would invalidate — Non-accrual or PIK-income ratios rise materially in KKR, Ares or Blackstone credit vehicles tied to data-center or neocloud borrowers. Watch next — Q3 2026 earnings calls (October-November) for updated data-center AUM, spread, and non-accrual disclosures across BX, KKR, ARES, APO. Valuation — Forward P/E of 13-24x across the six managers versus 30-61x trailing, both well below their own recent-year highs.