

Barron's Biotech Takeout Basket Splits Wide: Alnylam Sinks 28% on Guidance Cut, Ascendis Turns a Profit
Prompt v1.1
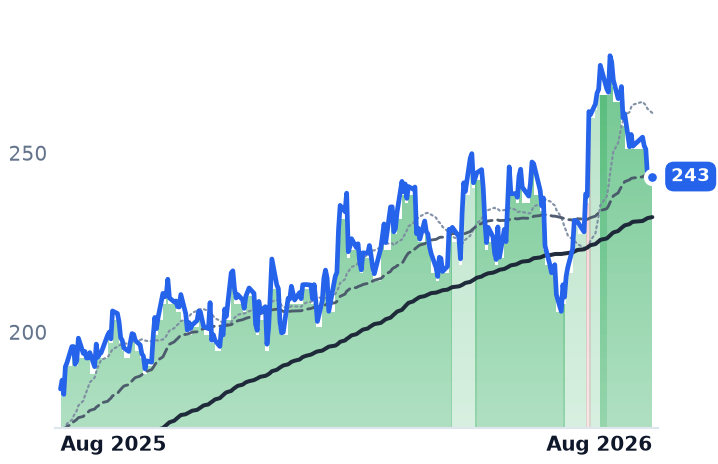
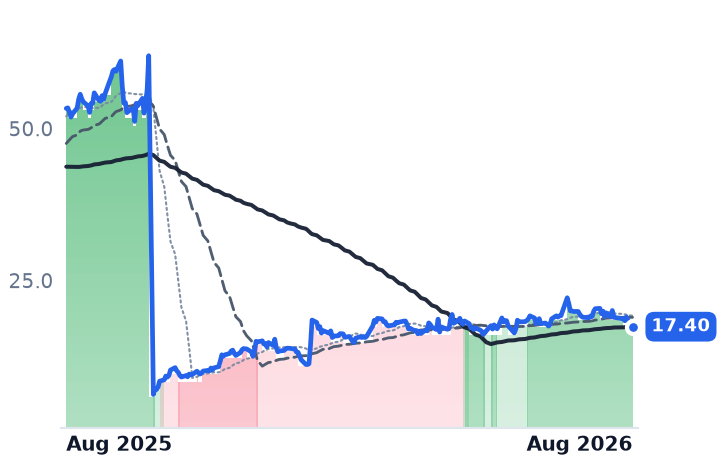
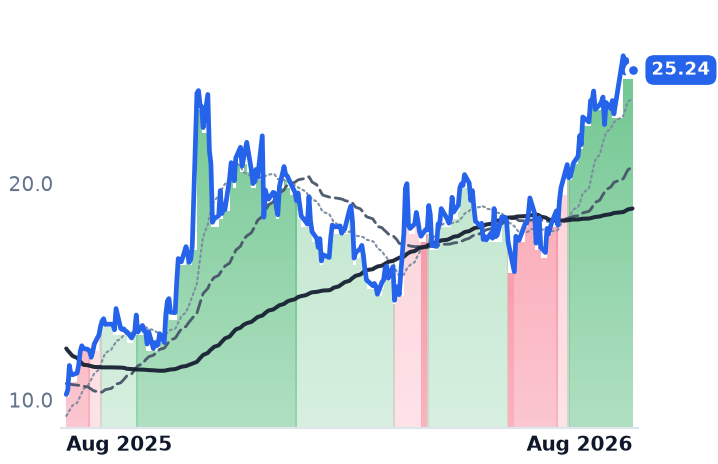
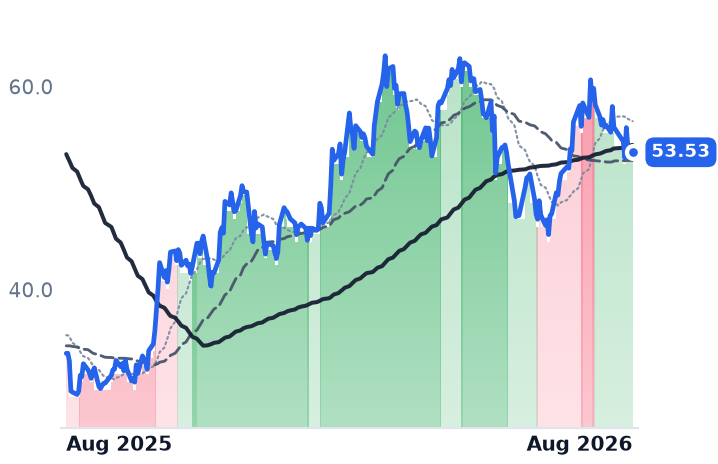
A watchlist of eight mid-size biotechs flagged as possible acquisition targets shows a 12-month average gain near 60% — but that number hides a 236-point spread between winners and losers, and last month's group-wide pullback was really one stock, Alnylam, cutting sales guidance on its flagship drug.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
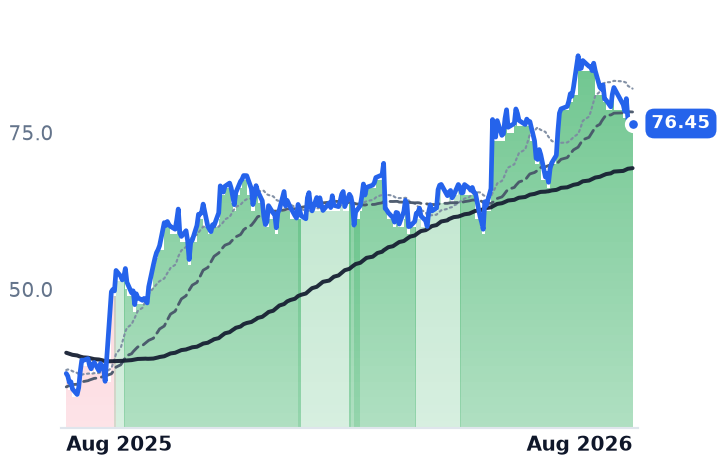
ASND | Ascendis Pharma A/S | Autoimmune & Inflammatory Diseases | 🟢 Cont. Bull | −9.1% | +32.2% |
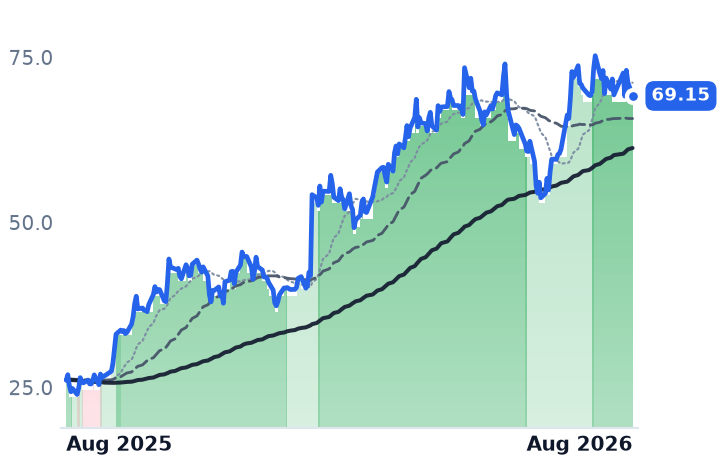
MLTX | MoonLake Immunotherapeutics | Monoclonal Antibodies & Immunotherapies | 🟢 Cont. Bull | −7.8% | −67.4% |
DYN | Dyne Therapeutics | Other | 🟢 Cont. Bull | +10.5% | +146.2% |
PCVX | Vaxcyte | Vaccines & Infectious Disease | ⚠️ Emerging Bear | −6.0% | +58.7% |
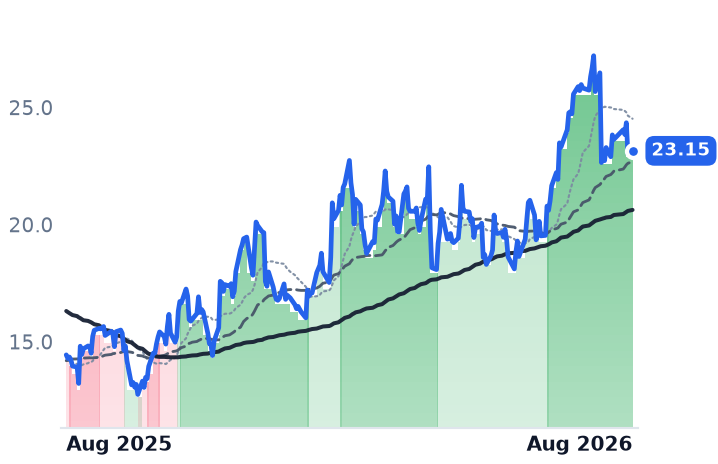
CYTK | Cytokinetics, Incorporated | Other | 🟢 Cont. Bull | −10.7% | +109.0% |
CGON | CG Oncology | Other | 🟢 Cont. Bull | −0.2% | +165.0% |
DNLI | Denali Therapeutics | Other | 🟢 Cont. Bull | −10.1% | +60.3% |
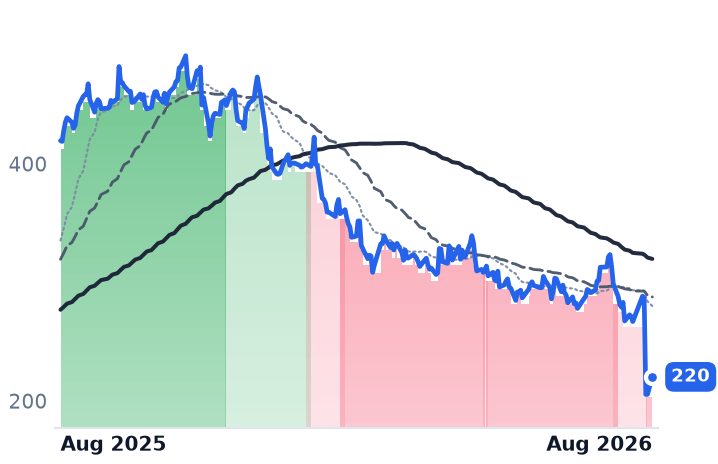
ALNY | Alnylam Pharmaceuticals | Gene & RNA Therapeutics | 🔴 Cont. Bear | −29.6% | −47.5% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ASND | $14.0B | 16.4x | 16.2x | 11.7x | 10.4x | 12.9x | 11.5x | 152.8x | 2.7% |
MLTX | $1.6B | n/m | — | n/m | — | — | — | n/m | -14.5% |
DYN | $3.0B | n/m | — | n/m | — | — | — | n/m | -16.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
PCVX | $8.4B | n/m | — | n/m | 335.4x | — | — | n/m | -14.3% |
CYTK | $8.0B | n/m | — | 113.4x | 53.7x | 133.4x | 63.2x | n/m | -7.2% |
CGON | $6.3B | n/m | — | — | 568.3x | — | — | n/m | -2.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DNLI | $3.7B | n/m | — | n/m | 104.4x | — | — | n/m | -11.5% |
ALNY | $30.4B | 37.3x | 35.0x | 6.3x | 5.6x | 7.9x | 7.0x | 26.0x | 1.8% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
ASND | Revenue | +90.9% | +46.5% | +27.1% |
| EPS | −516.5% | −35.2% | +58.5% | |
MLTX | Revenue | — | — | +499.2% |
| EPS | +6.4% | −5.3% | −19.5% | |
DYN | Revenue | +43.8% | +5202.8% | +423.5% |
| EPS | +3.5% | −7.7% | −24.6% | |
PCVX | Revenue | — | +248.6% | +103.3% |
| EPS | +51.9% | −19.8% | −5.5% | |
CYTK | Revenue | +94.8% | +182.8% | +110.5% |
| EPS | −6.8% | −26.1% | −52.9% | |
CGON | Revenue | +292.5% | +669.5% | +432.7% |
| EPS | +26.5% | +2.4% | −97.0% | |
DNLI | Revenue | +1299.4% | +204.0% | +150.9% |
| EPS | −18.1% | +0.8% | −24.6% | |
ALNY | Revenue | +45.8% | +26.4% | +18.9% |
| EPS | +163.9% | +48.5% | +23.6% |
Forward fiscal years only. Blank means no analyst coverage for that year.
A basket of eight mid-size biotech stocks that Barron's and fund manager David Giroux flagged in June as likely large-pharma acquisition targets has gained an average of 58% over the past year. That average is doing a lot of work to hide what actually happened: one stock, CG Oncology, tripled; another, MoonLake, lost two-thirds of its value; and the group's apparent one-month "pullback" of 7% was overwhelmingly the work of a single five-session, 28% crash in Alnylam Pharmaceuticals, which sells Amvuttra, a gene-silencing injection for a heart-damaging protein disorder called ATTR amyloidosis. This is not a quietly compounding sector story. It's a barbell of one real commercial setback and several speculative re-ratings, sitting on top of a genuine pickup in industry-wide dealmaking.
What actually moved, and why. Alnylam's Amvuttra crossed $1 billion in quarterly sales for the first time in the same report that triggered the stock's collapse: the company cut its full-year sales guidance by $200 million at both ends of the range, to $4.2–$4.5 billion, after second-quarter revenue came in about 4% below Wall Street's estimate as early-launch demand normalized (Endpoints News). The stock had already been sliding on a separate readout — a disappointing study of a related drug, eplontersen, that raised questions about how RNA-silencing drugs like Amvuttra perform in patients switching from other treatments (Endpoints News). The business is still growing; the multiple compressing around it — trailing price-to-sales fell to 9.3x, cheaper than before the crash — makes Alnylam the one name in this group where the tape and the fundamentals now disagree, a genuine dislocation rather than a confirmation of bad news.
Ascendis Pharma, which sells the growth-hormone therapy Skytrofa and the hormone-replacement drug Yorvipath, is the opposite case: price and business are moving together. It posted its first-ever quarterly operating profit in the first quarter of 2026 — €25 million, a 10% margin — on revenue up 145% year over year, and management is targeting €5 billion in annual product sales by 2030 (Ascendis investor release). Cytokinetics, whose heart drug aficamten launched in January to compete with Bristol Myers Squibb's Camzyos, had reached 680 patients and 275 prescribers by mid-year (Investing.com) — real commercial traction, though the stock's ~109x trailing sales multiple prices in years of the drug's estimated $1.5–2 billion peak-sales potential.
The rest of the group is harder to defend on fundamentals alone. Vaxcyte, developing a pneumococcal vaccine called VAX-31, has no revenue and won't have pivotal trial data until the fourth quarter (StockTitan); its $8.4 billion valuation is a bet on that single readout. CG Oncology, whose bladder-cancer therapy cretostimogene is still awaiting FDA filing, trades near 1,238 times trailing sales. Dyne Therapeutics just raised $405 million in an upsized stock sale to fund its RNA-based muscular dystrophy programs through mid-2028 (Globe and Mail), and Denali Therapeutics has roughly 12 months of cash left and a $400 million backup share-sale facility ahead of Parkinson's and dementia data due later this year (Seeking Alpha). MoonLake, whose skin-disease antibody sonelokimab failed one of two pivotal trials last September, is rebuilding around a narrower FDA filing path but still posted a widening $70 million quarterly loss with rising share dilution.
The acquisition case is real — for the sector, not yet for these names. Global biopharma dealmaking hit $106 billion across 201 deals through mid-2026, on pace for the strongest year since 2019, with premiums averaging 60–120% as large drugmakers race to replace more than $200 billion of revenue facing patent expiration by 2030 (CNBC; CNBC). But none of these eight companies has actually been acquired in the past four quarters — the takeout premium in the pre-revenue names' valuations is a forward bet, not a confirmed pattern.
The setup
Where it stands — Alnylam's Amvuttra franchise keeps growing while its stock trades below its pre-crash multiple; six of eight peers carry valuations that assume commercial success not yet reported. Would confirm — A completed acquisition of any of the eight names at a 60%+ premium, or Amvuttra quarterly revenue reaccelerating past $1.05 billion next quarter. Would invalidate — Amvuttra sales guidance is cut again, or Vaxcyte's Q4 2026 VAX-31 pivotal data misses its efficacy target. Watch next — Vaxcyte's OPUS-1 pivotal readout, guided for the fourth quarter of 2026. Valuation — Alnylam trades at 9.3x trailing sales versus its own pre-crash multiple; Cytokinetics and CG Oncology trade at 109x and 1,238x trailing sales, both near their own multi-year highs.