

Gold Miners' Slump Narrows to Three Names as Cost Inflation Meets One-Off Setbacks
Prompt v1.1
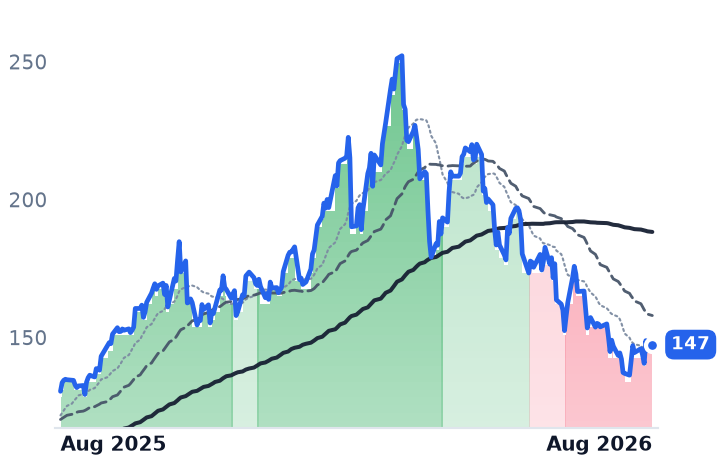
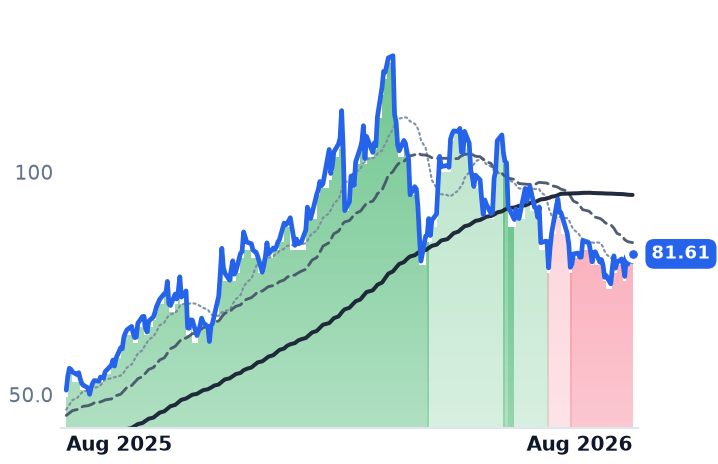
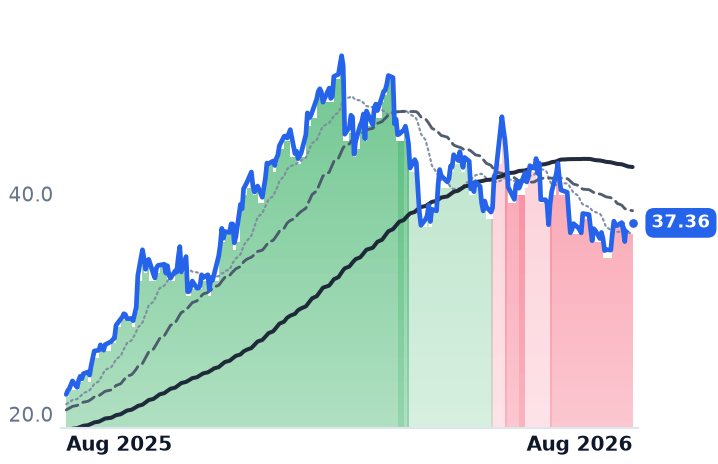
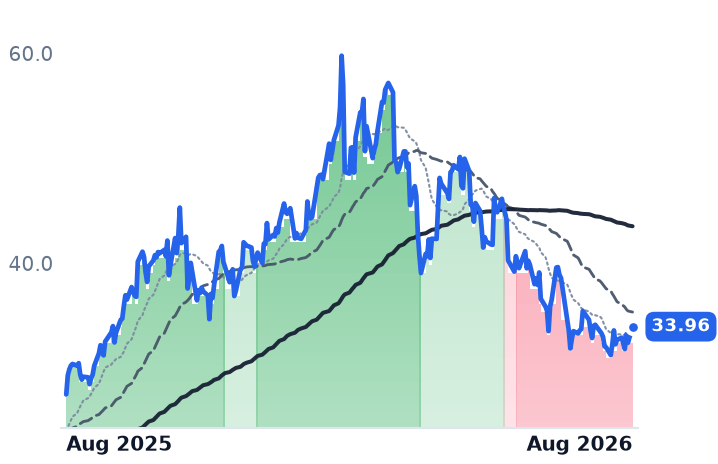
A feared two-segment gold de-rating didn't materialize broadly: seven of ten major gold producers and royalty firms already rebounded to neutral trading by late July, leaving only Agnico Eagle, AngloGold Ashanti and Barrick still down — each for its own reason, not because gold fell.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
AEM | Agnico Eagle Mines | Intermediate Producers | ⚠️ Emerging Bear | −4.9% | +13.0% |
AU | AngloGold Ashanti | Major Producers | ⚠️ Emerging Bear | −2.9% | +60.0% |
B | Barrick Mining | Major Producers | 🔴 Cont. Bear | −2.0% | +71.6% |
GFI | Gold Fields | Major Producers | ⚠️ Emerging Bear | −1.9% | +23.5% |
KGC | Kinross Gold | Major Producers | ⚠️ Emerging Bear | −5.2% | +36.1% |
NEM | Newmont | Major Producers | ⚠️ Emerging Bear | −2.9% | +47.0% |
FNV | Franco-Nevada | Precious Metals Royalty & Streaming | ⚠️ Emerging Bear | +0.9% | +29.0% |
OR | OR Royalties | Precious Metals Royalty & Streaming | ⚠️ Emerging Bear | −1.2% | +5.5% |
RGLD | Royal Gold | Precious Metals Royalty & Streaming | ⚠️ Emerging Bear | +0.1% | +30.0% |
WPM | Wheaton Precious Metals | Precious Metals Royalty & Streaming | ⚠️ Emerging Bear | −2.9% | +16.9% |
GLD | SPDR Gold Shares | Asset Management | ⚠️ Emerging Bear | −2.7% | +19.6% |
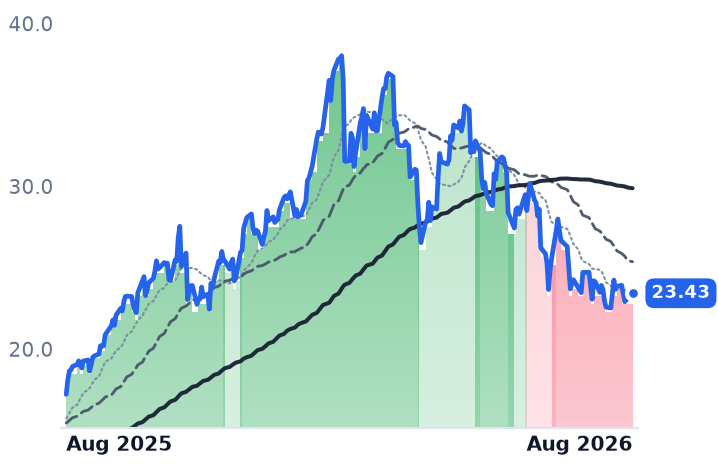
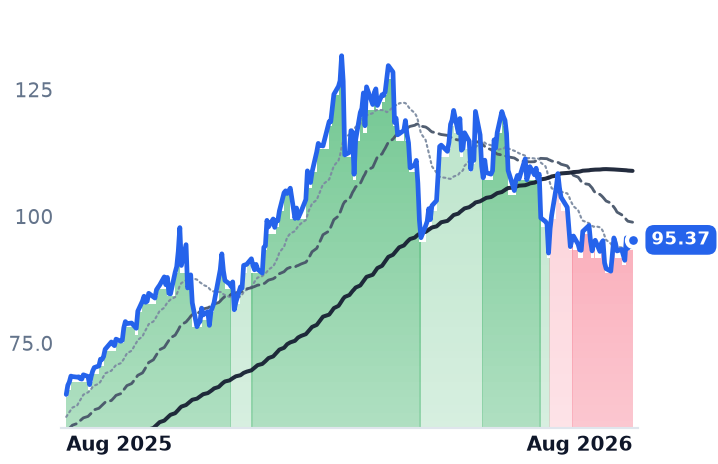
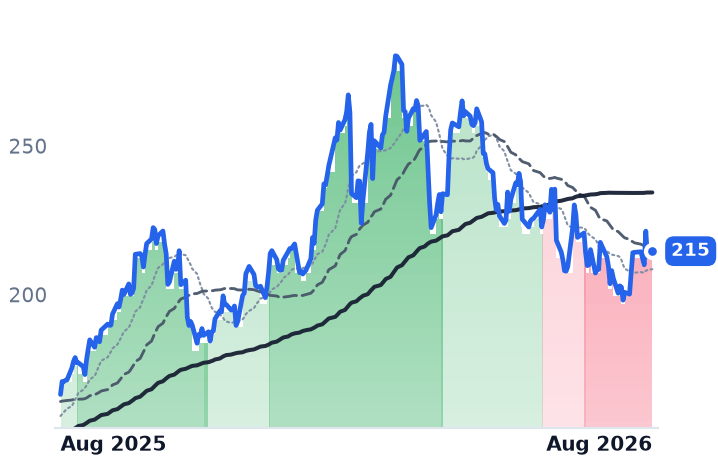
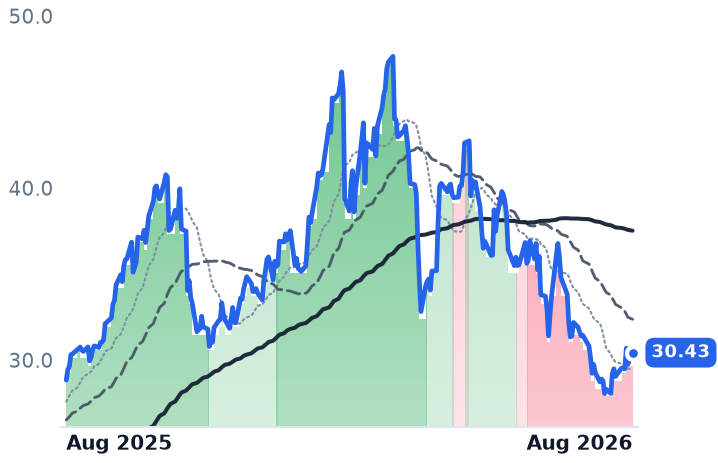
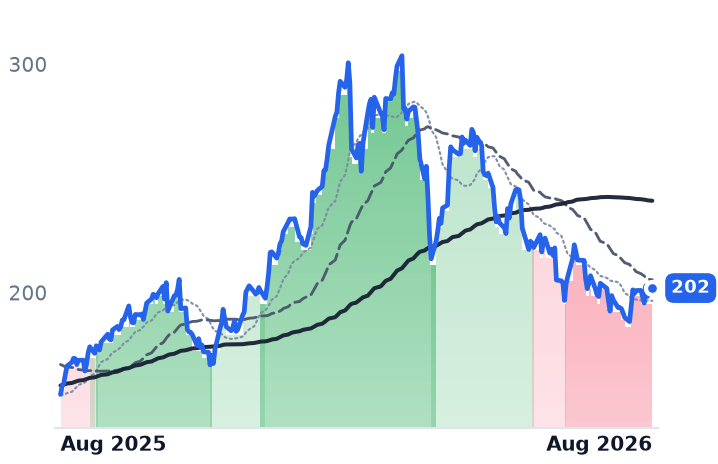
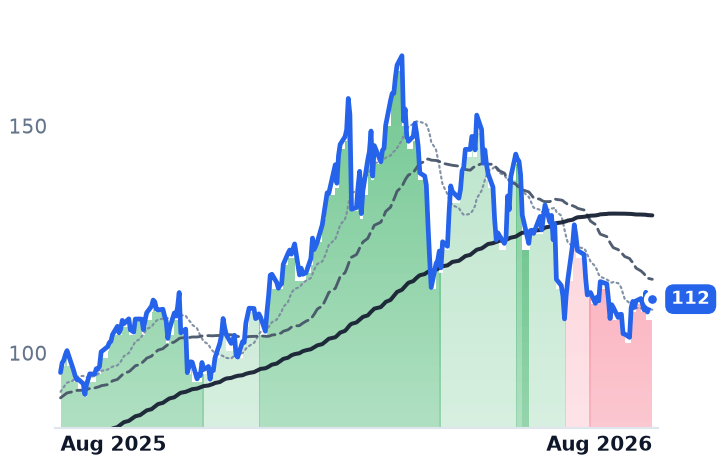
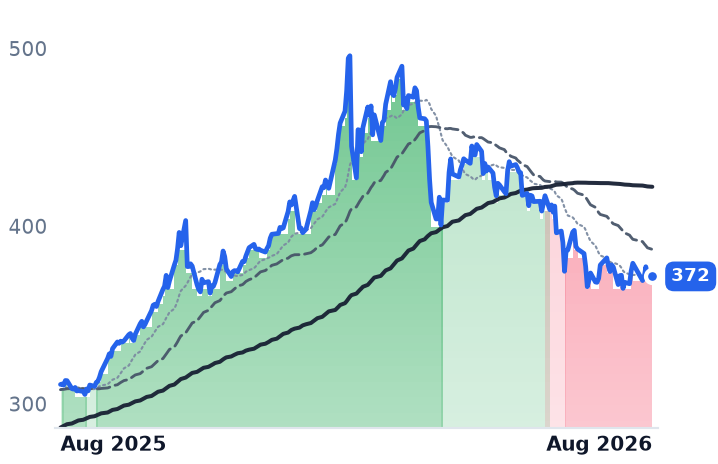
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AEM | $95.7B | 16.2x | 16.1x | 6.6x | 6.3x | 10.6x | 10.1x | 8.9x | 4.7% |
AU | $47.6B | 12.5x | 10.6x | 4.0x | 3.7x | 7.5x | 7.0x | 5.8x | 8.9% |
B | $68.8B | 10.6x | 11.8x | 3.3x | 3.3x | 5.9x | 5.8x | 5.2x | 8.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
GFI | $31.8B | 7.1x | 7.6x | 2.8x | 2.7x | 4.9x | 4.7x | 4.4x | 14.2% |
KGC | $26.4B | 8.5x | 8.8x | 3.1x | 3.1x | 5.9x | 5.7x | 4.4x | 11.7% |
NEM | $124.2B | 14.8x | 12.6x | 4.9x | 4.7x | 8.5x | 8.1x | 7.4x | 7.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FNV | $45.3B | 30.7x | 28.1x | 19.6x | 18.0x | 25.3x | 23.3x | 20.0x | 2.0% |
OR | $6.3B | 21.9x | 18.6x | 16.0x | 11.5x | 18.9x | 13.6x | 15.3x | -1.7% |
RGLD | $19.1B | 24.5x | 21.5x | 12.3x | 10.3x | 18.5x | 15.5x | 16.0x | 0.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
WPM | $58.8B | 28.7x | 27.5x | 18.5x | 16.0x | 24.0x | 20.8x | 21.8x | -5.0% |
GLD | $155.3B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
AEM | Revenue | +28.3% | +3.6% | −1.8% |
| EPS | +42.8% | +3.6% | +0.8% | |
AU | Revenue | +27.6% | +5.5% | +5.3% |
| EPS | +53.2% | +3.3% | +13.3% | |
B | Revenue | +28.6% | +13.2% | +5.1% |
| EPS | +50.3% | +13.0% | +15.0% | |
GFI | Revenue | +37.7% | +2.9% | +4.0% |
| EPS | +40.7% | +9.3% | +5.0% | |
KGC | Revenue | +20.8% | +4.3% | +5.3% |
| EPS | +44.6% | +9.4% | +12.4% | |
NEM | Revenue | +20.8% | +7.6% | +3.7% |
| EPS | +42.3% | +11.7% | +13.0% | |
FNV | Revenue | +44.1% | +14.5% | +2.8% |
| EPS | +54.5% | +11.6% | +12.1% | |
OR | Revenue | +42.3% | +16.4% | +10.2% |
| EPS | +47.6% | +3.6% | +23.4% | |
RGLD | Revenue | +76.1% | +16.3% | +1.6% |
| EPS | +29.8% | +23.5% | +4.5% | |
WPM | Revenue | +65.1% | +10.4% | +9.3% |
| EPS | +61.4% | +6.6% | +11.6% |
Forward fiscal years only. Blank means no analyst coverage for that year.
What actually happened
A month ago it looked like the entire gold-mining complex was turning over together — both the big producers that dig ore out of the ground and the royalty firms that finance mines in exchange for a cut of output showed the same technical downtrend. That reading doesn't survive a closer look. By July 28, seven of the ten largest gold-related stocks had already snapped back to neutral trading, and the metal itself barely moved over the same 30 days. What's left is a narrower, more useful story: three producers are still down, and each has its own explanation.
The ten companies
The group splits into miners and financiers. Agnico Eagle Mines (AEM), a Canadian gold miner with operations from Quebec to Nunavut; AngloGold Ashanti (AU), a Johannesburg-based producer with mines across Africa, the Americas and Australia; and Barrick Mining (B), a global gold and copper miner headquartered in Toronto, remain in a sustained downtrend. Gold Fields (GFI), a South African-based global gold producer; Kinross Gold (KGC), a Canadian miner with operations in the Americas and West Africa; and Newmont (NEM), the world's largest gold producer by market value, have all recovered to neutral. So have all four royalty and streaming firms — Franco-Nevada (FNV), which funds mine construction for a share of future output rather than operating mines itself; Osisko Gold Royalties (OR), a smaller Canadian royalty company; Royal Gold (RGLD), a US-based royalty and streaming firm; and Wheaton Precious Metals (WPM), which buys discounted future gold and silver production from operators.
Three producers, three separate problems
Agnico Eagle's slide traces to a specific incident: a July 1 rock-mass movement forced the company to suspend part of its Barnat pit at the Canadian Malartic complex, and it cut 2026-2028 production guidance by up to 150,000 ounces a year while raising costs at that mine to roughly $1,260 an ounce; the stock fell as much as 5.2% on the news. AngloGold Ashanti missed second-quarter estimates — earnings of $1.96 a share versus $2.04 expected, revenue of $3.1 billion versus $3.3 billion — and shares fell as much as 10.6% intraday, with Scotiabank, Citigroup and JPMorgan all trimming price targets despite record cash generation. Barrick had no single incident but absorbed a string of downgrades after raising 2026 all-in sustaining cost (AISC) guidance to $1,760-1,950 an ounce from $1,637, prompting Citi and JPMorgan price-target cuts.
Cost inflation itself is not confined to these three. Newmont guided 2026 AISC to $1,680 an ounce, up from $1,358, and Agnico Eagle guided costs higher on labor, electricity and royalty inflation even before its pit suspension. So the operating-leverage pressure the hypothesis flagged is real and sector-wide — it just hasn't been enough on its own to keep a stock's trend broken. It took an added, company-specific catalyst to do that.
Gold itself didn't move
The metal explains none of this month's divergence. A gold-tracking ETF proxy closed at $370.60 on July 1 and $371.54 on July 31 — essentially flat. The real correction happened earlier, from a May 1 peak near $423 down to $370.60 by July 1, a 12.4% drop that UBS attributes to markets "rediscovering the concept of opportunity cost" as real yields and the dollar firmed; consensus Q3/Q4 price forecasts were trimmed accordingly. Demand data don't support a bearish read either: central banks bought 289 tonnes in the second quarter, up 62% year over year, more than offsetting modest 45-tonne ETF outflows.
Valuation: cheap producers, structurally rich streamers
On forward earnings, the three lagging producers aren't obviously overpriced: Barrick trades near 10.0x forward earnings and Newmont near 10.6x, both close to a roughly 9.5x gold-mining industry average, while Agnico Eagle carries a 21% premium at about 11.3x — arguably still cheap given its 16% one-year gain. Royalty firms trade richer by design: the group structurally commands 1.5-2.0x net asset value versus miners' 0.7-0.9x, reflecting fixed-margin economics rather than fresh re-rating, though Franco-Nevada's roughly 45x P/E rests on assumptions — sustained gold strength and Cobre Panamá clarity — that a renewed gold leg down could still test. Fine-grained company profitability data for nine of these ten names came from public filings and sell-side notes rather than a single database pull that exceeded its output limit; the figures are corroborated across multiple sources.
The tape
Seven of ten names flipped from a sharp downtrend back to neutral trading by July 28 and held there through month-end; AEM, AU and B alone remained pinned in the downtrend through July 31, consistent with the idiosyncratic, not sector-wide, story above.
The setup
Where it stands — Only three of ten gold stocks remain in a sustained downtrend, each tied to a company-specific setback rather than a falling gold price. Would confirm — A fourth or fifth name (e.g., Newmont, Gold Fields) re-enters a sustained downtrend without its own guidance cut or earnings miss. Would invalidate — Agnico Eagle, AngloGold or Barrick recover to neutral trading within the next month without a new operational or earnings catalyst. Watch next — Barrick's and Newmont's next quarterly results, due mid-to-late October 2026, for confirmation of AISC guidance and margin trends. Valuation — Barrick ~10.0x and Newmont ~10.6x forward earnings, near the ~9.5x gold-mining industry average; Franco-Nevada ~45x, near its own structural premium range.