

Nuclear/SMR Complex Rolls Over Together — But Fuel-Cycle Names Aren't All Equal
Prompt v1.0
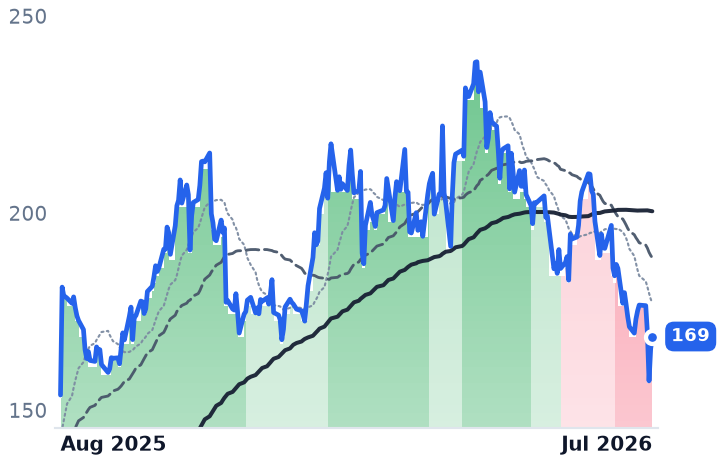
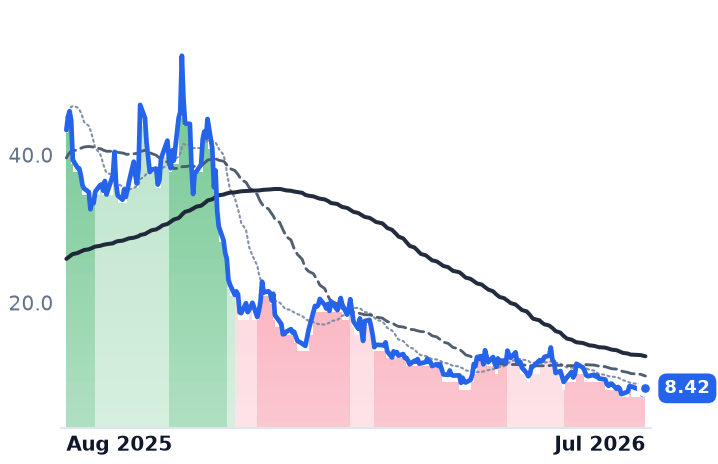
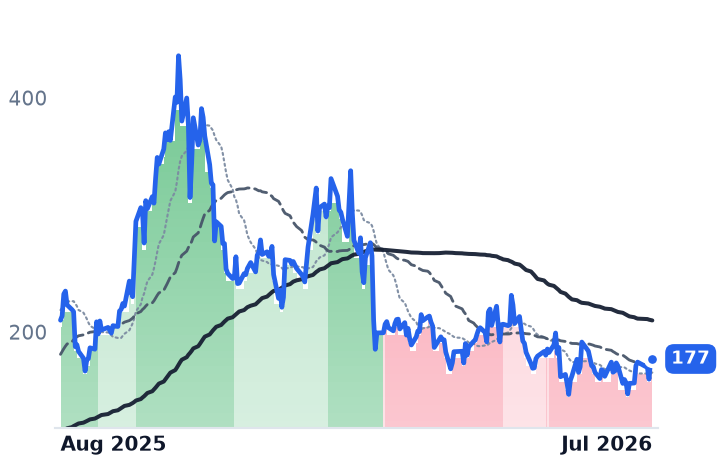
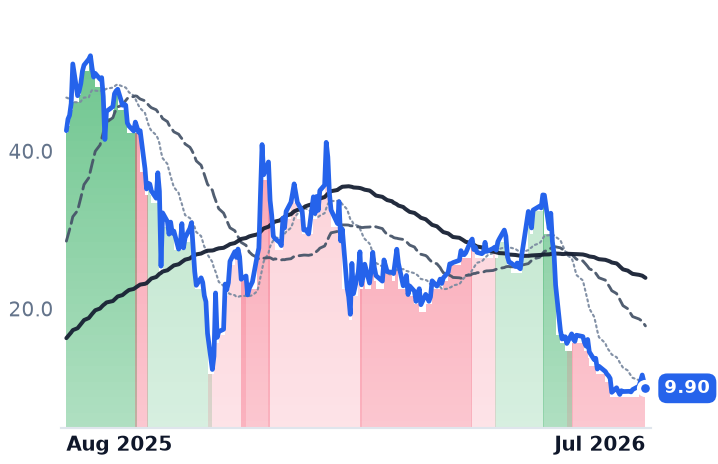
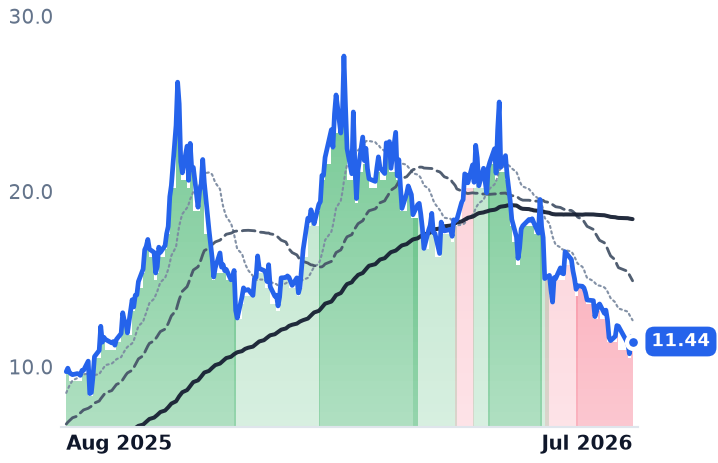
BWXT, CCJ, SMR, OKLO, LEU and UUUU flipped from bull to strongly bearish bands within a tight four-week window in June-July 2026, confirming a real thesis-level de-rating in the AI-nuclear trade rather than isolated stock news — but FRVO (geothermal, not nuclear) and FRMI's steep declines trace to unrelated, idiosyncratic catalysts, and BWXT's order book is actually growing even as its stock craters.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
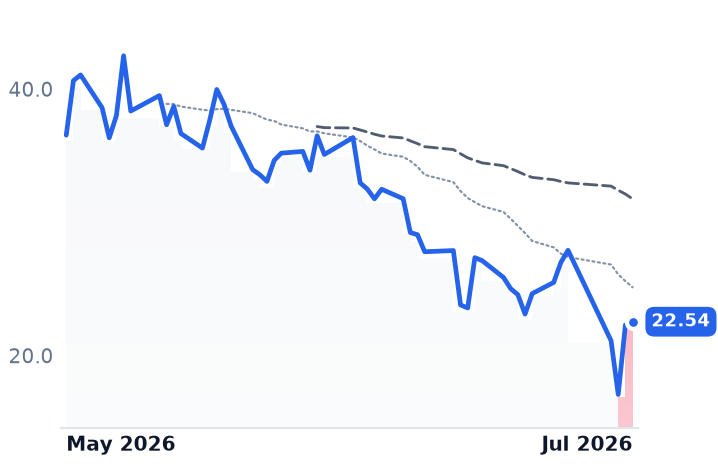
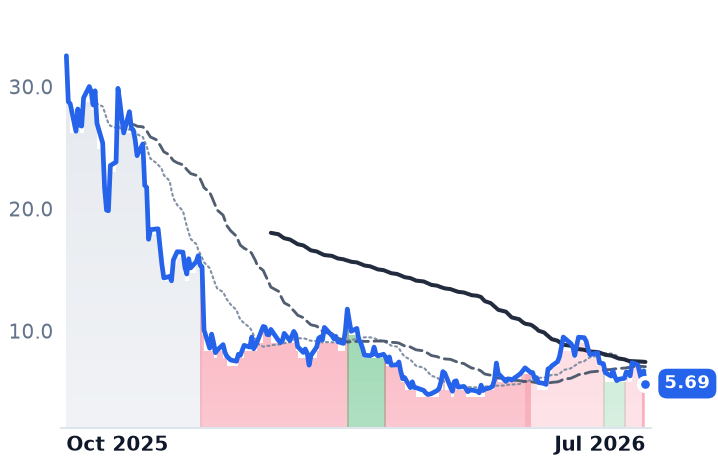
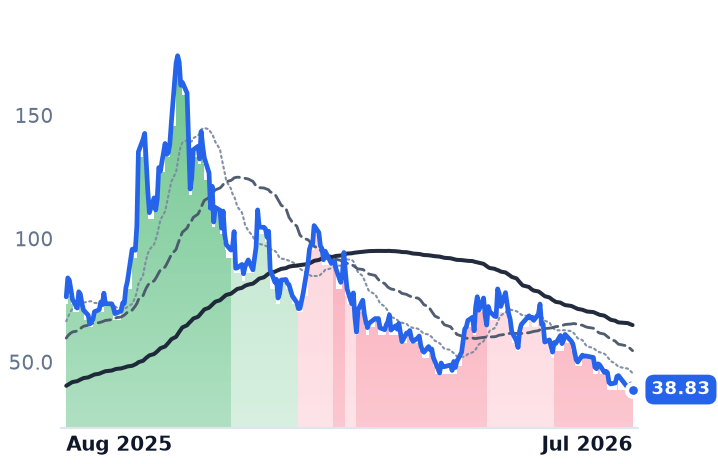
FRVO | Fervo Energy | Geothermal Specialists | 🔴 Cont. Bear | −19.2% | −38.3% |
FRMI | Fermi | Data Center Operators | 🔴 Cont. Bear | −30.7% | −82.5% |
OKLO | Oklo | Advanced Nuclear | 🔴 Cont. Bear | −25.1% | −49.2% |
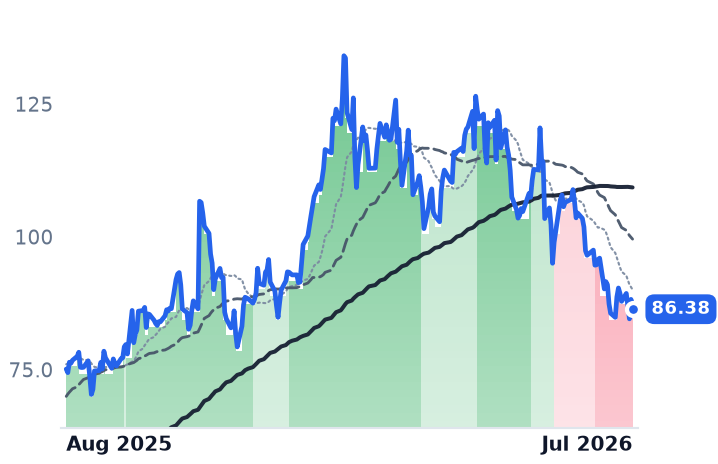
CCJ | Cameco | Uranium | ⚠️ Emerging Bear | −11.4% | +15.0% |
BWXT | BWX Technologies | Aerospace Components & Propulsion | ⚠️ Emerging Bear | −14.3% | +9.6% |
SMR | NuScale Power | Advanced Power Systems | 🔴 Cont. Bear | −12.4% | −80.6% |
LEU | Centrus Energy | Uranium | 🔴 Cont. Bear | +1.5% | −15.8% |
NNNN | Anbio Biotechnology Class A Ordinary Shares | Diagnostics & Blood Management | 🔴 Cont. Bear | −17.8% | −76.8% |
UUUU | Energy Fuels | Uranium | ⚠️ Emerging Bear | −16.9% | +17.7% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FRVO | $4.1B | n/m | — | — | 759.0x | — | — | n/m | -10.7% |
FRMI | $3.8B | n/m | — | n/m | 208.4x | — | — | n/m | -31.0% |
OKLO | $6.6B | n/m | — | — | — | — | — | n/m | -4.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CCJ | $37.1B | 148.5x | 57.8x | 15.2x | 10.7x | 55.2x | 38.7x | 61.2x | 1.0% |
BWXT | $12.4B | 34.8x | 28.4x | 3.5x | 3.2x | 15.9x | 14.7x | 24.9x | 2.6% |
SMR | $3.0B | n/m | — | 284.6x | 160.7x | — | 762.7x | n/m | -25.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
LEU | $2.6B | 55.1x | 54.3x | 5.5x | 5.6x | 23.7x | 23.9x | 26.5x | -8.5% |
NNNN | $1.2B | 164.5x | — | 121.3x | — | 139.4x | — | 181.4x | 0.1% |
UUUU | $2.8B | n/m | — | 26.8x | 21.3x | 62.0x | 49.3x | n/m | -3.9% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
FRVO | Revenue | +3857.3% | +1212.9% | +179.6% |
| EPS | −91.0% | −26.3% | −19.6% | |
FRMI | Revenue | +14.5% | +2797.8% | +327.6% |
| EPS | +326.2% | −116.4% | +1983.0% | |
OKLO | Revenue | — | +247.8% | +498.2% |
| EPS | +64.1% | +8.1% | +10.3% | |
CCJ | Revenue | +1.4% | +12.3% | +8.3% |
| EPS | +2.6% | +71.9% | +24.2% | |
BWXT | Revenue | +20.7% | +9.1% | +8.7% |
| EPS | +24.1% | +10.6% | +13.3% | |
SMR | Revenue | −54.8% | +517.4% | +185.1% |
| EPS | −76.8% | +19.4% | −24.8% | |
LEU | Revenue | +5.2% | −0.8% | −10.9% |
| EPS | −43.2% | +13.2% | −23.3% | |
UUUU | Revenue | +128.1% | +88.3% | +62.7% |
| EPS | −37.3% | −160.5% | +170.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
A synchronized rollover, not scattered noise
Band-transition data shows six adjacent nuclear-complex names — LEU, SMR, OKLO, CCJ, BWXT and UUUU — rolled from bullish trend bands into strongly bearish within roughly a four-week window between late May and early July 2026 (LEU from 5/29, SMR from 6/10, CCJ confirmed 7/7, BWXT confirmed 7/8, UUUU from 6/25). That clustering is the strongest piece of evidence here: it looks like a thesis-level repricing, not six unrelated stock stories. The catalyst dates to the mid-to-late July "AI hype rotation," when Oklo, X-Energy, NuScale, Nano Nuclear and Uranium Energy Corp each fell 8-9% in a single session as investors began demanding proof of licensing, financing and construction rather than rewarding announcement-stage hype.
The pre-revenue tail has real fundamentals behind the sell-off
The pullback isn't purely sentiment. Oklo remains pre-revenue, was down 27.9% over the trailing month even after a $200M federal reactor-acceleration award, has built its $2.5B cash pile via a $1.18B dilutive ATM raise and just filed a fresh $1B equity shelf, and its Aurora reactor still lacks NRC design certification even as ancillary isotope-licensing milestones clear. Uranium spot has also cooled, pulling back to ~$71.45/lb from a seven-month high of $79/lb in mid-June, while the term price held near $80/lb — a real but moderate correction, not a collapse in physical contracting.
The fuel-cycle leg is not one story
This is where the "dragged down by speculative peers" framing breaks. BWXT's backlog reached ~$8.65B, up 77% year-over-year, supporting the case that its equity de-rating is multiple compression, not fundamentals. Cameco, by contrast, missed Q2 EPS by roughly 50% on weaker Westinghouse equity income and trimmed 2026 delivery guidance — a direct hit to its large-reactor bull case. Centrus, meanwhile, heads into its August 5 print with consensus estimates cut sharply.
Two names don't belong in this story
FRVO is a geothermal developer, not nuclear, and its single-session flip to strongly bearish on July 29 — weeks after the main cluster — traces to widening losses and a flagged cash-runway concern, not sector contagion. FRMI's sharpest leg down followed its own $375M convertible note pricing and a director resignation, before a Mizuho price-target cut and a turbine-delivery bounce tied to its hybrid gas-nuclear Project Matador campus — a story with little to do with uranium fundamentals.