

Physician-Staffing Cohort's Bull Label Is Real — the Fundamentals Aren't Uniform
Hypothesis Opus 5 · Research Sonnet 5 · Writing Sonnet 5 · Prompt v1.0
All four names in the watchlist's Physician Services & Staffing bucket (AGL, AMN, ASTH, MD) genuinely share a strongly bullish band that predates Agilon's own upgrade, but the underlying fundamentals diverge sharply — AGL's margin turn is real yet richly re-rated and under fresh short-seller/analyst pressure, AMN's blowout quarter was a one-off strike windfall with core locums revenue still falling, and MD remains the cheapest, steadiest leg heading into next week's earnings.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
AGL | Agilon Health | Physician Services & Staffing | 🌱 Emerging Bull | −19.5% | +92.0% |
AMN | AMN Healthcare Services | Physician Services & Staffing | 🌱 Emerging Bull | +7.2% | +79.4% |
ASTH | Astrana Health | Physician Services & Staffing | 🌱 Emerging Bull | −18.9% | +55.8% |
MD | Pediatrix Medical | Physician Services & Staffing | 🟢 Cont. Bull | +8.3% | +111.0% |
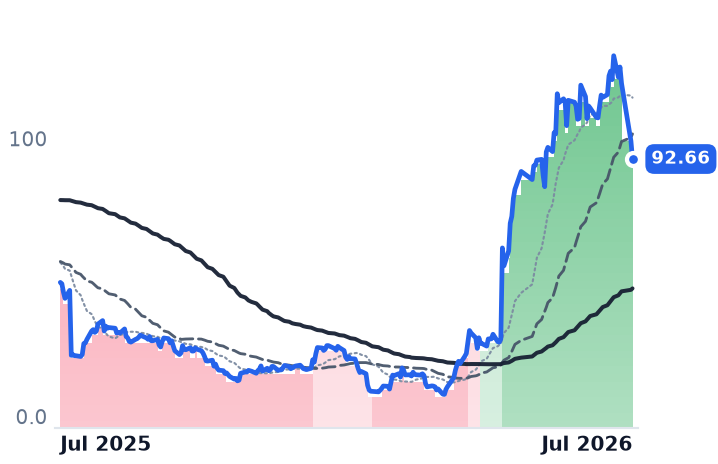
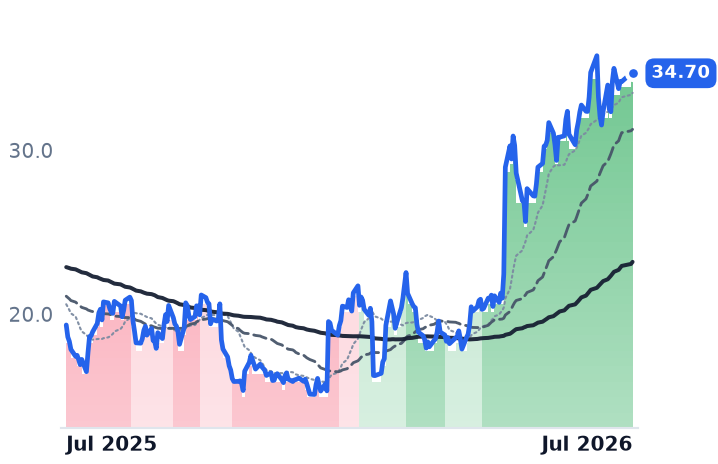
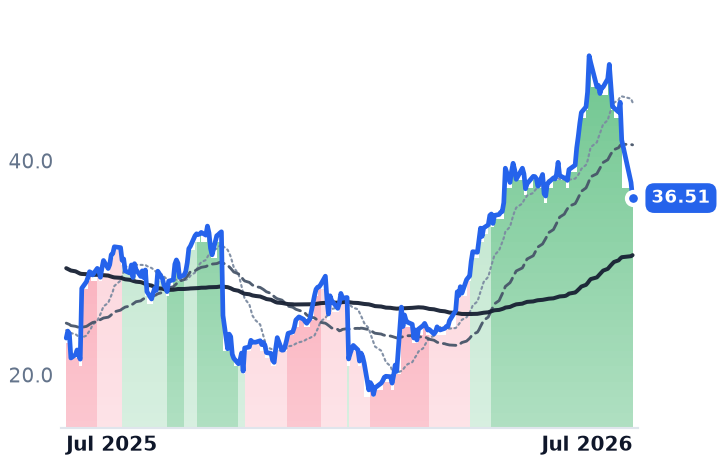
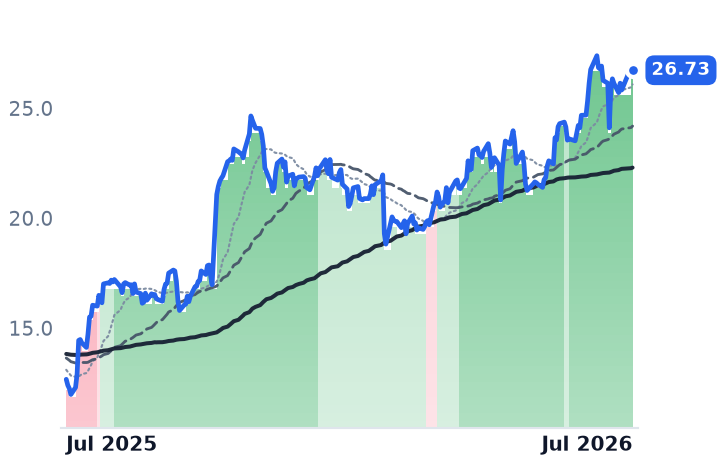
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AGL | $1.5B | n/m | — | 0.3x | 0.3x | — | — | n/m | -5.0% |
AMN | $1.3B | n/m | 12.7x | 0.4x | 0.4x | 1.4x | 1.5x | 7.5x | 54.2% |
ASTH | $1.8B | 57.6x | 28.0x | 0.5x | 0.4x | 5.4x | 4.7x | 14.4x | 8.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MD | $2.2B | 12.9x | 11.6x | 1.1x | 1.1x | 4.4x | 4.3x | 9.3x | 10.9% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
AGL | Revenue | −1.8% | +6.3% | +11.6% |
| EPS | −84.4% | −69.1% | −294.6% | |
AMN | Revenue | +20.2% | −19.9% | +4.5% |
| EPS | +88.5% | −59.2% | +18.2% | |
ASTH | Revenue | +26.7% | +9.4% | +7.0% |
| EPS | +158.1% | +47.6% | +46.0% | |
MD | Revenue | +1.9% | +2.4% | +4.4% |
| EPS | +9.5% | +3.5% | −3.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The band move is cohort-wide, not an AGL artifact
Daily trend-band history shows all four tickers — AGL, AMN, ASTH and MD — sat in a strongly bearish band as recently as July 2025 and are all in strongly bullish as of the latest read. Notably, AMN, ASTH and MD had already confirmed strongly bullish status by late April 2026, weeks before Agilon's own band upgraded from mildly bullish — meaning the cohort label isn't simply a single stock dragging an average. One-year returns underline the same point: MD is actually up more than Agilon (+112.0% vs +99.3%), with AMN +76.4% and ASTH +60.6%. It's only on the six-month window that Agilon's move separates from the pack, up roughly 383% versus 30-73% for the other three.
Agilon: real margin improvement, expensive re-rating
Agilon's Q1 2026 medical margin rose to $149M from $128M a year earlier, and full-year guidance was raised to roughly $5.7B revenue and $375M medical margin — though adjusted EBITDA guidance of just ~$25M shows how thin the underlying economics remain even after deliberate exits of unprofitable Medicare Advantage contracts (membership fell 13.2% to 426,000). The stock's ~650% 2026 run drew a Citi downgrade to Sell on valuation (a 38% premium to peers) and 2027 margin-retention risk, alongside a fresh stockholder investigation echoing an older securities-fraud claim. The shares have already pulled back roughly 24% in a week into the Aug. 5 print.
AMN's staffing thesis doesn't hold up on its own numbers
AMN's headline Q1 (revenue +100% YoY) was driven almost entirely by $722M of one-off nurse-strike revenue that management called unsustainable, and Q2 guidance of just $620-635M implies a steep sequential drop. Its locums segment was down 6% YoY in Q1 with further declines guided, while industry data point to travel-nurse revenue edging up only ~1% industrywide in 2026 with bill rates still under pressure — a soft plateau, not the inflection the bull case requires.
Astrana and Pediatrix: acquisition-fueled growth versus steady-state value
Astrana's 55.6% revenue growth was substantially boosted by the Prospect Health acquisition, even as capitation revenue and full-risk mix genuinely expand; short interest has eased as an earlier accounting overhang faded. Pediatrix, trading at roughly 12x earnings versus Astrana's ~73x, reaffirmed stable payor mix and full-year EBITDA guidance ahead of its Aug. 4 report — the least re-rated, most conservative leg of the group. Pediatrix reports Aug. 4 and Agilon Aug. 5, making next week's prints the live test of which fundamental story the shared bull label actually reflects.