

Freight Core Still Grinding Higher; Telecom Drag Masks the Real Story
Prompt v1.0
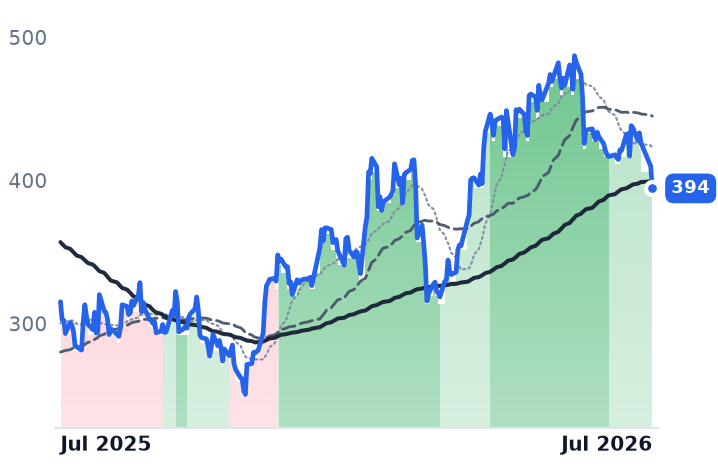
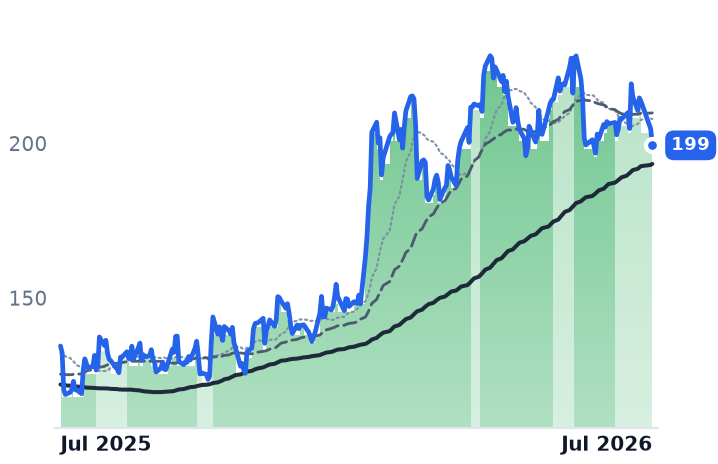
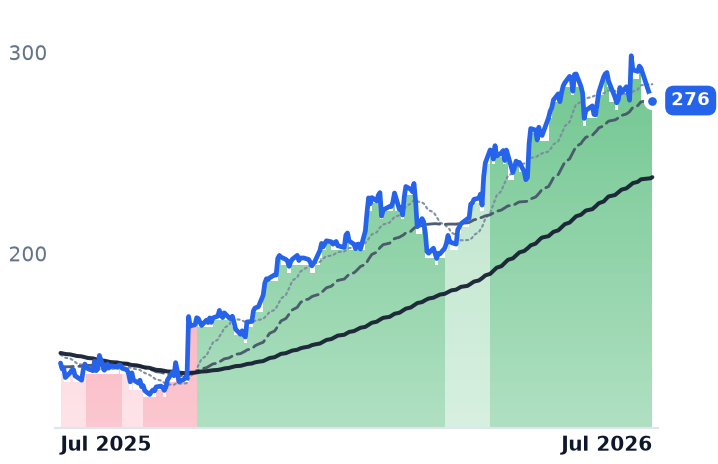
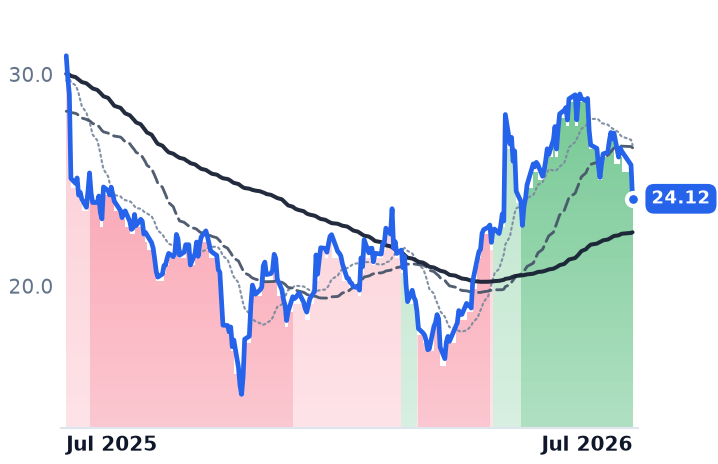
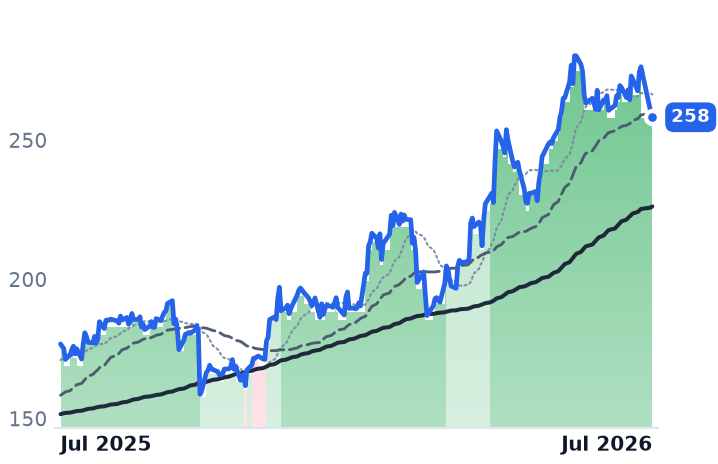
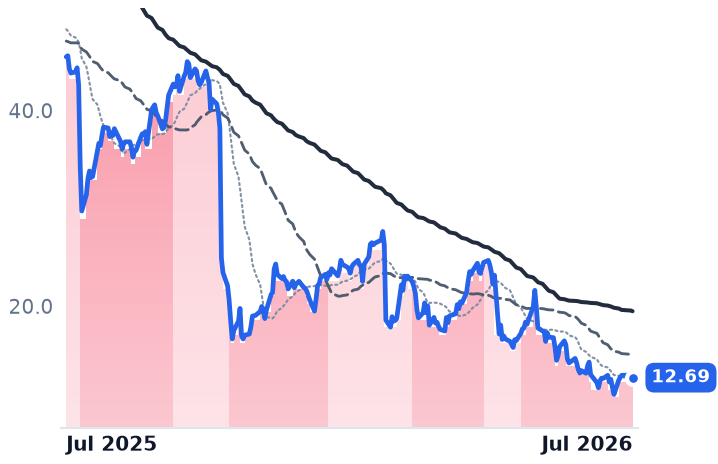
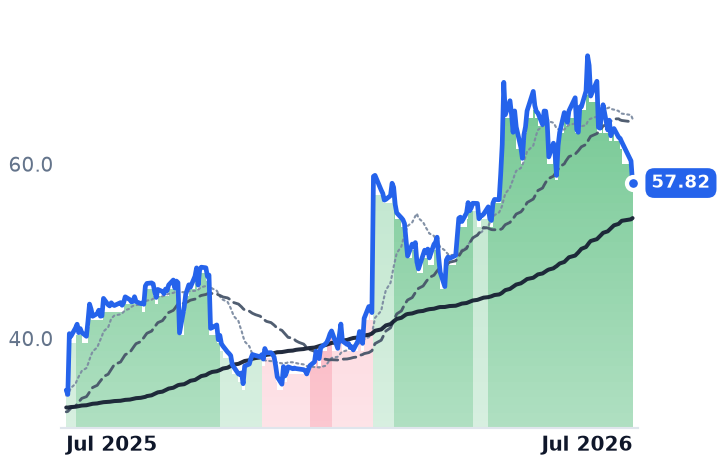
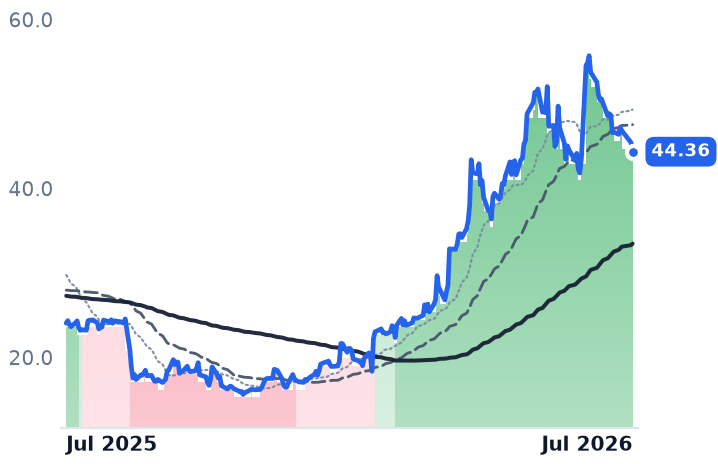
The watchlist's 17-name logistics/telecom bucket looks flat over 30 days, but that's an illusion: the 9-name freight core (rails, LTL, truckload/leasing) is uniformly in bull bands with strongly bullish streaks clustering since mid-April, while collapsing telecom names CCOI and TMUS are dragging the blended average down. Rail intermodal records, six straight months of positive truck tonnage, and driver-supply tightening from CDL enforcement support a genuine but capacity-led (not demand-led) freight cycle turn.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
UNP | Union Pacific | Freight Operators | 🟢 Cont. Bull | +7.1% | +32.9% |
NSC | Norfolk Southern | Freight Operators | 🟢 Cont. Bull | +6.0% | +22.6% |
CSX | CSX | Freight Operators | 🟢 Cont. Bull | +5.7% | +44.8% |
ODFL | Old Dominion Freight Line | LTL Specialists | 🟢 Cont. Bull | +1.4% | +38.1% |
SAIA | Saia | LTL Specialists | 🟢 Cont. Bull | −7.3% | +25.1% |
XPO | XPO Logistics | Diversified Carriers | 🟢 Cont. Bull | −3.3% | +48.3% |
JBHT | J.B. Hunt Transport Services | Intermodal & Trucking | 🟢 Cont. Bull | −4.1% | +89.6% |
WSC | WillScot | Modular Structures | 🟢 Cont. Bull | −16.1% | −21.9% |
R | Ryder System | Fleet & Transportation Assets | 🟢 Cont. Bull | −2.4% | +46.1% |
CCOI | Cogent Communications | Technology & Services | 🔴 Cont. Bear | −3.4% | −72.1% |
CGNX | Cognex | Test & Measurement | 🟢 Cont. Bull | −15.4% | +69.7% |
IRDM | Iridium Communications | Satellite Communications | 🟢 Cont. Bull | −18.7% | +84.4% |
ROK | Rockwell Automation | Industrial Automation & Motion Control | 🟢 Cont. Bull | −4.8% | +31.2% |
SYM | Symbotic | Industrial Automation & Motion Control | 🔴 Cont. Bear | −4.3% | −20.4% |
T | AT&T | US Tier-1 Wireless Carriers | ⚠️ Emerging Bear | +9.7% | −9.7% |
TMUS | T-Mobile US | US Tier-1 Wireless Carriers | 🔴 Cont. Bear | +4.3% | −23.1% |
VZ | Verizon Communications | US Tier-1 Wireless Carriers | 🟢 Cont. Bull | +7.1% | +16.1% |
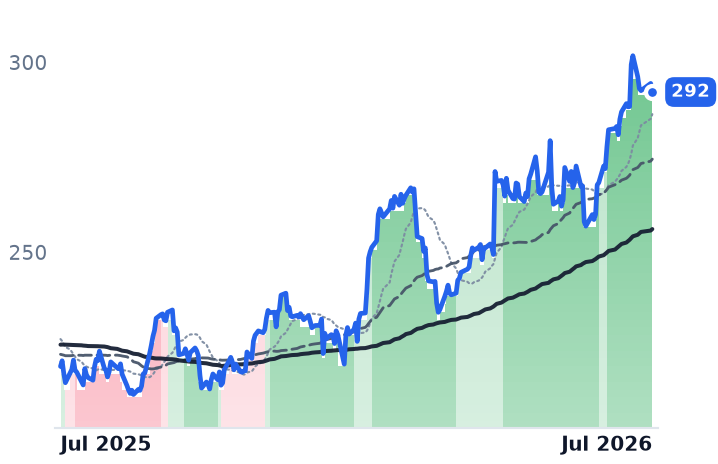
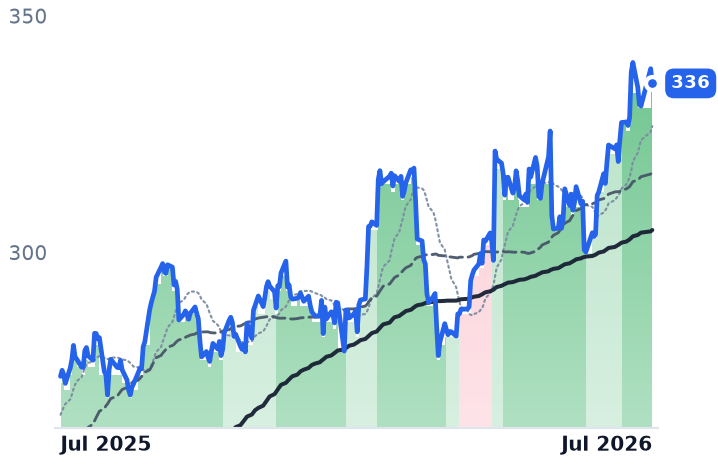
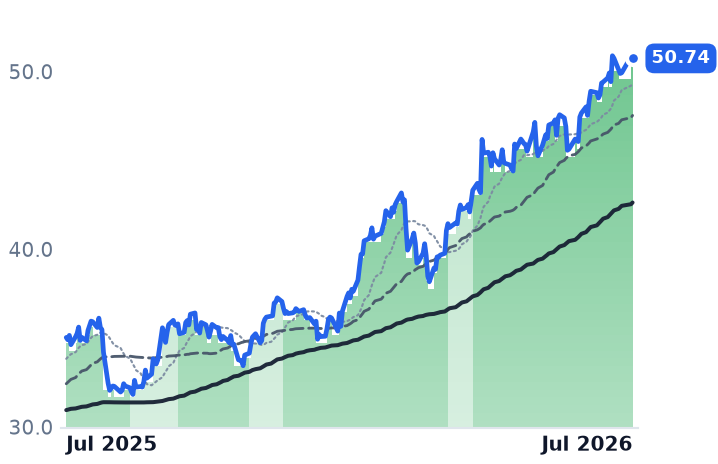
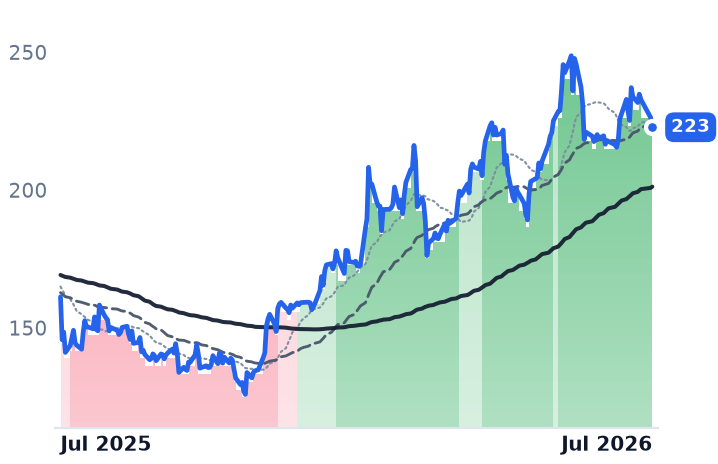
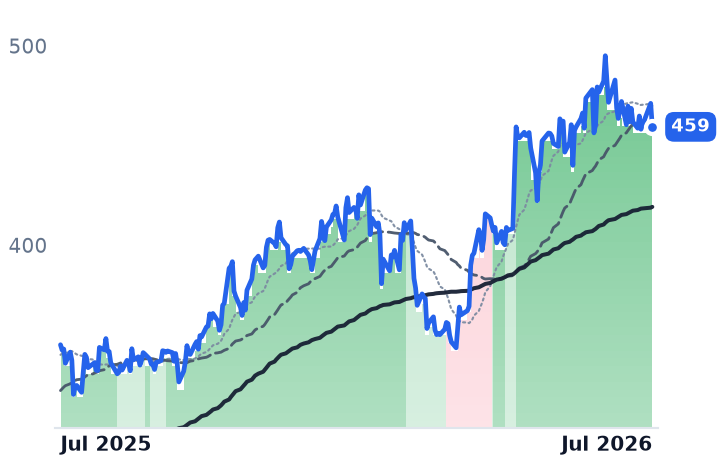
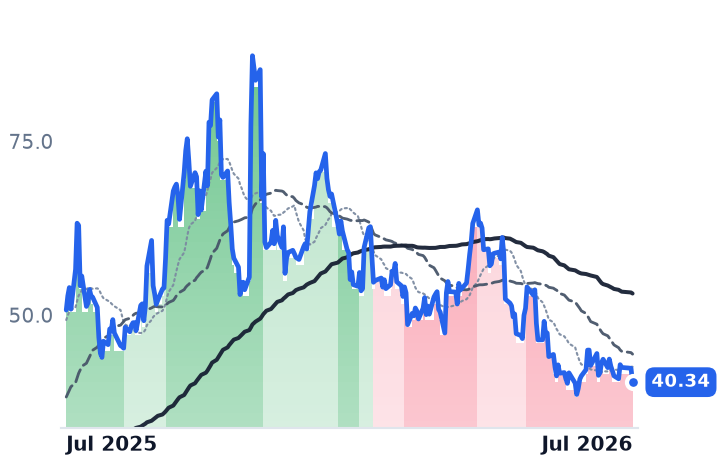
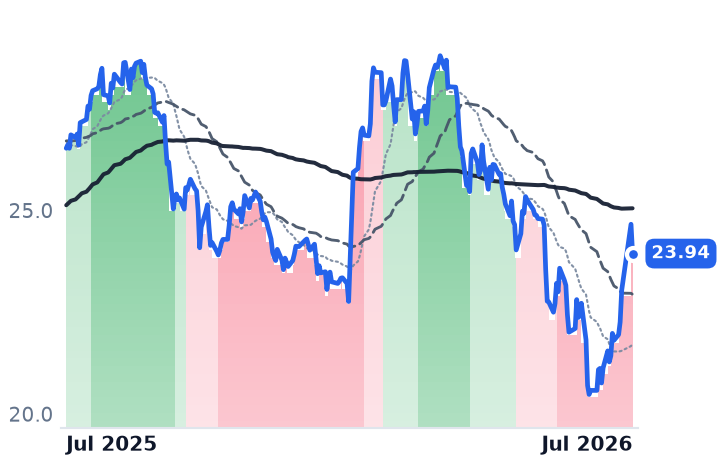
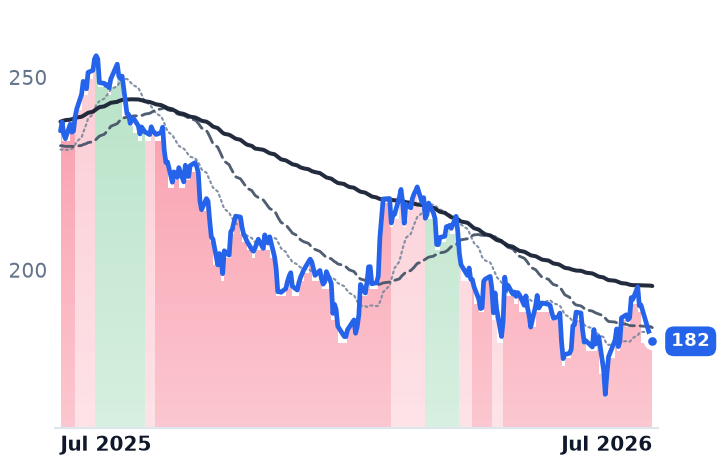
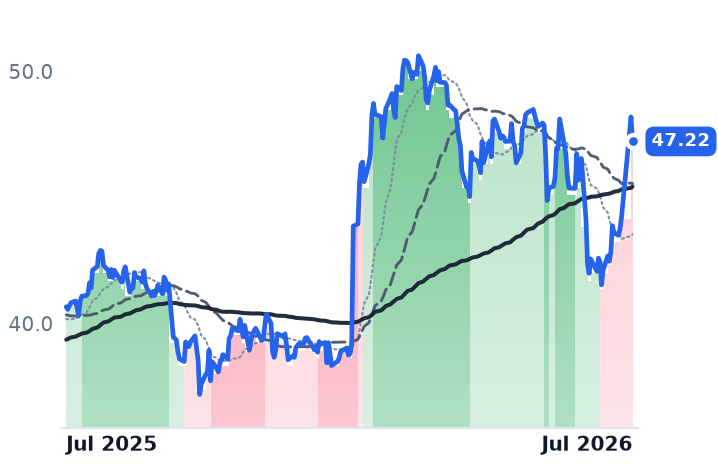
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
UNP | $165.4B | 22.5x | 21.3x | 6.5x | 6.1x | 14.3x | 13.4x | 14.6x | 3.9% |
NSC | $71.4B | 27.1x | 24.6x | 5.7x | 5.4x | 10.6x | 10.0x | 16.0x | 5.4% |
CSX | $87.5B | 27.3x | 23.6x | 6.0x | 5.7x | 17.1x | 16.3x | 15.8x | 5.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ODFL | $37.8B | 35.0x | 31.0x | 6.8x | 6.3x | 21.3x | 20.0x | 20.7x | 2.9% |
SAIA | $9.0B | 32.4x | 29.6x | 2.6x | 2.5x | 16.4x | 15.4x | 14.5x | 2.8% |
XPO | $20.8B | 51.7x | 32.3x | 2.4x | 2.3x | 19.0x | 18.0x | 19.0x | 2.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
JBHT | $21.5B | 32.6x | 30.3x | 1.7x | 1.6x | 10.4x | 9.6x | 13.8x | 5.1% |
WSC | $3.2B | n/m | 15.8x | 1.4x | 1.4x | 2.9x | 2.9x | 19.6x | 16.7% |
R | $9.1B | 19.3x | 16.2x | 0.7x | 0.7x | 3.7x | 3.6x | 4.7x | 7.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CCOI | $519.1M | n/m | — | 0.4x | 0.5x | 1.0x | 1.3x | 7.8x | -27.5% |
CGNX | $9.7B | 55.4x | 34.6x | 8.9x | 8.5x | 12.9x | 12.3x | 33.9x | 2.8% |
IRDM | $4.7B | 28.9x | 39.8x | 5.2x | 5.1x | 6.8x | 6.7x | 13.5x | 5.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ROK | $48.6B | 40.9x | 33.1x | 5.4x | 5.4x | 9.9x | 9.9x | 29.2x | 3.1% |
SYM | $28.0B | 456.1x | 213.1x | 10.6x | 10.0x | 49.1x | 46.3x | 434.2x | 2.6% |
T | $170.5B | 8.2x | 10.6x | 1.3x | 1.3x | 2.2x | 2.2x | 5.9x | 10.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TMUS | $195.9B | 19.1x | 16.7x | 2.1x | 2.1x | 3.9x | 3.8x | 10.9x | 7.8% |
VZ | $202.4B | 12.6x | 9.7x | 1.5x | 1.4x | 2.5x | 2.4x | 8.1x | 10.6% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
UNP | Revenue | +10.3% | +4.7% | +11.5% |
| EPS | +11.9% | +8.8% | +9.6% | |
NSC | Revenue | +9.1% | +4.6% | +4.0% |
| EPS | +7.3% | +11.2% | +9.7% | |
CSX | Revenue | +8.0% | +5.2% | +3.4% |
| EPS | +22.4% | +14.1% | +10.3% | |
ODFL | Revenue | +8.6% | +8.1% | +8.4% |
| EPS | +22.1% | +14.7% | +13.5% | |
SAIA | Revenue | +12.2% | +7.5% | +8.3% |
| EPS | +22.1% | +25.4% | +20.4% | |
XPO | Revenue | +11.5% | +5.3% | +6.6% |
| EPS | +52.4% | +18.9% | +21.9% | |
JBHT | Revenue | +14.3% | +9.7% | +8.4% |
| EPS | +25.3% | +32.6% | +19.1% | |
WSC | Revenue | +2.3% | +2.7% | +4.6% |
| EPS | −0.2% | +15.2% | +36.4% | |
R | Revenue | +7.0% | +5.1% | +6.9% |
| EPS | +13.9% | +20.1% | +18.6% | |
CCOI | Revenue | −1.6% | +4.5% | +6.4% |
| EPS | −11.7% | −21.4% | −23.5% | |
CGNX | Revenue | +16.7% | +9.3% | +9.4% |
| EPS | +74.7% | +19.4% | +15.3% | |
IRDM | Revenue | +5.2% | +5.5% | +3.8% |
| EPS | +3.6% | +13.7% | −17.1% | |
ROK | Revenue | +10.0% | +5.5% | +6.4% |
| EPS | +31.5% | +12.1% | +12.1% | |
SYM | Revenue | +25.7% | +29.2% | +24.5% |
| EPS | −15.6% | +82.3% | +121.2% | |
T | Revenue | +3.4% | +2.1% | +2.1% |
| EPS | +13.6% | +9.4% | +13.7% | |
TMUS | Revenue | +7.1% | +4.4% | +4.0% |
| EPS | +10.2% | +27.4% | +20.0% | |
VZ | Revenue | +2.3% | +1.7% | +1.1% |
| EPS | +6.8% | +4.7% | +7.1% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The bifurcation hiding in the blended average
The "Data Center: Logistics, Telecom & Adjacent" bucket's flat 30-day return conceals two very different stories. The 9-name freight core — rails UNP, NSC, CSX; LTL players ODFL, SAIA, XPO; and truckload/leasing names JBHT, R, WSC — sits uniformly in mildly bullish or strongly bullish bands as of July 28, with no member downgraded to a bear band in the trailing 30 days. Strongly bullish streaks for CSX, JBHT, ODFL and NSC all began within a tight mid-to-late-April window (CSX on April 17, JBHT on April 20, ODFL on April 15, NSC re-entering on April 28 after a brief whipsaw), pointing to a genuine cohort inflection rather than a handful of names carrying a mixed group. Over the past 30 days, UNP is up 9.7%, NSC up 8.3%, and CSX up 6.7%, even as JBHT, SAIA and WSC have pulled back modestly.
The drag comes from the bucket's non-freight legs. CCOI and SYM sit in strongly bearish bands, alongside T and TMUS, with VZ in mildly bearish. CCOI alone is down roughly 73% over the trailing year following Q4 2025 and Q1 2026 revenue misses, a dividend cut, and net leverage above 8x, far worse than anything in the freight names. That single collapse, not a freight rollover, is what flattens the headline 30-day average.
What the freight data actually shows
The fundamentals lean toward a real, capacity-driven cycle turn. Rail volumes hit record weekly intermodal levels in June, up 11.7% year-over-year, with Q2 carloads up 2.3%. The ATA tonnage index posted its sixth straight month of annual growth in May, and spot truckload rates are up roughly 31% year-over-year with tender rejections near 13%, the tightest capacity signal since early 2022. That tightness traces partly to English-proficiency and CDL enforcement actions that have sidelined roughly 20,000 drivers and revoked ~28,000 licenses, a supply-side shock rather than a demand boom.
The picture is uneven, though. Cass freight expenditures rose 11.2% in June, but the shipments component fell 4.1% year-over-year, meaning much of the gain is pricing, not volume. LTL is split the same way: Saia's tonnage per workday rose as much as 8.4% in May on genuine share gains, while Old Dominion's tons per day still declined year-over-year even as yield rose 5.4%. And the UNP-NSC deal remains a slow-moving regulatory process — the STB accepted the revised application in May with supplemental filings still underway and no close expected before 2027 — so it isn't a near-term price catalyst.
The freight core's bull streak looks real and broad-based rather than a merger-arb sideshow, but it's a capacity-tightening story more than a volume boom, and the bucket's blended optics are being distorted by unrelated telecom weakness.