

Nuclear's July flush is a lead-lag cascade, not a clean bucket split
Prompt v1.0
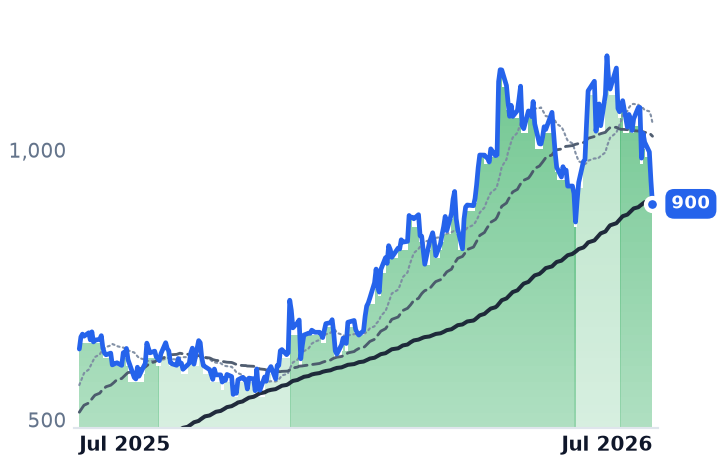
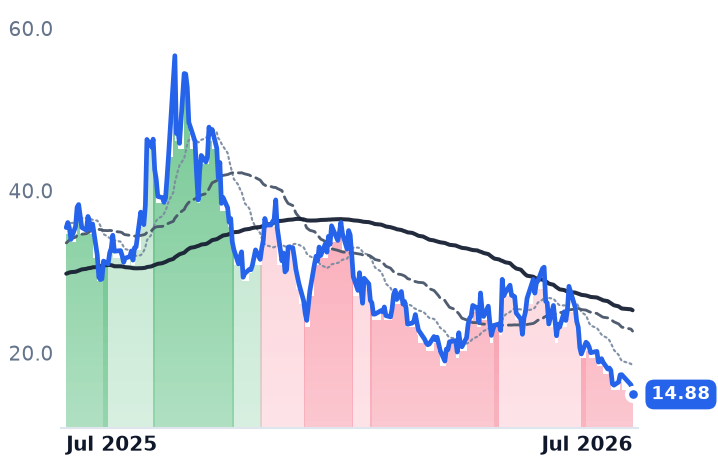
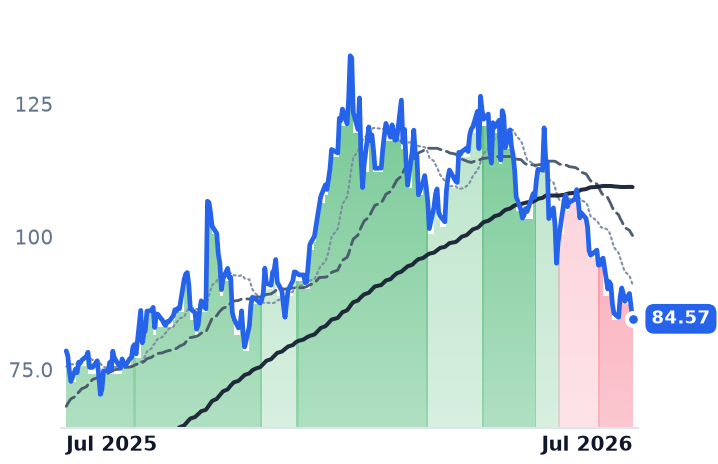
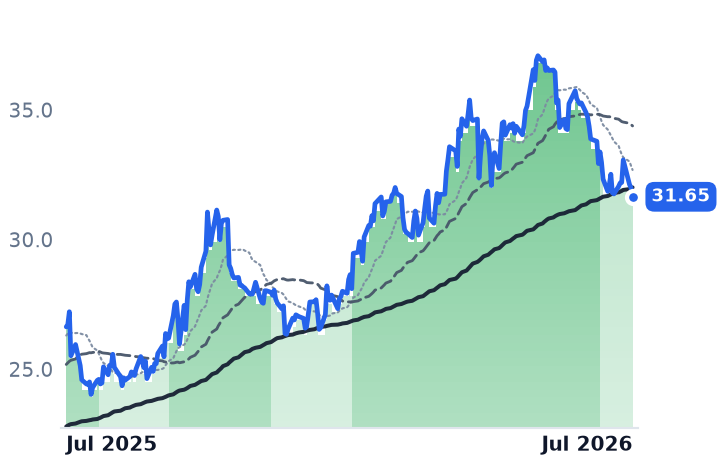
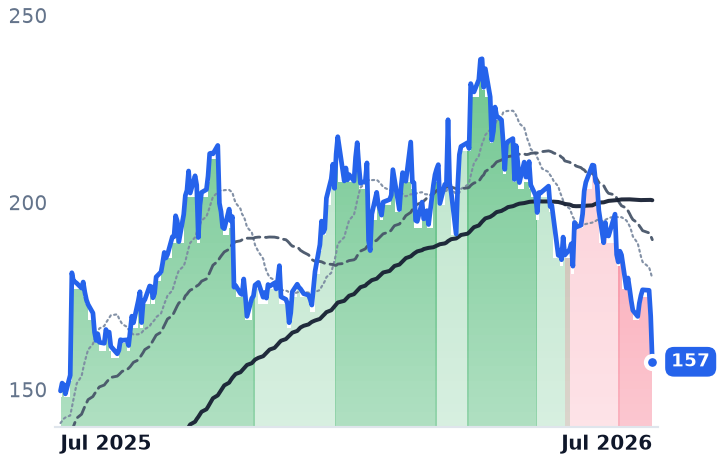
The premise that SMR developers have rolled over while the fuel/OEM leg (CCJ, BWXT, GEV) holds doesn't survive the band data — GE Vernova is still trend-strongly bullish despite an earnings-day EPS miss, while Cameco and BWXT both flipped to strongly bearish on July 7-8, seven months after the developers broke. Fundamentals (uranium term prices, BWXT backlog, hyperscaler PPA cadence, DOE loan support) mostly haven't deteriorated, framing this as a multiple reset with Cameco's Q2 print (7/31) and BWXT's (8/3) as the near-term arbiters.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
GEV | GE Vernova | Power Generation & Propulsion | 🟢 Cont. Bull | −18.3% | +42.6% |
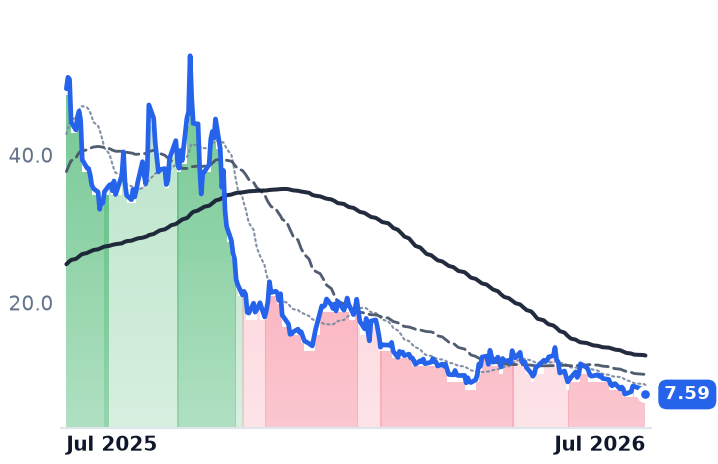
SMR | NuScale Power | Advanced Power Systems | 🔴 Cont. Bear | −26.0% | −84.5% |
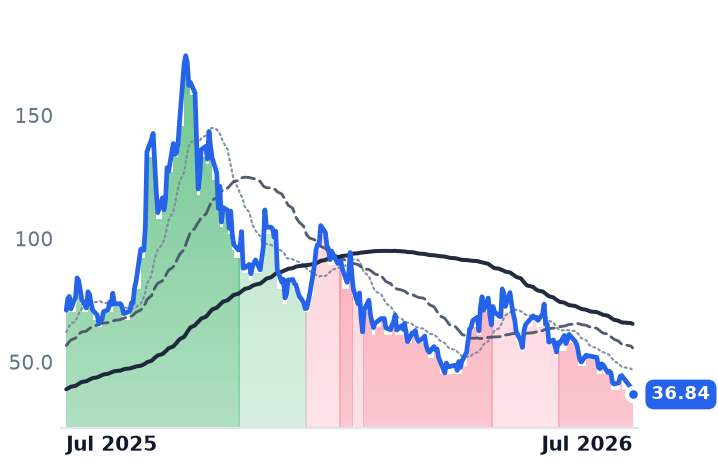
OKLO | Oklo | Advanced Nuclear | 🔴 Cont. Bear | −30.2% | −48.1% |
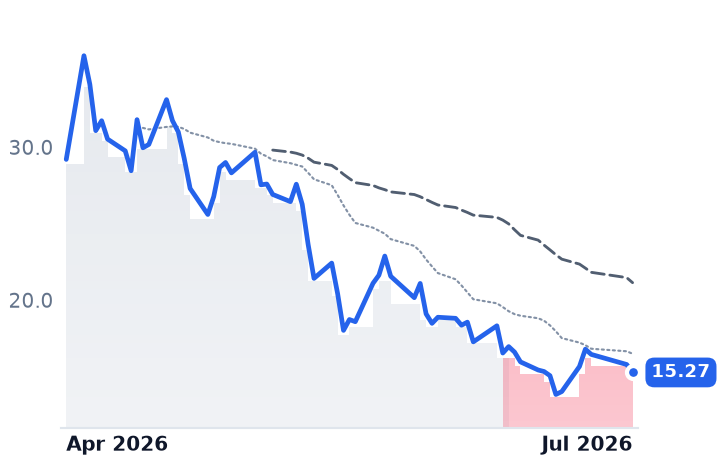
XE | X-Energy | Power & Propulsion Systems | 🔴 Cont. Bear | −18.8% | −47.7% |
NNE | Nano Nuclear Energy | Advanced Power Systems | 🔴 Cont. Bear | −30.2% | −58.0% |
CCJ | Cameco | Uranium | ⚠️ Emerging Bear | −18.3% | +7.7% |
BEP | Brookfield Renewable Partners | Diversified Generators | 🟢 Cont. Bull | −9.3% | +18.8% |
BWXT | BWX Technologies | Aerospace Components & Propulsion | ⚠️ Emerging Bear | −16.8% | +5.2% |
UEC | Uranium Energy | Uranium | ⚠️ Emerging Bear | −16.5% | +3.3% |
DNN | Denison Mines | Uranium | ⚠️ Emerging Bear | −13.8% | +26.3% |
NXE | NexGen Energy | Uranium | ⚠️ Emerging Bear | −7.9% | +27.6% |
LEU | Centrus Energy | Uranium | 🔴 Cont. Bear | −0.3% | −28.7% |
UUUU | Energy Fuels | Uranium | ⚠️ Emerging Bear | −26.4% | +13.4% |
LTBR | Lightbridge | Electrical Equipment & Parts | 🔴 Cont. Bear | −12.9% | −44.0% |
EU | enCore Energy | Uranium | 🔴 Cont. Bear | −20.3% | −61.7% |
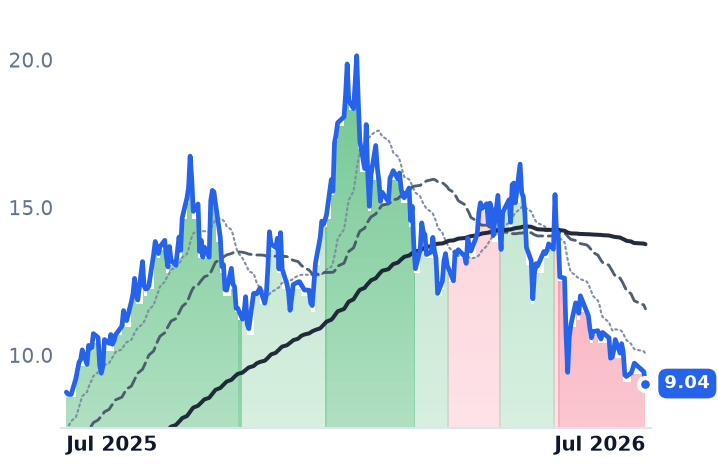
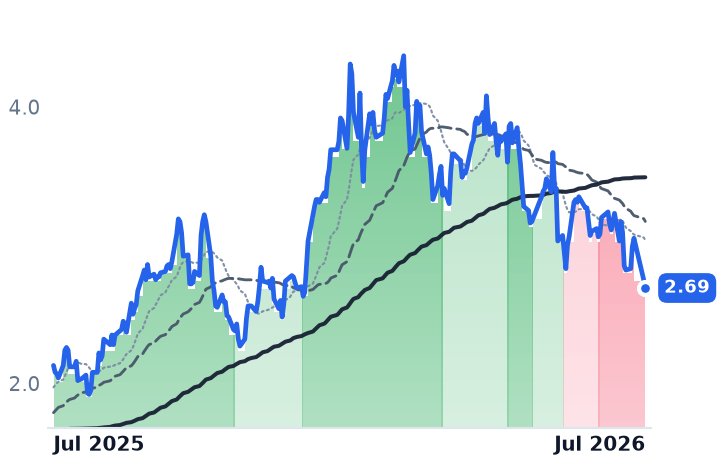
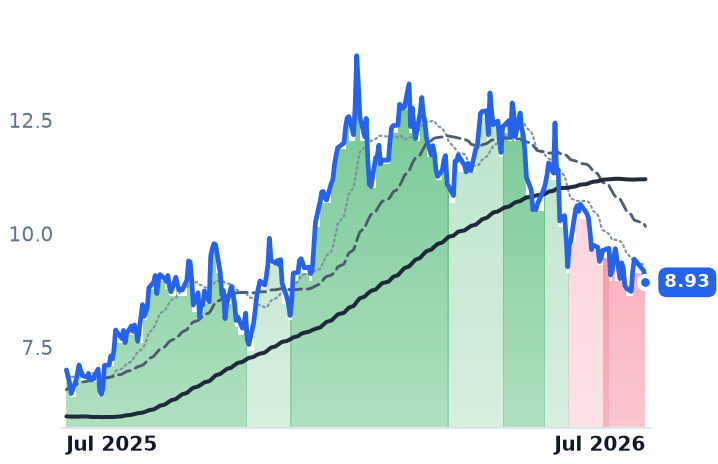
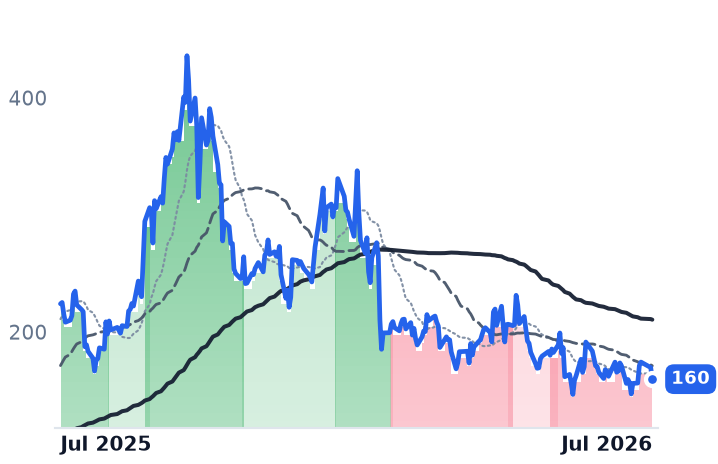
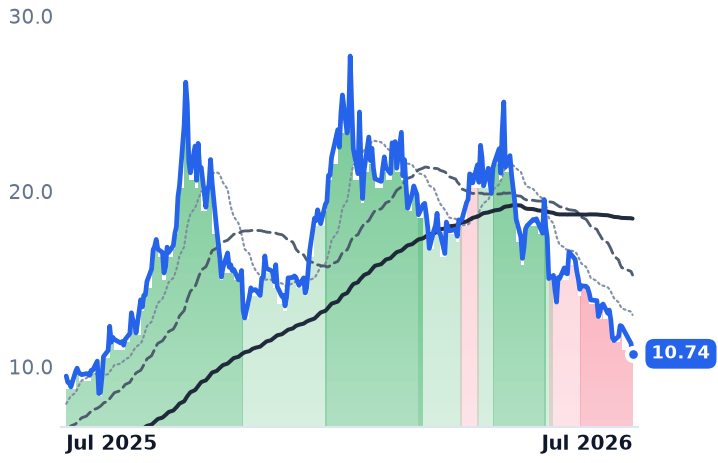
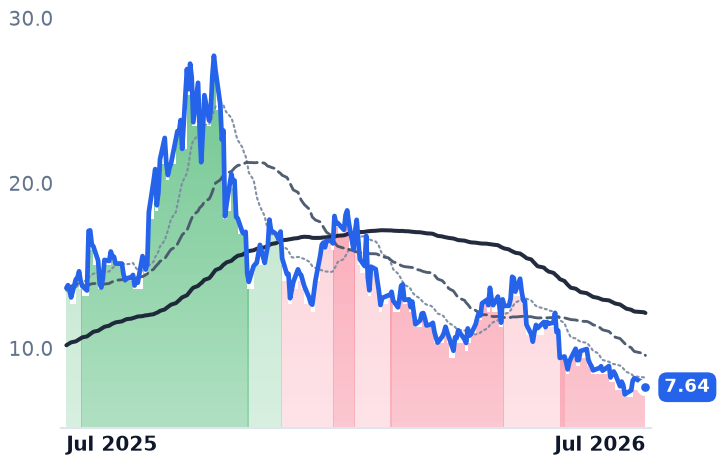
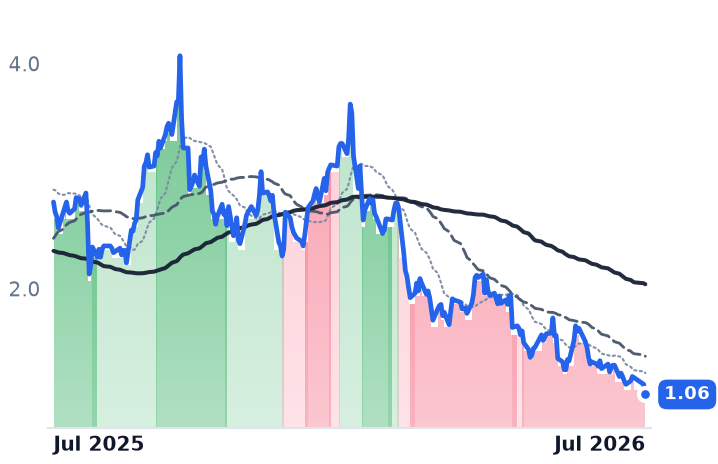
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
GEV | $211.0B | 20.7x | 25.2x | 4.8x | 4.5x | 22.0x | 20.7x | 19.0x | 8.1% |
SMR | $1.5B | n/m | — | 549.6x | 88.6x | — | — | n/m | -40.4% |
OKLO | $4.4B | n/m | — | — | — | — | — | n/m | -10.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
XE | $219.8M | n/m | — | 1.5x | 1.0x | — | — | 3.2x | -186.5% |
NNE | $585.0M | n/m | — | — | 78.6x | — | 270.4x | n/m | -6.7% |
CCJ | $30.1B | 106.4x | 52.1x | 12.2x | 8.6x | 51.3x | 36.1x | 48.8x | 0.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BEP | $8.7B | 62.8x | — | 1.4x | 1.3x | 5.6x | 5.3x | 9.6x | -54.4% |
BWXT | $12.0B | 33.7x | 27.6x | 3.4x | 3.1x | 15.4x | 14.3x | 24.2x | 2.6% |
UEC | $4.6B | n/m | — | 225.6x | 44.5x | 533.1x | 105.1x | n/m | -2.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DNN | $2.9B | n/m | — | 988.4x | 120.1x | — | — | n/m | -4.1% |
NXE | $7.2B | n/m | — | n/m | — | — | — | n/m | -2.4% |
LEU | $2.0B | 26.9x | 42.9x | 4.5x | 4.2x | 19.6x | 18.6x | 8.9x | -14.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
UUUU | $2.8B | n/m | — | 26.8x | 21.3x | 62.0x | 49.3x | n/m | -3.9% |
LTBR | $154.9M | n/m | — | n/m | — | — | — | 2.8x | -12.5% |
EU | $363.2M | n/m | — | 8.8x | 4.1x | 39.1x | 18.2x | n/m | -12.1% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
GEV | Revenue | +25.7% | +14.1% | +15.7% |
| EPS | +334.6% | −18.6% | +38.8% | |
SMR | Revenue | −59.6% | +507.1% | +271.3% |
| EPS | −77.1% | +14.4% | −16.3% | |
OKLO | Revenue | — | +231.0% | +435.4% |
| EPS | +62.4% | +8.3% | +11.3% | |
XE | Revenue | +81.4% | +289.0% | +42.5% |
| EPS | −96.6% | −38.4% | −29.6% | |
NNE | Revenue | +2627.0% | +309.5% | +1056.5% |
| EPS | −31.4% | +54.0% | +18.7% | |
CCJ | Revenue | +2.4% | +12.8% | +8.8% |
| EPS | −7.5% | +88.3% | +27.3% | |
BEP | Revenue | +3.4% | +9.5% | −3.3% |
| EPS | +11.4% | −10.5% | +9.0% | |
BWXT | Revenue | +20.7% | +8.9% | +9.7% |
| EPS | +24.1% | +10.5% | +13.9% | |
UEC | Revenue | −61.4% | +301.4% | +159.3% |
| EPS | +53.3% | −65.1% | −345.7% | |
DNN | Revenue | +394.2% | −27.3% | +1699.7% |
| EPS | −30.5% | −73.1% | −363.0% | |
NXE | Revenue | −68.7% | +131.4% | +32282.1% |
| EPS | −38.6% | −10.8% | +37.8% | |
LEU | Revenue | +6.9% | +4.5% | −5.5% |
| EPS | −46.4% | +46.7% | −12.2% | |
UUUU | Revenue | +128.1% | +88.3% | +62.7% |
| EPS | −37.3% | −160.5% | +170.0% | |
EU | Revenue | +101.0% | +20.6% | +72.5% |
| EPS | −66.0% | −114.4% | +1843.9% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The hypothesis frames the nuclear trade as splitting into two buckets — pre-revenue SMR developers breaking while fuel and large-reactor OEM names hold. The trend-band data says otherwise: this looks like a single cohort rolling over in sequence, not a fundamentals-driven bifurcation.
The bands don't split cleanly
GE Vernova's own trend band is still strongly bullish as of today, unchanged despite Wednesday's -5.3% single-day move. That move was an earnings-day reaction — GEV's Q2 2026 adjusted EPS of $2.47 missed the $3.04 consensus on a -$275M Wind-segment loss, even as revenue beat, orders jumped 88% YoY to $24.2B, and backlog hit a record $176B. The company also signed two additional SMR early-work agreements and continues advancing its BWRX-300 project — the nuclear-adjacent leg is expanding, not shrinking.
Meanwhile the "still bullish" label on the CCJ/BWXT/BEP bucket is stale for two of three names. CCJ and BWXT both flipped to strongly bearish on July 7 and July 8 respectively, over 30-day windows both are down double digits (CCJ -16.0%, BWXT -10.3% against BEP's milder -8.3%), and only BEP still sits in an unambiguous bull band (downgraded from strongly bullish to mildly bullish on July 8). That's not "fuel/OEM holding" — it's the same rollover arriving later. SMR developers (SMR, OKLO, XE, NNE) entered strongly bearish between December 2025 and February 2026; uranium miners followed in June; Cameco and BWXT broke last, in early July. All ten-plus names in the complex now sit at the bottom trend score.
Fundamentals haven't moved in step with price
The underlying data mostly contradicts a fundamental turn. Uranium term pricing has ground up to roughly $86/lb, up 8.86% year-to-date, even as spot slid from above $101 to the mid-$80s. Cameco reaffirmed 2026 production guidance after a brief, supply-side Cigar Lake suspension. BWXT raised 2026 EBITDA guidance to $650-665M on a 77% backlog jump to $8.65B, yet still fell nearly 14% on doubled volume. Hyperscaler nuclear demand hasn't cooled either — all four major hyperscalers had signed nuclear deals by May 2026, totaling 9.8-10 GW, and DOE has committed $17.5B in loans to the nuclear supply chain.
The one clear exception is NuScale: quarterly revenue collapsed from roughly $8M to $0.6M, alongside securities-fraud litigation — a genuine operational break rather than pure multiple compression. The broader developer-cohort flush also has a dated trigger: Truist initiated coverage of the pre-revenue SMR names at Hold in mid-July, and each fell 8-9% that session.
What's next
Consensus price targets still sit well above spot for both CCJ ($133.78) and BWXT ($229), even as BofA trimmed its Cameco target. Cameco reports Q2 results before the open on July 31, and BWXT follows on August 3 — the two prints most likely to determine whether the complex's de-rating is a valuation reset or the start of a fundamentals-driven turn.