

Satellite Bucket's 120% Year Hides a Two-Name, M&A-Driven Story
Hypothesis Opus 5 · Research Sonnet 5 · Writing Sonnet 5 · Prompt v1.0
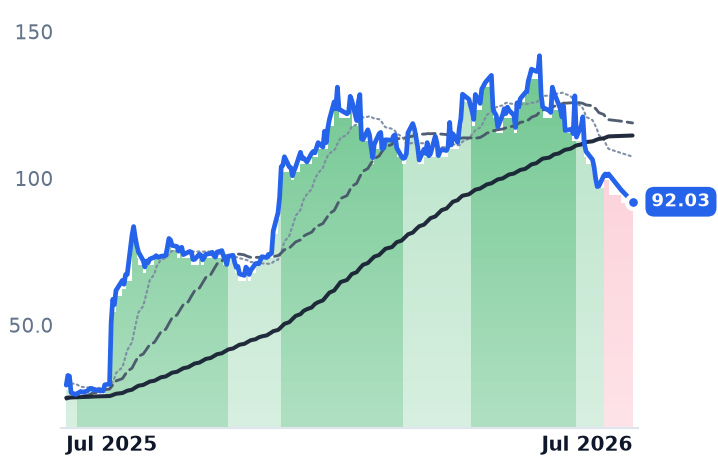
The SPACE bucket's headline +120.7% one-year average masks extreme dispersion: EchoStar's spectrum monetization and Viasat's Ligado-fueled deleveraging drove most of the gain, Iridium's biggest leg was a late-June acquisition pop from Rocket Lab, Gogo has fallen roughly 75% in a nine-month bear band, and EchoStar itself is already down over 21% in the last 30 days heading into July 30 earnings.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
SATS | EchoStar | Satellite & Broadband Services | ⚠️ Emerging Bear | −8.7% | +211.9% |
VSAT | Viasat | Satellite & Broadband Services | 🟢 Cont. Bull | −8.5% | +377.8% |
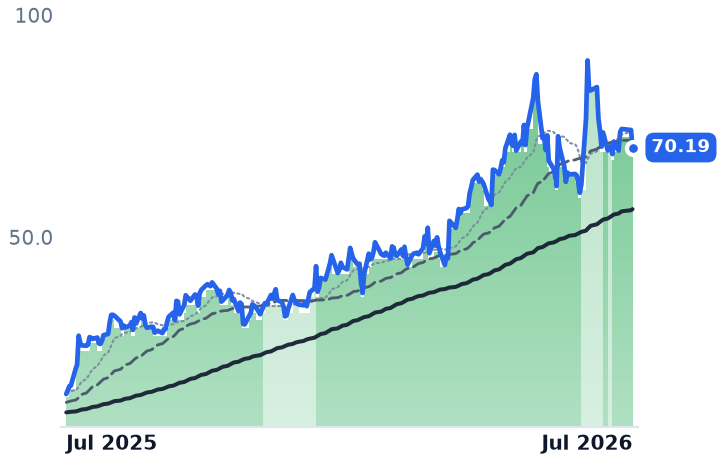
IRDM | Iridium Communications | Specialty & Small Carriers | 🌱 Emerging Bull | −18.7% | +84.4% |
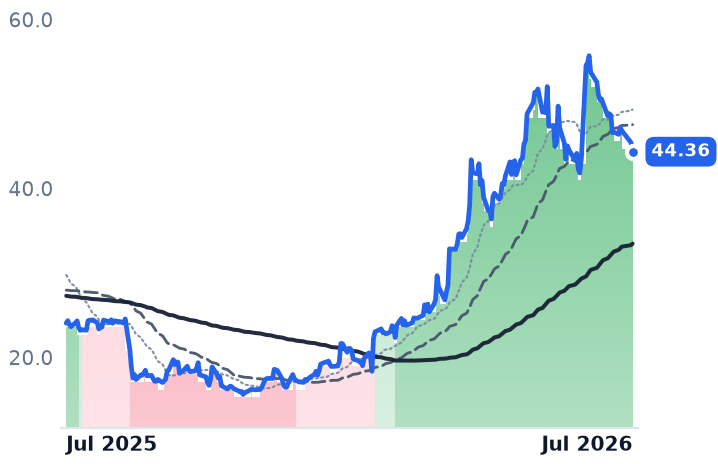
TSAT | Telesat | Satellite & Broadband Services | 🟢 Cont. Bull | −25.2% | +41.8% |
SIRI | Sirius XM | Music & Audio | 🌱 Emerging Bull | +11.5% | +45.2% |
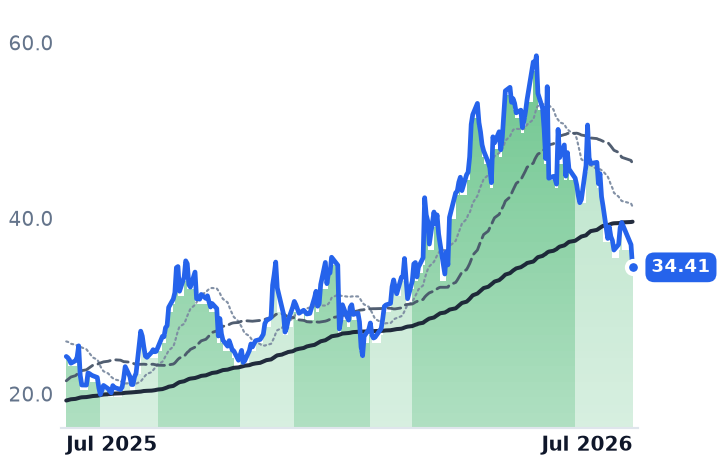
GOGO | Gogo | Niche Connectivity | 🔴 Cont. Bear | +25.6% | −76.1% |
| Compared against · context, not the story | |||||
RKLB | Rocket Lab USA | Unmanned Systems & ISR | 🟢 Cont. Bull | −40.2% | +33.8% |
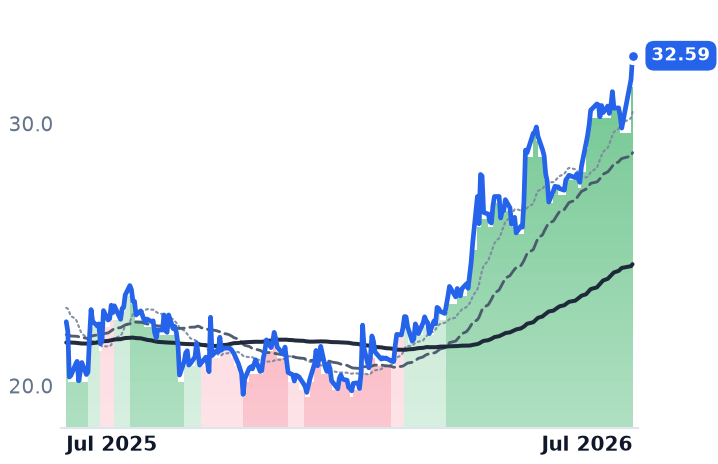
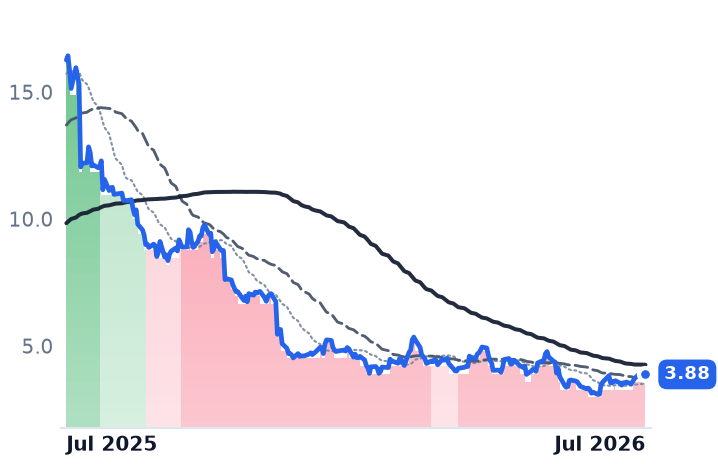
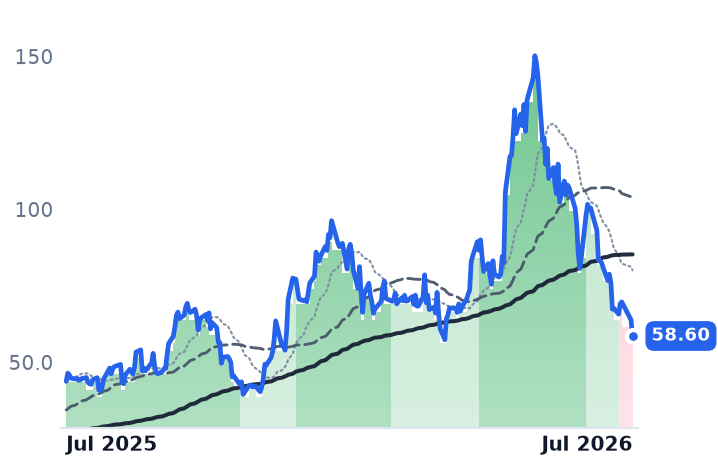
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SATS | $25.1B | n/m | 4.6x | 1.7x | 1.7x | 5.8x | 5.9x | n/m | -1.1% |
VSAT | $11.4B | n/m | — | 2.5x | 2.4x | 8.1x | 7.7x | 9.3x | 5.1% |
IRDM | $5.3B | 57.0x | 48.9x | 6.0x | 5.8x | 8.5x | 8.2x | 16.3x | 5.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TSAT | $778.2M | n/m | — | 2.8x | 2.4x | 4.3x | 3.8x | n/m | -52.6% |
SIRI | $8.7B | 10.3x | 8.3x | 1.0x | 1.0x | 2.2x | 2.2x | 8.4x | 15.6% |
GOGO | $524.7M | 37.7x | 11.4x | 0.6x | 0.6x | 1.1x | 1.1x | 8.4x | -0.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
RKLB | $72.2B | n/m | — | 106.3x | 79.7x | 290.7x | 218.0x | n/m | -0.4% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
SATS | Revenue | −4.0% | −5.7% | −7.6% |
| EPS | −141.8% | −86.6% | +31.6% | |
VSAT | Revenue | +3.6% | +4.0% | +4.4% |
| EPS | −66.9% | +41.0% | +5.7% | |
IRDM | Revenue | +4.5% | +4.9% | +9.7% |
| EPS | −4.2% | +33.5% | +20.3% | |
TSAT | Revenue | −22.5% | −14.0% | +101.1% |
| EPS | +52.5% | +7.6% | −25.1% | |
SIRI | Revenue | +0.3% | +1.4% | +1.4% |
| EPS | +12.2% | +9.1% | +5.2% | |
GOGO | Revenue | +1.4% | +3.2% | — |
| EPS | +75.8% | +50.0% | — | |
RKLB | Revenue | +51.0% | +39.0% | +27.0% |
| EPS | −41.8% | −100.1% | +68844.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Member by member, not a cohort move
One-year price returns across the six names range from Viasat's +398.9% to Gogo's -75.1%, with EchoStar/SATS (renamed ECHO) up +209.1%, Iridium up +77.9%, Telesat up +46.0% and SiriusXM up +35.1% — an average near 120% built on extreme dispersion rather than broad participation. Current trend bands confirm the split: IRDM, SIRI and VSAT sit in strongly bullish, TSAT is mildly bullish, GOGO is strongly bearish, and EchoStar's feed last showed a downgrade to mildly bearish around June 29 before data stopped updating on July 17.
Gogo is the clearest rollover: it has held a strongly bearish or mildly bearish band continuously since roughly late October 2025, on softer 2026 guidance and a 9% year-over-year decline in business aviation service revenue, prompting JPMorgan to cut its price target to $7 from $11 while shares traded roughly 74% below their 52-week high. The company's Galileo LEO rollout — 92 units shipped in Q1 2026 across VistaJet, Wheels Up and a planned NetJets Europe deployment — is a real growth vector but hasn't been large enough to reverse the stock's downtrend.
Iridium's strongly bullish band looks less like organic re-rating and more like arbitrage: on June 29, Rocket Lab agreed to acquire Iridium for $54.00 per share, an 8.0 billion enterprise value, and the ticker jumped roughly 25% in two sessions — a violent single-day move that contradicts a "gradual" cohort narrative. Underlying operations were mixed: Q2 2026 subscriber growth was solid at +6% to 2.627 million, led by commercial IoT, but the government EMSS contract the hypothesis cites as renewed actually expires in September 2026 with no new agreement expected before March 2027, and SpaceX's $4.16 billion Space Force satcom contract signals encroaching competition.
Viasat's rally rests on genuine deleveraging — net debt down to $4.84B against $2.9B liquidity — which drew an Oppenheimer Outperform rating and $140 price target, and a Deutsche Bank target hike to $97, alongside a BMW automotive satellite-connectivity demo. EchoStar's move was driven almost entirely by FCC-approved spectrum sales worth roughly $22.65B cash from AT&T plus a SpaceX stake, yet the stock was down 21.4% over the trailing 30 days to $87.14 by July 24 ahead of July 30 earnings — the single biggest contributor to the year's average already stalling from current levels. SiriusXM's nearly 50% first-half rally was tied to a YouTube ad-tech partnership and SpaceX-IPO spectrum-value attention rather than subscriber growth, while Telesat's gain is anticipatory ahead of Lightspeed launches beginning mid-2026 and full service only in late 2027.