

OTA Watchlist Splits 3-1 on a Crude-Driven Bounce, Not an AI Re-Rating
Hypothesis Opus 5 · Research Sonnet 5 · Writing Sonnet 5 · Prompt v1.0
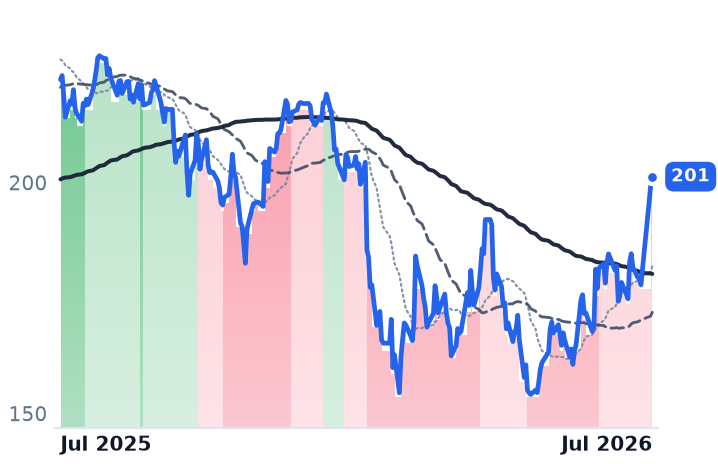
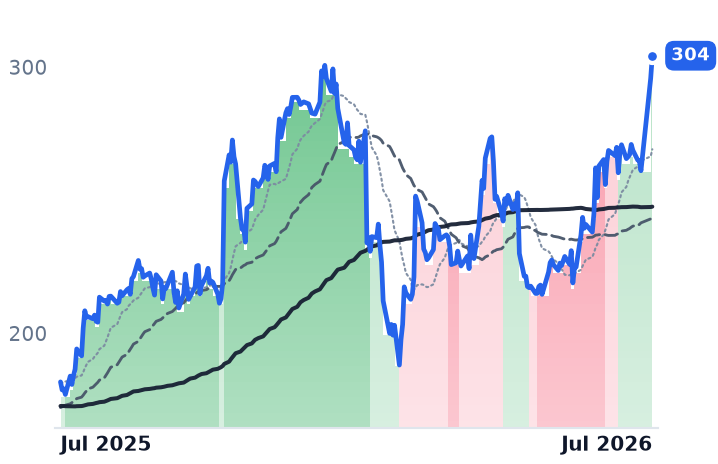
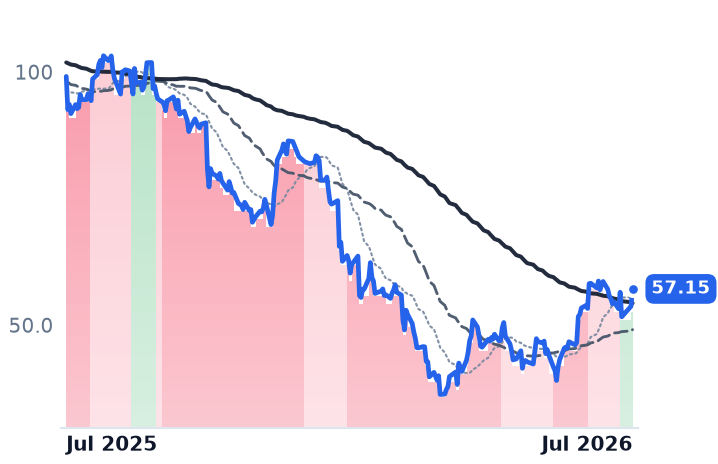
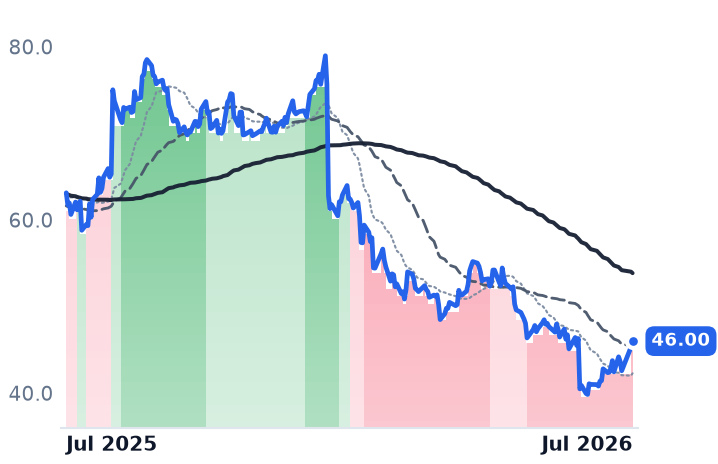
BKNG, EXPE and MMYT have genuinely crossed from mildly bearish into mildly bullish trend bands over a staggered three-week window, but TCOM — the group's second-biggest 30-day gainer — remains stuck in strongly bearish, and the late-July acceleration traces to falling crude and Strait of Hormuz de-escalation rather than Q2 earnings or an AI-driven fundamental shift.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
BKNG | Booking | Online Travel Agencies | 🔴 Cont. Bear | +10.4% | −9.5% |
EXPE | Expedia | Online Travel Agencies | ⚠️ Emerging Bear | +14.7% | +67.4% |
MMYT | MakeMyTrip | Online Travel Agencies | 🔴 Cont. Bear | +6.0% | −42.3% |
TCOM | Trip.com | Online Travel Agencies | ⚠️ Emerging Bear | +15.1% | −27.1% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BKNG | $149.5B | 25.3x | 18.5x | 5.4x | 5.1x | 5.4x | 5.1x | 16.0x | 6.0% |
EXPE | $33.7B | 24.6x | 14.8x | 2.2x | 2.1x | 2.5x | 2.3x | 10.0x | 13.9% |
MMYT | $5.4B | 114.6x | 109.7x | 5.1x | 4.5x | 7.4x | 6.4x | 30.0x | 2.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TCOM | $29.6B | 6.6x | — | 3.1x | — | 3.8x | — | 4.8x | 6.8% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
BKNG | Revenue | +9.8% | +9.2% | +8.3% |
| EPS | +14.8% | +17.8% | +16.2% | |
EXPE | Revenue | +9.6% | +7.0% | +7.9% |
| EPS | +29.3% | +15.7% | +18.3% | |
MMYT | Revenue | +12.6% | +7.4% | +17.2% |
| EPS | −48.0% | +18.9% | +89.4% | |
TCOM | Revenue | +9.6% | +10.9% | +10.5% |
| EPS | −48.1% | +17.1% | +10.5% |
Forward fiscal years only. Blank means no analyst coverage for that year.
What's happening
The four-name Online Travel Agencies bucket (BKNG, EXPE, MMYT, TCOM) is up roughly 11.6% on average over the past 30 days, but the composition of that move matters more than the headline number. Three of four names — BKNG, EXPE, MMYT — have crossed moving-average trend signal trend bands from mildly bearish into mildly bullish over a staggered one-to-three-week window, not in a single synchronized jump. TCOM, despite posting the group's second-largest 30-day price gain, has stayed in strongly bearish since a May transition and has not flipped.
Most of BKNG's and EXPE's gains are concentrated in just the final two trading sessions of the window (7/28-7/29), and the proximate trigger looks macro rather than fundamental: crude oil falling below $70/barrel and reports the Strait of Hormuz is preparing to reopen, which unwound the Middle East travel-demand headwind that had forced Booking to guide Q2 room-night growth down to just 2-4% after a strong Q1 ($5.5B revenue, +16% YoY, 338M room nights) that beat estimates. Critically, Booking's and Expedia's actual Q2 prints had not been reported as of 7/29, so the rally is running ahead of, not confirming, the fundamentals. Expedia's own guidance reaffirmed full-year gross bookings growth of 6-8%, and Argus lifted its price target to $315 from $270 citing broad travel-recovery signs and a historically cheap multiple.
The AI-disintermediation question is unresolved
Evidence cuts both ways. OpenAI's March reversal on in-ChatGPT checkout — moving Instant Checkout back to external apps — was read in trade press as defending the OTAs' transaction layer, and Booking has been building its own agentic AI tools and model partnerships. But a study of Google AI Mode travel queries found OTAs capture only 3.6% of clicks despite 46.6% of citations — a live customer-acquisition-cost risk that neither company's guidance has yet addressed.
Regional divergence explains the split
MMYT's band flip is backed by real fundamentals: 20%+ hotel room-night growth and $10B+ FY26 gross bookings, plus domestic-air share gains. TCOM's holdout status looks similarly grounded — trade press argues its international-expansion story is running ahead of a domestic China recovery that hasn't arrived, compounded by a recent Chinese antitrust penalty forcing distribution and pricing changes, even as China's outbound travel market is projected to nearly triple by 2036. Separately, transatlantic US-bound demand remains soft, concentrated in UK travelers rather than broad European weakness — a swing factor for BKNG and EXPE's international mix heading into Q2 prints due within the next two weeks.