

Nitrogen/Methanol Bucket's Rally Looks Like a War-Driven Round Trip
Hypothesis Opus 5 · Research Sonnet 5 · Writing Sonnet 5 · Prompt v1.0
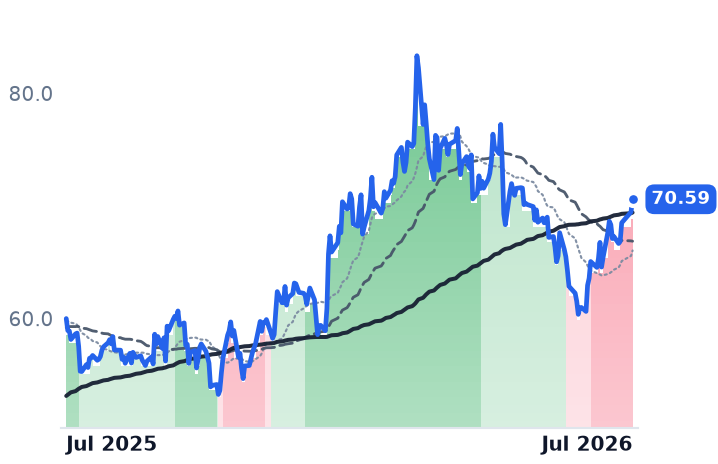
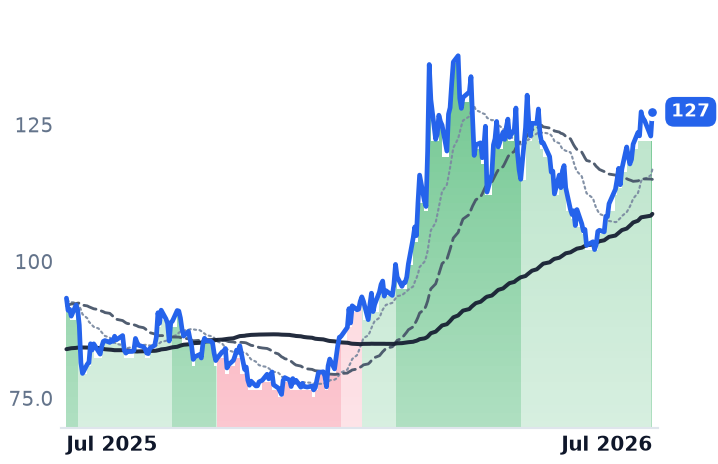
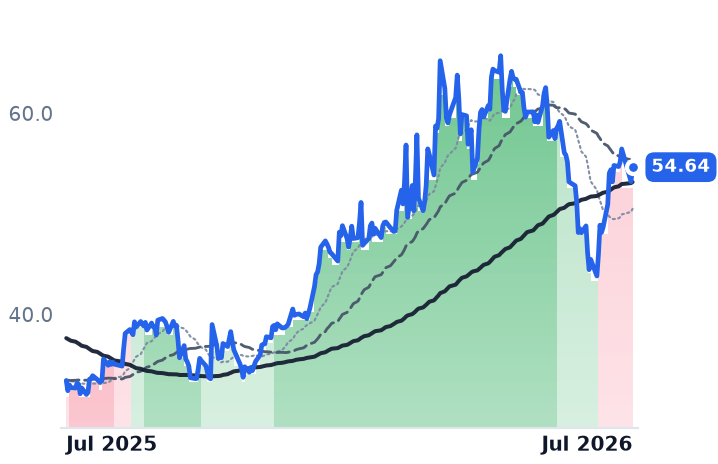
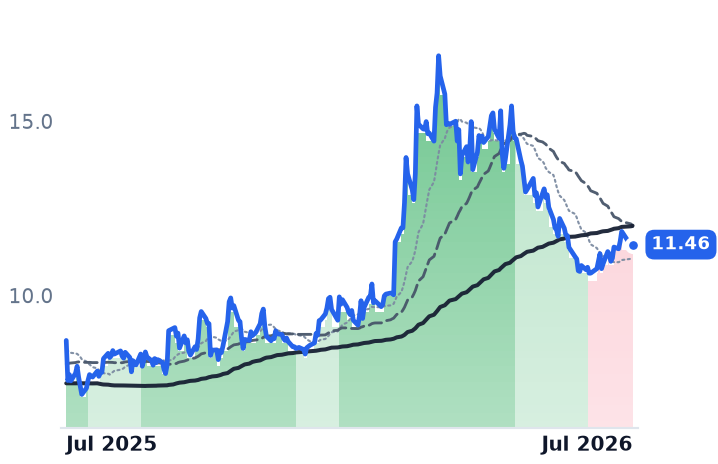
The 30-day gain across NTR, CF, MEOH and LXU is real, but trend-band data shows the group is not in a broad, gradual bull run — three of four names are still bear-banded and the rally traces back to a Persian Gulf supply shock that has already partly unwound, not a smoothly widening gas-to-nitrogen spread.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
NTR | Nutrien | Fertilizer Distribution & Retail | ⚠️ Emerging Bear | +16.4% | +17.7% |
CF | CF Industries | Nitrogen Fertilizers | 🟢 Cont. Bull | +20.8% | +36.5% |
MEOH | Methanex | Basic Chemicals & Intermediates | 🟢 Cont. Bull | +12.0% | +63.4% |
LXU | LSB Industries | Basic Chemicals & Intermediates | ⚠️ Emerging Bear | +6.7% | +31.6% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NTR | $33.2B | — | 12.5x | — | 1.2x | — | — | 7.3x | 6.7% |
CF | $19.2B | 11.2x | 7.5x | 2.6x | 2.3x | 6.4x | 5.6x | 5.6x | 8.4% |
MEOH | $4.3B | 52.4x | 6.1x | 1.0x | 0.9x | 3.5x | 3.1x | 6.4x | 17.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
LXU | $782.7M | 21.8x | 10.5x | 1.2x | 1.2x | 6.9x | 6.8x | 8.2x | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
NTR | Revenue | +7.0% | −2.4% | −1.5% |
| EPS | +19.7% | −6.9% | −11.7% | |
CF | Revenue | +22.1% | −14.6% | −6.7% |
| EPS | +87.5% | −34.2% | −18.0% | |
MEOH | Revenue | +30.0% | −16.1% | −3.3% |
| EPS | +203.5% | −37.8% | −26.0% | |
LXU | Revenue | +11.0% | −4.8% | −0.3% |
| EPS | +201.3% | −31.6% | +9.2% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The nitrogen/methanol names have indeed moved together over the past month, averaging roughly +11.5% (CF +16.3%, NTR +13.9%, MEOH +10.6%, LXU +5.3%) and about +34.6% over a year. But the trend-band history tells a messier story than a clean, gradual continued-bull cohort. As of today, LXU and MEOH sit in mildly bearish bands, NTR has been in strongly bearish since July 2, and only CF flipped to strongly bullish — on today's print alone, a one-day-old signal rather than a persistent streak.
A round trip, not a slow burn
Zooming out to 90 days exposes the real shape of the move: CF is roughly flat (-1.3%), while NTR (-6.1%), MEOH (-16.3%) and LXU (-24.6%) are all still underwater from their late-April peaks. The group's genuine "continued bull" streak was a Q1/early-Q2 2026 event, driven by a Persian Gulf conflict beginning in February that disrupted the Strait of Hormuz, which carries 20-30% of global fertilizer exports. That shock sent urea from about $400/mt to over $850/mt and ammonia from an $828/mt average to $1,123/mt by mid-April. The subsequent May-June rollover in the bands coincides with China reopening urea exports with quotas and price floors around $660-670/mt FOB, which crashed benchmark prices back down. NOLA urea now sits around $430/mt, up 16.85% on the trailing month but still 5.29% below year-ago levels — volatile and event-driven, not a smooth spread expansion.
Gas is falling for its own reasons
Henry Hub's slide to roughly $2.68 is attributed to strong production, ample storage, and Permian pipelines diverting supply toward the Gulf Coast — a supply-side story running in parallel with, not causally tied to, the nitrogen names' bounce. Separately, secondary data suggests European ammonia costs rising versus falling North American costs, consistent with a cost-advantage thesis, though this should be read as indicative given the source tier.
Idiosyncratic drivers, not a uniform trade
MEOH's move looks tied to its own catalyst: Methanex posted a Q3 European contract price of €915/MT, up from €850/MT, alongside the Geismar 3 restart materially adding Gulf Coast supply. LXU has its own thread in the El Dorado low-carbon ammonia project reaching pre-certification for a late-2026 startup. Meanwhile CF's valuation discount has largely closed, with its forward P/E re-rating to about 15.65x from 7.95x earlier in the year, and new global capacity — including Russian and Indian urea/ammonia plants in 2026 and US projects at Donaldsonville and St James Parish in 2027 — is scheduled to land over the next two years. CF and Nutrien both report Q2 results around August 5, with consensus already pricing large year-over-year earnings growth.