

Grid-Equipment Pullback Looks Like a Reset, Not a Rollover
Hypothesis Opus 5 · Research Sonnet 5 · Writing Sonnet 5 · Prompt v1.0
Despite a 16.8% one-month drawdown across the AI-grid/switchgear-transformer cohort, only two of roughly ten tracked names — Hubbell and Hyundai Electric — have actually crossed from bull into bear trend bands, and both moves trace to idiosyncratic or macro factors rather than a demand rollover. Backlogs, book-to-bill, and transformer lead times across the group still point to an intact multi-year shortage.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
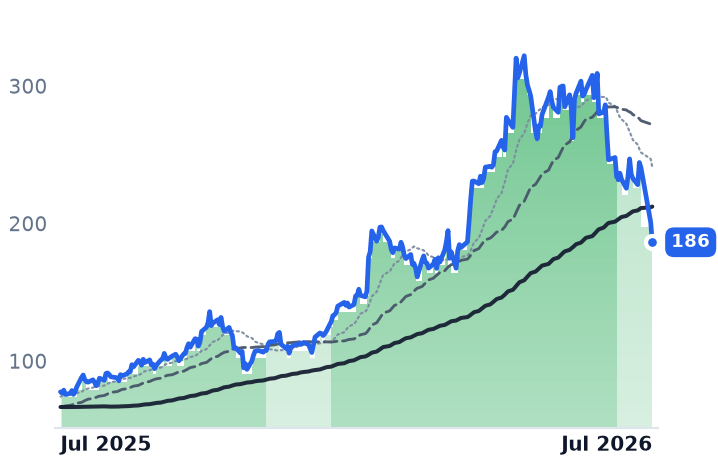
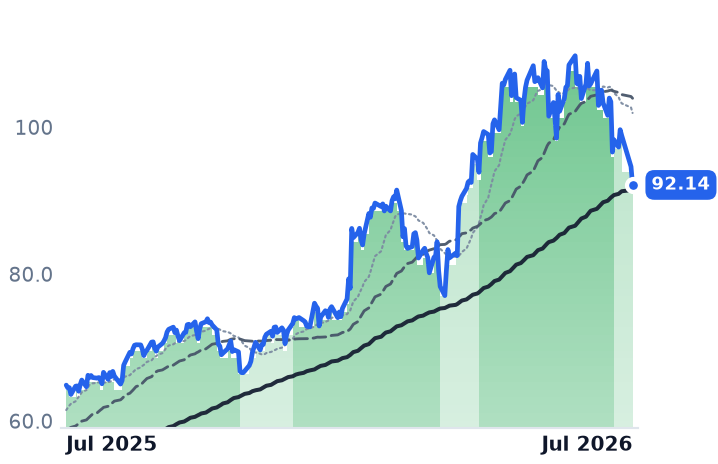
POWL | Powell Industries | Electrical Distribution & Switchgear | 🟢 Cont. Bull | −33.7% | +140.2% |
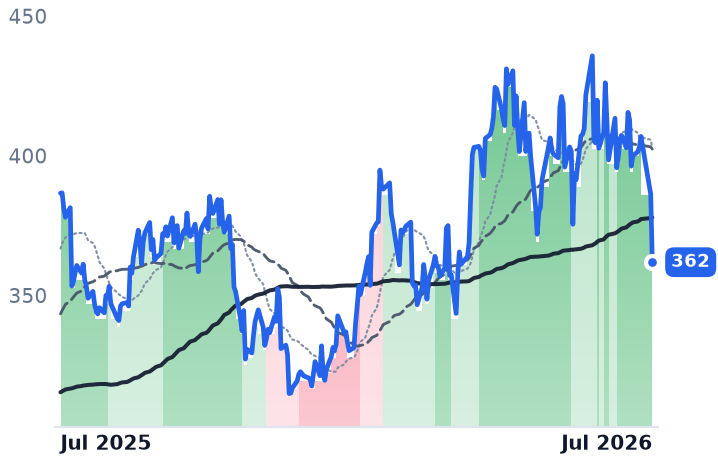
ETN | Eaton | Power & Propulsion Systems | 🟢 Cont. Bull | −11.4% | −6.4% |
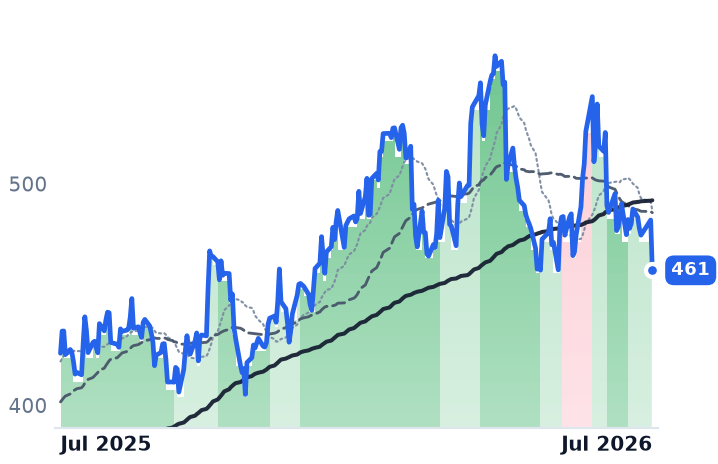
HUBB | Hubbell Incorporated | Electrical Distribution & Switchgear | 🟢 Cont. Bull | −10.4% | +8.8% |
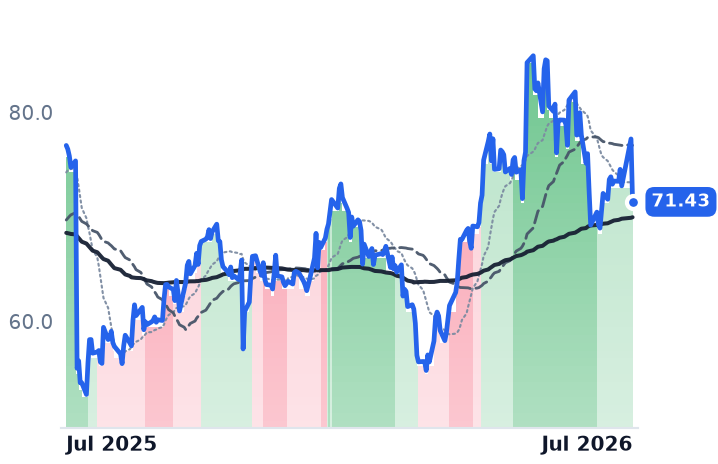
ATKR | Atkore | Electrical Infrastructure Products | 🌱 Emerging Bull | −4.9% | −7.0% |
ABBNY | ABB | Electrical Equipment & Parts | 🟢 Cont. Bull | −13.0% | +42.0% |
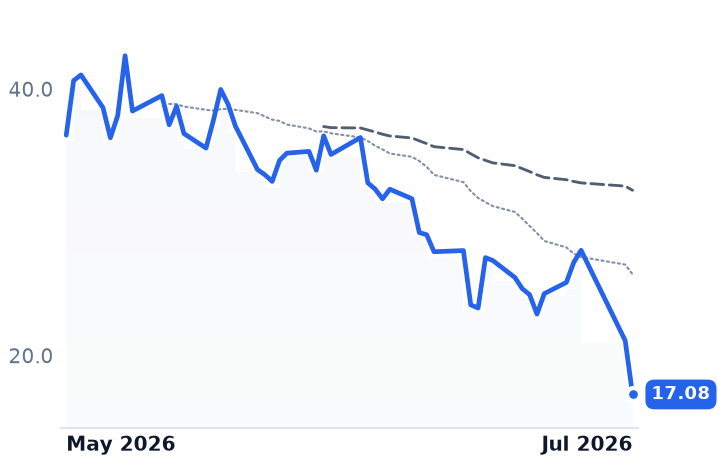
FRVO | Fervo Energy | Emerging & Specialized Energy | 🔴 Cont. Bear | −46.2% | −53.3% |
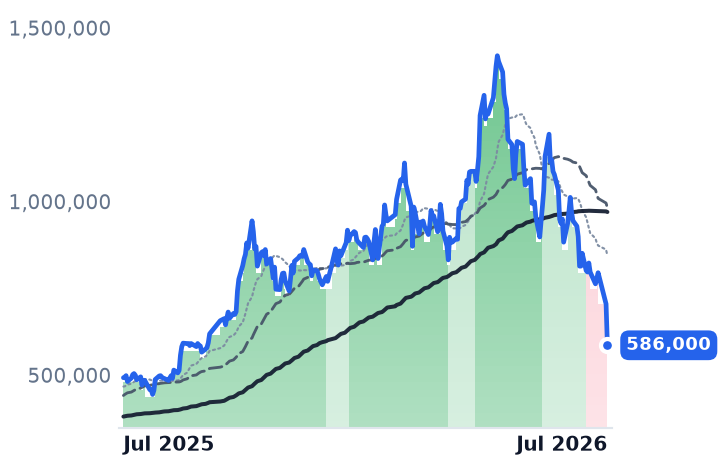
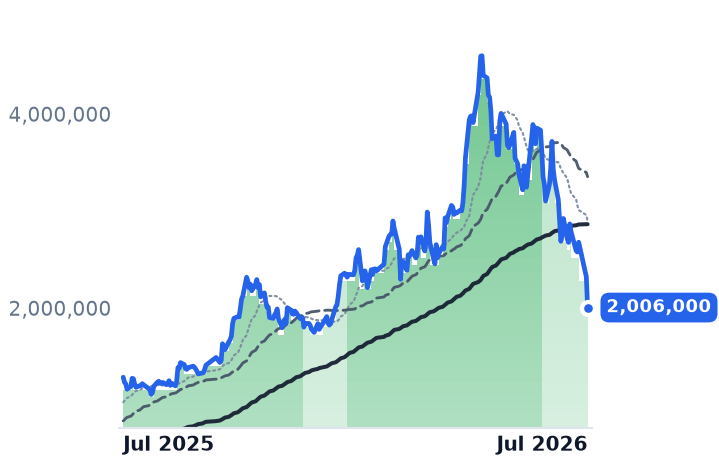
267260.KS | HD Hyundai Electric | Electrical Equipment & Parts | 🟢 Cont. Bull | −37.5% | +19.0% |
298040.KS | Hyosung Heavy Industries | Electrical Equipment & Parts | 🟢 Cont. Bull | −38.7% | +55.8% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
POWL | $7.6B | 39.7x | 38.6x | 6.6x | 6.4x | 21.8x | 21.2x | 28.0x | 3.2% |
ETN | $178.2B | 46.6x | 34.1x | 5.9x | 5.5x | 16.5x | 15.3x | 32.9x | 2.5% |
HUBB | $27.4B | 30.6x | 25.5x | 4.4x | 4.0x | 12.5x | 11.4x | 22.0x | 3.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ATKR | $3.2B | n/m | 16.8x | 1.1x | 1.1x | 5.5x | 5.4x | n/m | 1.8% |
ABBNY | $184.3B | 36.8x | 30.3x | 5.1x | 4.8x | 12.7x | 12.1x | 24.7x | 2.6% |
FRVO | $6.9B | n/m | — | — | — | — | — | n/m | -7.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
267260.KS | $26.6T | 31.3x | 27.7x | 6.1x | 5.6x | 23.7x | 21.8x | 21.8x | 2.8% |
298040.KS | $26.4T | 45.1x | 33.6x | 4.1x | 3.7x | 26.5x | 23.7x | 29.5x | 1.5% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
POWL | Revenue | +8.7% | +22.0% | +13.1% |
| EPS | +12.4% | +21.8% | +31.6% | |
ETN | Revenue | +18.5% | +10.9% | +8.9% |
| EPS | +11.6% | +18.3% | +16.9% | |
HUBB | Revenue | +16.4% | +9.3% | +6.3% |
| EPS | +11.9% | +11.5% | +11.1% | |
ATKR | Revenue | +5.7% | +2.9% | +7.7% |
| EPS | −15.1% | +12.6% | +14.7% | |
ABBNY | Revenue | +13.1% | +11.7% | +10.2% |
| EPS | +31.6% | +9.2% | +14.6% | |
FRVO | Revenue | +4533.3% | +1135.0% | +195.3% |
| EPS | −96.2% | +22.8% | −38.0% | |
267260.KS | Revenue | +16.8% | +19.5% | +15.6% |
| EPS | +36.9% | +28.5% | +22.9% | |
298040.KS | Revenue | +21.9% | +21.3% | +14.8% |
| EPS | +62.0% | +46.8% | +31.2% |
Forward fiscal years only. Blank means no analyst coverage for that year.
What the bands actually show
Of the roughly ten names in this bucket, only two have crossed a trend-band threshold into bear territory in the past 90 days: Hubbell (mildly bullish to mildly bearish on the most recent session) and Korea's Hyundai Electric (mildly bullish to mildly bearish on 2026-07-13). Eaton, Powell Industries, Atkore, ABB, Hyosung Heavy and other Korean industrials remain in bull bands — mostly downshifted from strong to mild intensity, but never breaking bear. Eaton's most recent band reading is still strongly bullish, unchanged all year. That distinction matters: a cohort-wide rollover would show three-plus names flipping bear inside a common window, and that hasn't happened.
Why the two "bear" names flipped
Hubbell's drop followed a Q2 print that actually beat estimates — revenue of $1.71B (+15.3% YoY) and adjusted EPS of $5.52, with full-year guidance raised to $20.25–$20.55 — yet shares still fell roughly 6% as investors focused on margin pressure from tariffs and inflation rather than the beat. That pressure was concentrated in the Electrical Solutions segment, where margins fell 130bps on raw-material and tariff costs, while the Grid Infrastructure segment — the actual data-center/grid exposure — grew about 12% with orders already booking into 2027 and quote volumes roughly double versus two years ago.
Hyundai Electric's slide, alongside Hyosung Heavy's, is characterized by Korean brokerages as macro-driven profit-taking tied to Middle East tensions and rising US yields layered on a prior parabolic run, with explicit commentary that industry fundamentals "have not turned downward." Korea's three major power-equipment makers reportedly booked over 7 trillion won in new orders in Q1 alone, pushing combined backlog past 32 trillion won, and Macquarie has reiterated an Outperform rating on Hyosung.
The capacity story hasn't caught up
The hypothesis's key confirming signal — shortening lead times as new capacity lands — isn't showing up. US transformer lead times remain at 128-144 weeks, 2-4x pre-pandemic norms, with normalization not expected before 2028 despite roughly $2B in announced North American capacity. Input costs, split roughly evenly between copper and grain-oriented electrical steel, remain elevated with only modest stabilization.
Company-specific noise elsewhere
Powell Industries' outsized monthly decline reflects pre-earnings positioning ahead of its August 3 report, following a prior +51% melt-up that had already drawn caution over its rich multiple, as noted in coverage of Powell's larger-than-market drop; its trend band never left bull territory, and knowledge notes still describe roughly $1.8B in backlog. Eaton has not yet reported Q2 (due July 31) and remains strongly bullish, with Q1 electrical backlog up 48% YoY and book-to-bill of 1.2. Atkore is actually up slightly over the month, with Q2 results citing accelerating data-center demand alongside an unrelated legacy PVC-conduit litigation charge. Fervo Energy, a geothermal merchant-power name rather than a switchgear/transformer OEM, is down about a third over the month — likely reflecting the separate merchant-power/data-center-pause dynamic rather than transformer demand.
Taken together, the evidence favors a multiple reset inside an intact structural shortage over a genuine cohort-wide bull-to-bear transition. Eaton's July 31 print and Powell's August 3 report are the near-term data points most likely to arbitrate which reading holds.