

Regional E-Commerce "Bear Flip" Is Really Two Stocks, Not a Cohort
Hypothesis Opus 5 · Research Sonnet 5 · Writing Sonnet 5 · Prompt v1.0
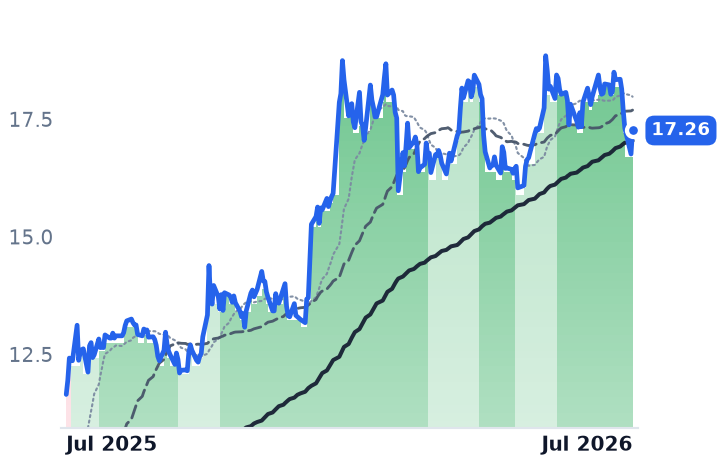
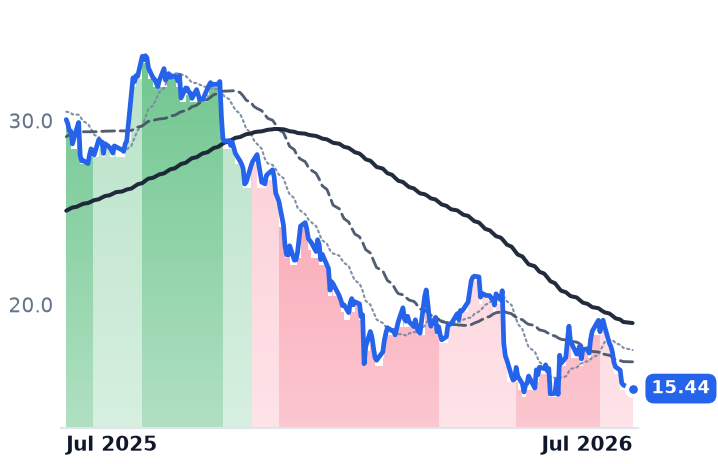
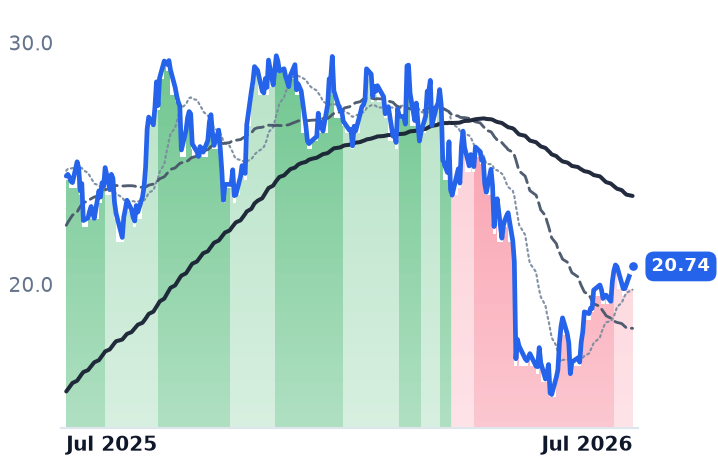
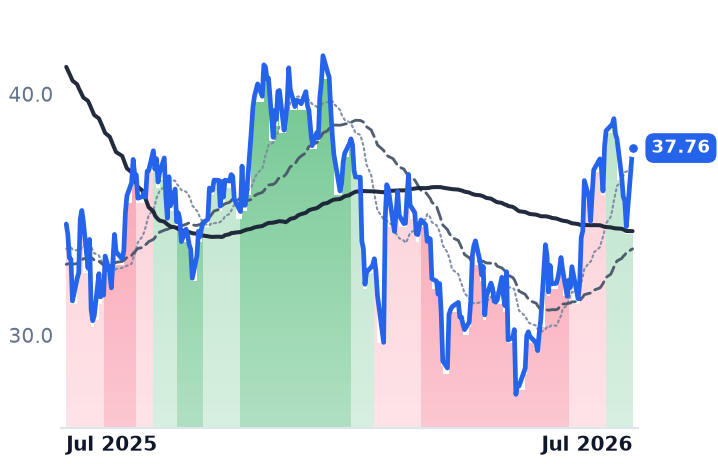
Trend-band data for the nine-name Regional/Niche E-commerce basket shows no synchronized 30-90 day rotation into bear: only EYE and RERE actually flipped from bull to bear in that window, MNSO and CPNG have been bear-banded for six-plus months, and BWMX, HZO and LQDT remain outright bullish, up 37-67% year over year.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
BWMX | Betterware de México, S.A.P.I. de C.V | Regional/Niche E-commerce | 🟢 Cont. Bull | −5.0% | +48.2% |
CPNG | Coupang | Regional/Niche E-commerce | 🔴 Cont. Bear | −12.2% | −48.6% |
EYE | National Vision | Regional/Niche E-commerce | ⚠️ Emerging Bear | — | — |
GLBE | Global-e Online | Regional/Niche E-commerce | ⚠️ Emerging Bear | — | — |
HZO | MarineMax | Regional/Niche E-commerce | 🟢 Cont. Bull | — | — |
LQDT | Liquidity Services | Regional/Niche E-commerce | 🟢 Cont. Bull | — | — |
MNSO | MINISO | Regional/Niche E-commerce | 🔴 Cont. Bear | — | — |
RERE | ATRenew | Regional/Niche E-commerce | ⚠️ Emerging Bear | — | — |
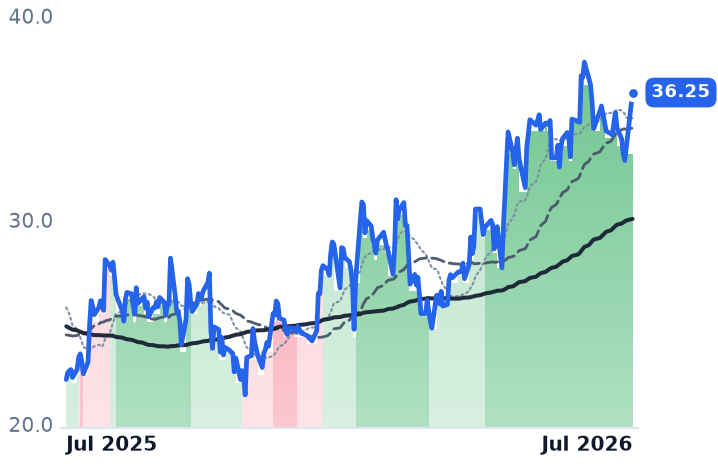
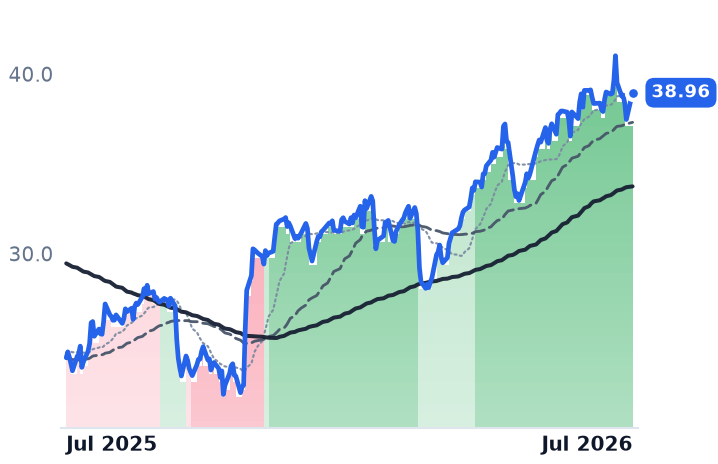
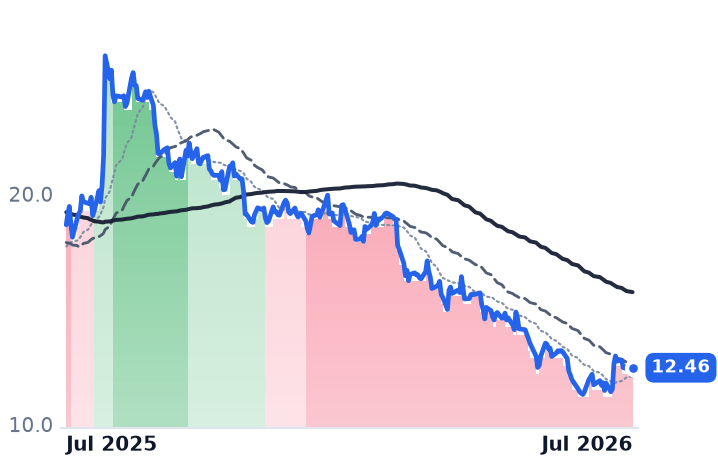
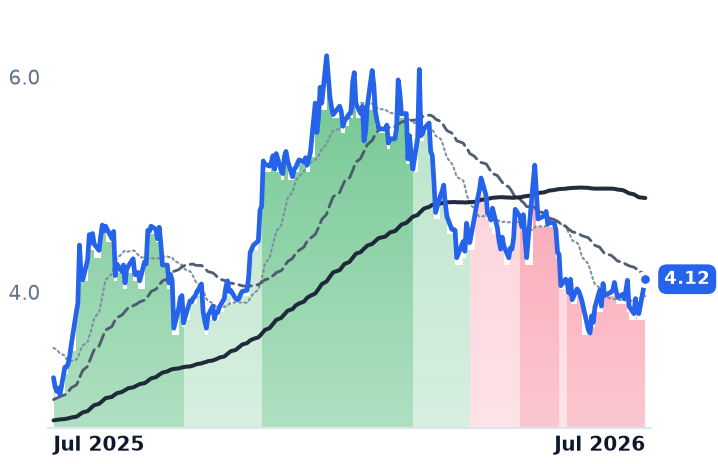
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BWMX | $598.6M | 1.8x | — | 0.1x | — | 0.2x | — | 1.1x | 13.3% |
CPNG | $29.3B | n/m | — | 0.8x | 0.8x | 2.9x | 2.7x | 38.4x | 1.0% |
EYE | $1.4B | 29.8x | 18.0x | 0.7x | 0.7x | 1.3x | 1.2x | 11.9x | 7.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
GLBE | $4.7B | 40.3x | 24.5x | 4.6x | 3.8x | 10.1x | 8.3x | 31.2x | 6.2% |
HZO | $727.4M | n/m | 45.2x | 0.3x | 0.3x | 1.0x | 1.0x | 16.2x | 23.3% |
LQDT | $1.0B | 33.6x | 22.3x | 2.1x | 4.5x | 4.7x | 9.8x | 16.3x | 7.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MNSO | $4.4B | 23.5x | — | 1.4x | — | 3.1x | — | 10.2x | 0.0% |
RERE | $1.6B | 31.9x | — | 0.5x | — | 2.8x | — | 17.8x | 0.0% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
BWMX | Revenue | +19.7% | +14.5% | +13.6% |
| EPS | +16.6% | +29.8% | +17.3% | |
CPNG | Revenue | +6.8% | +14.5% | +11.2% |
| EPS | −276.9% | −221.2% | +113.7% | |
EYE | Revenue | +8.5% | +4.5% | +6.0% |
| EPS | +34.1% | +38.3% | +22.2% | |
GLBE | Revenue | +31.2% | +24.7% | +25.2% |
| EPS | +225.3% | +36.3% | +41.2% | |
HZO | Revenue | −0.1% | +4.7% | +4.0% |
| EPS | −7.0% | +118.2% | +55.9% | |
LQDT | Revenue | −50.0% | +9.4% | — |
| EPS | +10.4% | +12.5% | — | |
MNSO | Revenue | +19.6% | +17.4% | +13.6% |
| EPS | +19.0% | +17.0% | +16.4% | |
RERE | Revenue | +26.9% | +21.5% | +22.6% |
| EPS | +89.7% | +36.9% | +16.5% |
Forward fiscal years only. Blank means no analyst coverage for that year.
What the bands actually show
Across the eight tracked names — BWMX, CPNG, EYE, GLBE, HZO, LQDT, MNSO, RERE — the trend-band history does not support a coherent 30-90 day rotation into bear territory. Only EYE (mildly bullish to mildly bearish on April 2, strongly bearish by April 16) and RERE (mildly bullish to mildly bearish April 10, strongly bearish by May 11) show a genuine bull-to-bear flip inside that window. GLBE's flip happened back in February, roughly 90-plus days before its most recent data point, and its price actually round-tripped — rallying from $28.64 to $33.30 in early-to-mid April before drifting back to $28.63 — even as its band stayed pinned in strongly bearish, a sign the moving-average band lags real price action. MNSO and CPNG, meanwhile, were already sitting in bear bands as far back as early February and simply stayed there — a persistent multi-month regime, not a fresh transition. And BWMX, HZO and LQDT remain in mild or strong bull bands, up 37% to 67% year over year, directly at odds with a cohort-wide bearish framing.
The catalysts don't line up as a shared shock
Real cross-border tariff catalysts do exist. The US de minimis exemption was eliminated for China and Hong Kong in May 2025 and fully ended for all countries by February 2026, while the EU introduced a flat €3 parcel customs fee effective July 1, 2026. But these dates mostly predate or postdate the actual band-transition dates seen in the data, undercutting the idea of one shared 30-90 day trigger. GLBE's roughly 30% earlier-2026 drawdown tied to tariff uncertainty had already recovered about 11% over the trailing month by late July. CPNG's decline looks name-specific: a Q1 loss, data-breach fallout, and Korean Fair Trade Commission scrutiny drove the drop, and sell-side consensus there remains a Buy with a price target implying over 40% upside — not a market treating this as a completed value re-rating. EYE's ~19% single-day gap came on a print that reiterated full-year guidance rather than cutting it, suggesting analyst skepticism more than a fundamental break. MNSO's own quarter delivered 28.5% revenue growth that beat guidance, even as its stock sits in a strongly bearish band.
Data caveat
Seven of the eight tickers' local price history is stale as of mid-May, roughly ten weeks behind today; only CPNG has data through the current date, where it ground from a $19.15 early-July peak down to $15.44. That grind is real but can't be generalized to the rest of the basket without fresher data.