

Sable's collapse is a one-day dilution event, not a permitting de-rating
Prompt v1.0
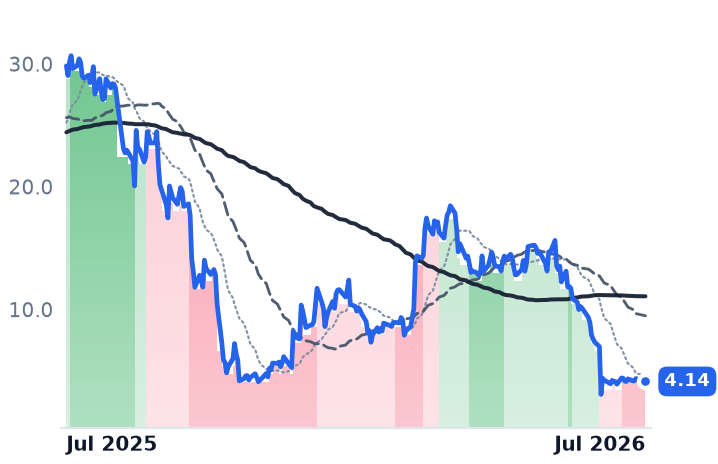
SOC's -70% three-month slide is not a gradual grind across a permitting-constrained oil cohort — it is a single -55.8% session on 30 June triggered by a dilutive financing package, after which the stock has been flat. The California and Gulf peers were in bull bands, and the regulatory regime is loosening, not tightening.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
SOC | Sable Offshore | Oil & Gas Production | 🔴 Cont. Bear | −40.6% | −86.1% |
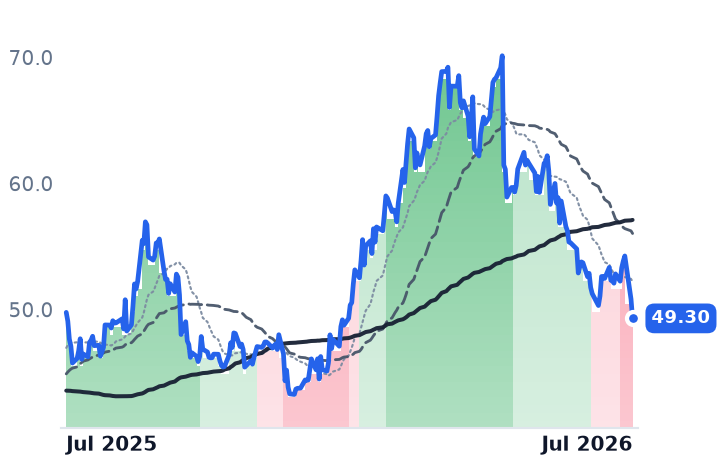
CRC | California Resources | Other | ⚠️ Emerging Bear | −6.3% | −1.0% |
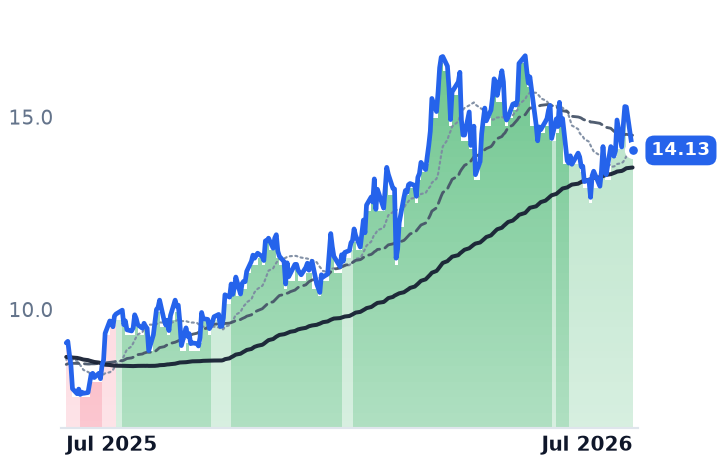
TALO | Talos Energy | International & Offshore | 🟢 Cont. Bull | — | — |
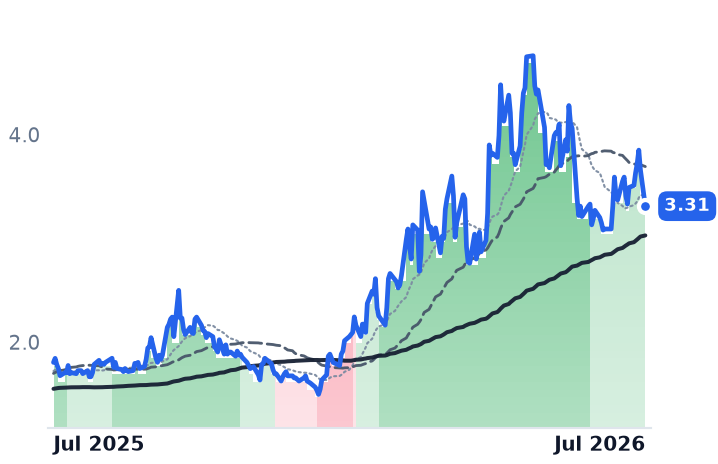
WTI | W&T Offshore | International & Offshore | 🟢 Cont. Bull | — | — |
MUR | Murphy Oil | Early-Stage & Exploration | 🟢 Cont. Bull | — | — |
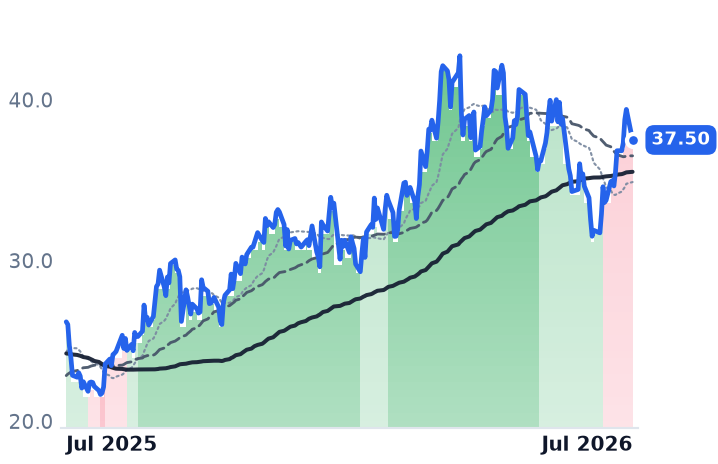
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SOC | $1.5B | n/m | 11.5x | — | 1.6x | — | — | n/m | -42.0% |
CRC | $5.4B | n/m | 10.9x | 1.5x | 1.4x | 4.1x | 3.8x | 5.0x | 7.2% |
TALO | $2.7B | n/m | 164.9x | 1.6x | 1.4x | 23.1x | 20.1x | 4.7x | 12.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
WTI | $706.7M | n/m | — | 1.4x | 1.2x | 5.1x | 4.6x | 8.8x | 6.7% |
MUR | $5.8B | 69.1x | 11.1x | 2.1x | 1.8x | 3.0x | 2.6x | 5.9x | 3.1% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
SOC | Revenue | +10057.7% | +30.8% | +1.7% |
| EPS | −130.4% | +102.0% | +15.0% | |
CRC | Revenue | +13.1% | −1.0% | +6.3% |
| EPS | +36.0% | −23.3% | +48.7% | |
TALO | Revenue | +10.0% | −6.3% | −0.2% |
| EPS | −110.1% | −249.8% | −30.8% | |
WTI | Revenue | +13.8% | −5.9% | +1.3% |
| EPS | −93.9% | +233.3% | −25.0% | |
MUR | Revenue | +16.9% | −2.8% | +3.8% |
| EPS | +212.0% | −2.6% | +11.1% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The move was one session, not a trend
Sable Offshore's three-month chart looks like a slow bleed: $14.67 on 22 April to $4.38 on 22 July, -70.1%, with a -53.3% one-month leg. The daily data says otherwise. On 2026-06-30 SOC closed at $3.08 versus $6.97 the prior session — a -55.8% single-day crash on 97.1 million shares against a typical June volume of roughly 3-5 million. Since then the stock has gone nowhere: $4.40 on 1 July, $4.38 on 22 July, -0.5% over three weeks.
The trigger was balance-sheet, not regulatory. Sable announced $100 million of common stock and $300 million of convertible senior notes due 2031, alongside a senior secured term loan of up to $1 billion to refinance the ExxonMobil seller note. That sits on top of a Q1 2026 print of $1.27 million revenue against a -$118.8 million operating loss, following a 2025 with zero revenue and a -$408.3 million operating loss. Jefferies subsequently cut its target to $11 from $24 on costs — still far above the $4.38 close, so the name trades below, not above, the sell-side.
Nothing broke early, and nothing broke together
SOC was in bull bands right up to the crash: mildly bullish from 30 April, briefly strongly bullish in early June, still mildly bullish on 26 June. It entered mildly bearish on 29 June and strongly bearish only on 13 July. There is no months-ahead lead on a cohort. The peers, through the desk's last local data on 2026-05-19, were in bull bands — MUR strongly bullish since 20 February, TALO since 28 January, WTI since 13 February — with CRC +5.2%, MUR +18.4%, TALO +21.2% and WTI +81.7% over the prior three months.
The permitting frame is inverted
California's SB 237 opens the way for up to 2,000 new Kern County drilling permits a year — passed partly to offset Phillips 66's 147,000 b/d Los Angeles closure and Valero's 145,000 b/d Benicia shutdown. CRC is already receiving 2026 permits and raised its adjusted EBITDAX midpoint 42% to $1,450 million, while Beacon's 275MW Golden Valley hub advances on Elk Hills. BRY is not a peer at all — CRC closed the $717 million all-stock acquisition on 18 December 2025. Offshore, BOEM has scheduled Big Beautiful Gulf 3 for 12 August across 80.4 million acres at a 12.5% royalty.
Sable itself got federal restart approval for Lines CA-324 and CA-325 and a Las Flores Canyon victory lap; the live overhang is California's 9th Circuit challenge to the June 25 special permit, i.e. litigation over a granted waiver. Management still targets ~62,000 gross Boe/d by 2027.
Context
Crude is up more than 50% year-to-date on the Middle East conflict, Brent near $84-86. CRC has cooled to around $54 from $62 — a normal pullback from a much higher base. The desk's own May analysis already flagged SOC as a binary, undercapitalised single-asset story. That framing held.