

The whole listed space complex left its bull bands in eight sessions
Prompt v1.0
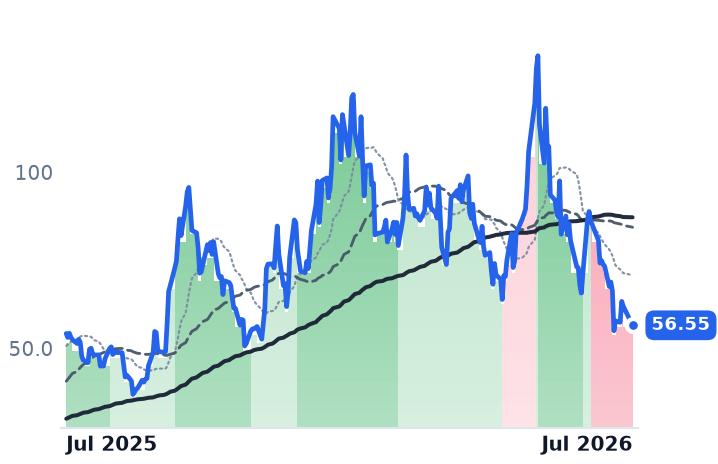
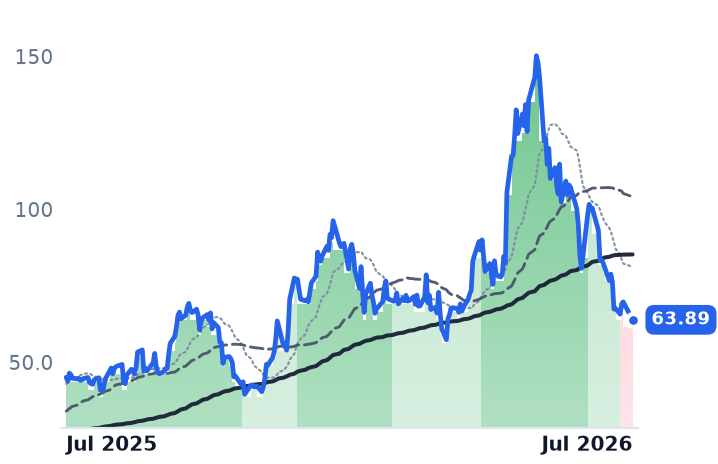
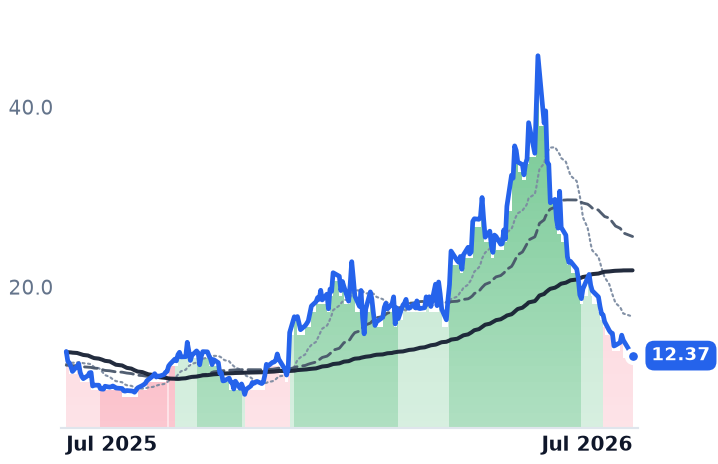
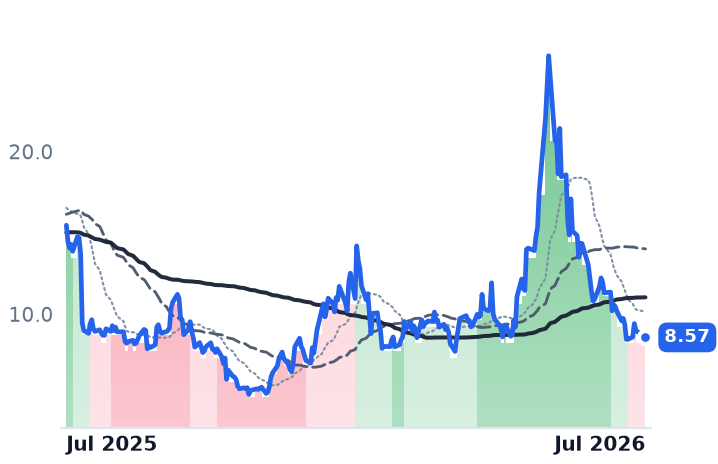
Every name in the commercial space/EO cohort — PL, BKSY, SATL, SPIR, ASTS, RKLB, LUNR, RDW — exited strongly bullish inside an eight-session window in late June 2026 and flipped to bear bands in July, all now below their 200-day averages and 53–69% off 52-week highs. But SPIR is the laggard in that sequence, not the leading edge, and the driver looks like a post-SpaceX-IPO supply and multiple reset rather than an earth-observation demand break: PL, BKSY and SATL all raised or accelerated guidance into the drawdown.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
SPIR | Spire Global | Specialized Services | 🌱 Emerging Bull | −35.6% | +7.8% |
PL | Planet Labs PBC | Unmanned Systems & ISR | 🟢 Cont. Bull | −34.7% | +221.1% |
BKSY | BlackSky Technology | Specialty Manufacturing & Components | 🟢 Cont. Bull | −22.6% | +14.6% |
SATL | Satellogic | Specialty Manufacturing & Components | 🌱 Emerging Bull | −37.4% | −0.6% |
ASTS | AST SpaceMobile | Satellite & Broadband Services | ⚠️ Emerging Bear | −34.8% | +4.3% |
RKLB | Rocket Lab USA | Unmanned Systems & ISR | 🟢 Cont. Bull | −34.8% | +41.6% |
LUNR | Intuitive Machines | Space Systems & Launch | 🟢 Cont. Bull | −41.0% | −3.6% |
RDW | Redwire | Space Systems & Launch | 🌱 Emerging Bull | −26.7% | −44.6% |
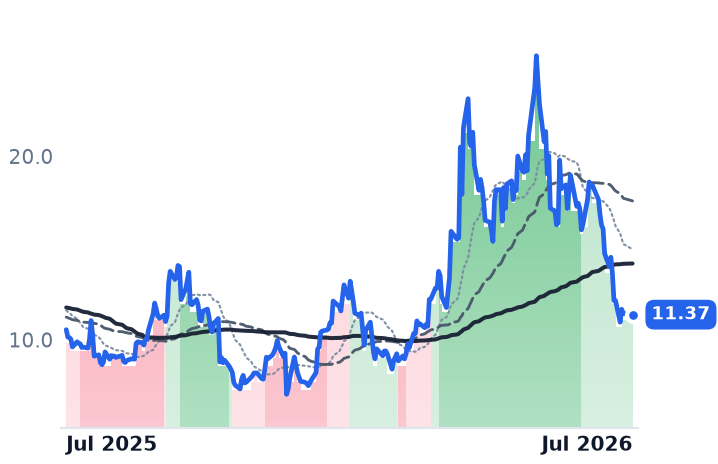
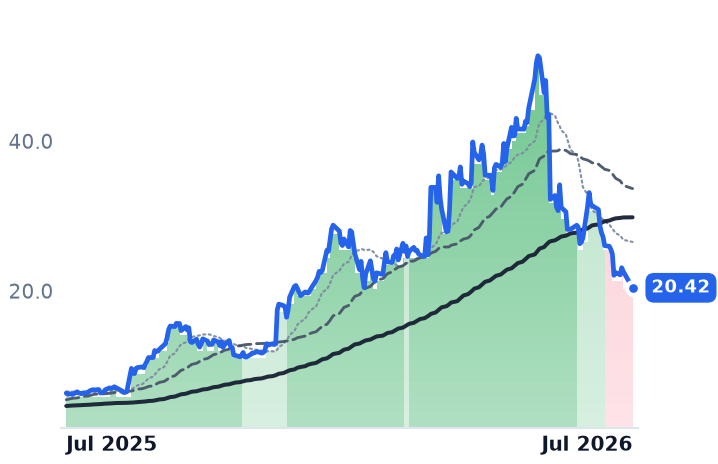
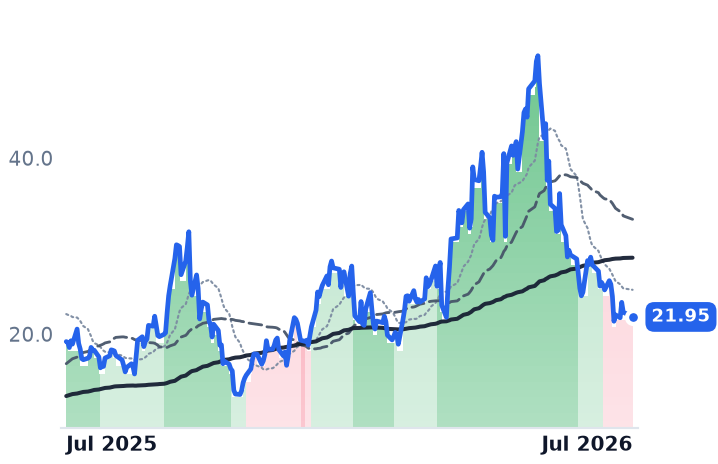
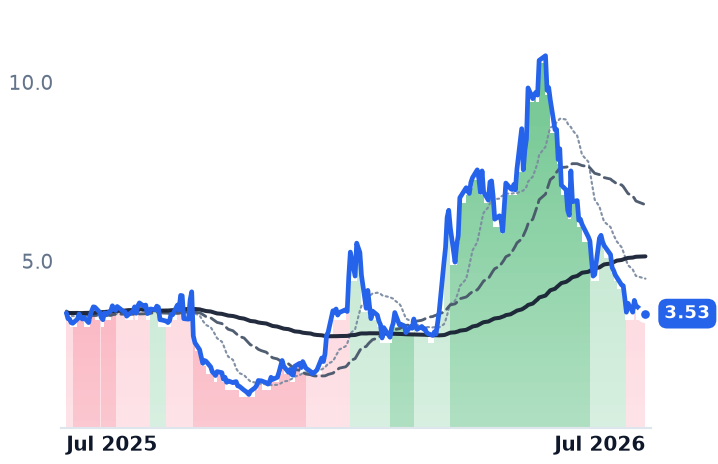
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SPIR | $453.9M | n/m | — | 7.3x | 5.7x | 19.3x | 15.1x | n/m | -23.9% |
PL | $8.2B | n/m | — | 24.5x | 18.8x | 44.1x | 34.0x | n/m | 0.6% |
BKSY | $1.3B | n/m | — | 11.6x | 9.2x | 28.7x | 22.9x | n/m | -5.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SATL | $798.4M | n/m | — | 25.0x | 18.2x | 31.7x | 23.0x | n/m | -5.3% |
ASTS | $29.1B | n/m | — | 252.4x | 183.2x | — | — | n/m | -5.6% |
RKLB | $72.2B | n/m | — | 106.3x | 79.7x | 290.7x | 218.0x | n/m | -0.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
LUNR | $5.4B | n/m | — | 16.2x | 5.7x | 62.9x | 22.3x | n/m | -2.5% |
RDW | $2.1B | n/m | — | 5.7x | 4.5x | 62.0x | 49.0x | n/m | -7.4% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
SPIR | Revenue | +12.2% | +22.4% | — |
| EPS | −42.0% | −55.4% | — | |
PL | Revenue | +21.9% | +46.2% | +30.7% |
| EPS | −56.0% | +25.8% | −78.2% | |
BKSY | Revenue | +26.3% | +32.7% | +36.4% |
| EPS | −34.1% | −59.2% | −140.7% | |
SATL | Revenue | +186.7% | +39.1% | +47.4% |
| EPS | +192.5% | −93.6% | −25.0% | |
ASTS | Revenue | +172.1% | +330.7% | +167.9% |
| EPS | +37.1% | −48.4% | −180.2% | |
RKLB | Revenue | +51.0% | +39.0% | +27.0% |
| EPS | −41.8% | −100.1% | +68844.3% | |
LUNR | Revenue | +329.6% | +21.3% | +23.6% |
| EPS | −29.4% | −117.9% | +736.8% | |
RDW | Revenue | +42.8% | +20.3% | +17.6% |
| EPS | −56.0% | −34.2% | −50.9% |
Forward fiscal years only. Blank means no analyst coverage for that year.
An eight-session cohort break
The band transitions are unusually tightly clustered. PL left strongly bullish on 6/22, BKSY and SATL on 6/23, LUNR and SPIR on 6/25, ASTS on 6/26, RKLB on 6/29, RDW on 7/6. July did the second leg: BKSY and LUNR to bear on 7/9, PL 7/10, SATL 7/16, RDW 7/17, RKLB 7/20, with ASTS skipping straight to strongly bearish on 7/1. All eight sit below their 200-day averages (ASTS -25.6%, LUNR -26.3%, BKSY -15.5%) and 53–69% below 52-week highs. Three-month declines run from RKLB -22.5% to LUNR -52.9%.
SPIR's -35.2% month was a grind, not a crash: 12 near-consecutive down sessions from 18.44 on 7/2 to 10.96 on 7/20, worst days near -8%, no gap-down volume spike. As of 7/22 SPIR was still tagged mildly bullish while six peers had already flipped. It is following the cohort, not leading it.
The catalyst is security supply, not demand
The cleanest explanation is that SpaceX's June IPO removed the scarcity premium that made listed names proxies for space exposure — and then SpaceX itself broke, closing at $131.11, 42% below its June 16 high and under its $135 IPO price, with a first lockup on August 6 releasing ~911.5M insider shares. One reversal map frames July as four layers: a vertical run, the scarcity unwind, a converts/ATM/insider-sale supply cluster, and ETF-driven liquidation. The dilution leg is visible: ASTS fell 17% on July 16 on a $1B+ convertible, and Planet's CEO and co-founder sold 289,593 shares on July 10 under 10b5-1 plans.
Fundamentals went the other way
Planet posted record $94M revenue, +42% YoY, backlog ~$906M and guided FY27 to $425–441M. BlackSky raised FY26 guidance to $130–150M; Satellogic grew revenue 80% YoY. Spire beat guidance at $15.8M and reaffirmed $75–85M, is debt-free after a $65.5M April placement, and had no July shock beyond a 10-satellite launch and a new CCO; its 2023–24 restatement is a 2025 overhang.
The budget-mix asymmetry
Commercial EO data buys keep arriving but small: ~$70M of NGA Luno awards on July 2 and a $22M Luno B option for Planet, while $1.75B went to L3Harris/Sierra for 36 missile-warning satellites, inside ~$19B of Golden Dome awards and $3.2B for space-based interceptors — none to this cohort. Spire's NOAA line is smaller still: $35.5M of RODB-2 awards against a program that started at $5M in FY2020.
What hasn't reset
The sell side. RKLB is 58% off its high with an average target 79% above spot even after an 8.7% session on July 24, and SPIR's consensus target sits ~38% above spot. The market is doing the de-rating; published fair values still lag. This desk's May notes flagged exactly that gap — RKLB at P/S 75, ASTS at P/S 387.