

AI component drawdown is a multiple unwind, not a broken trend
Prompt v1.0
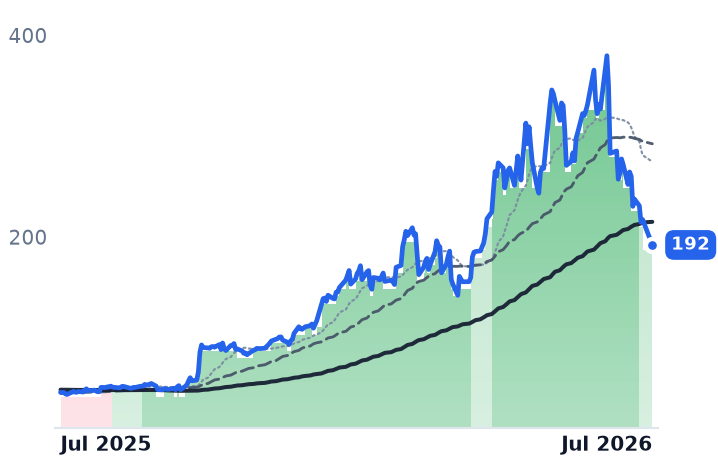
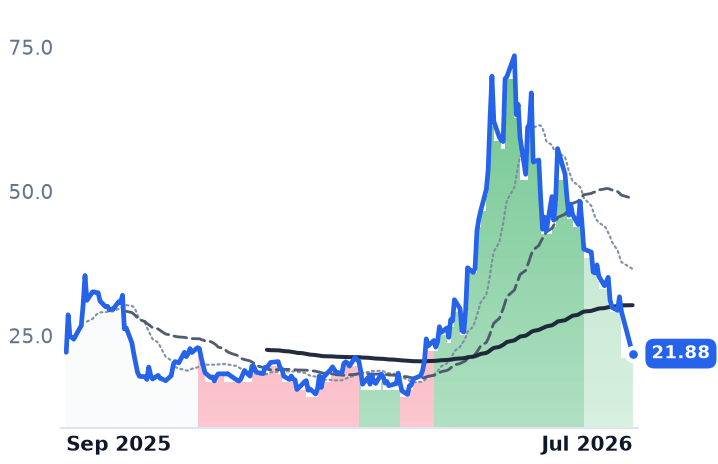
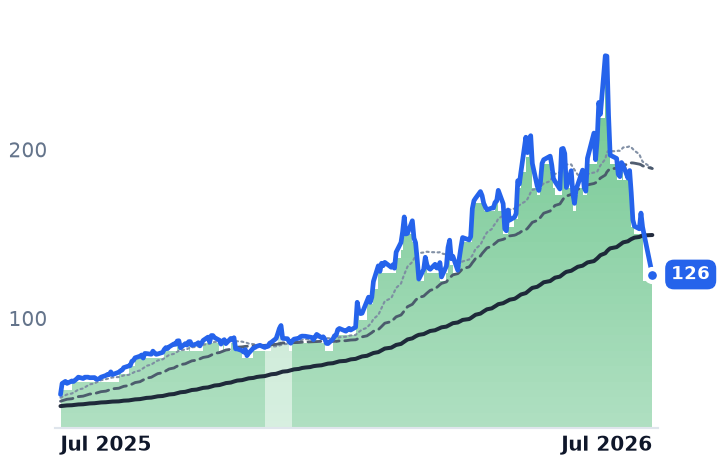
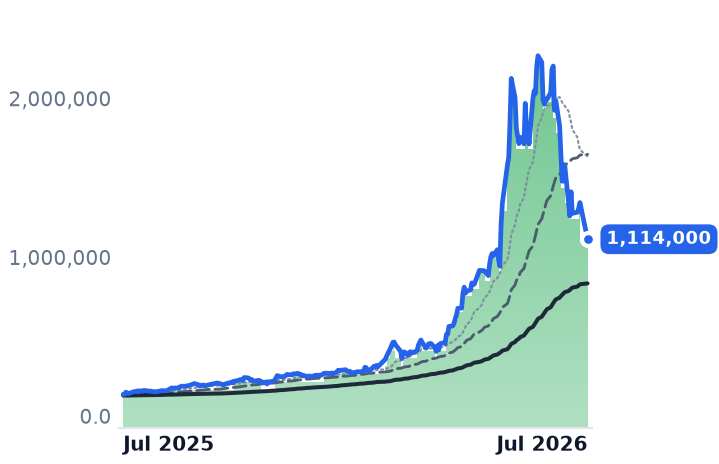
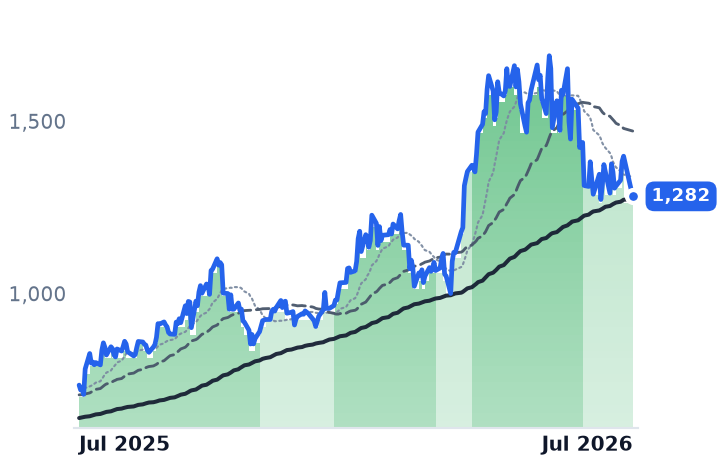
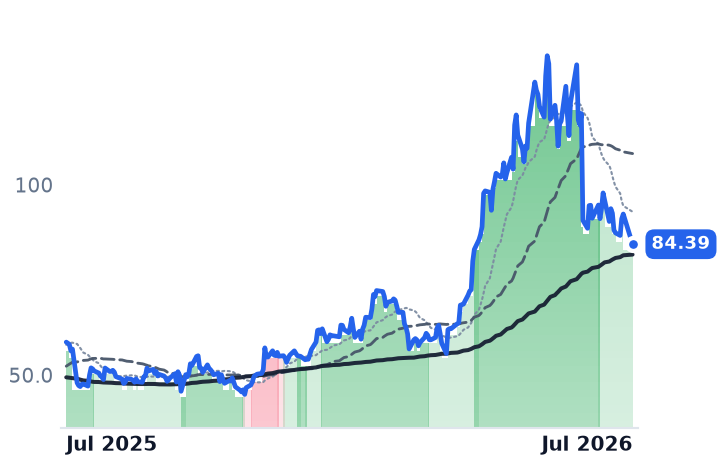
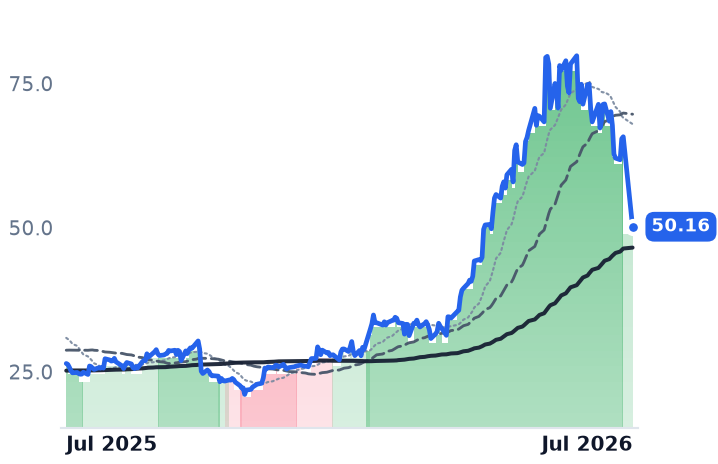
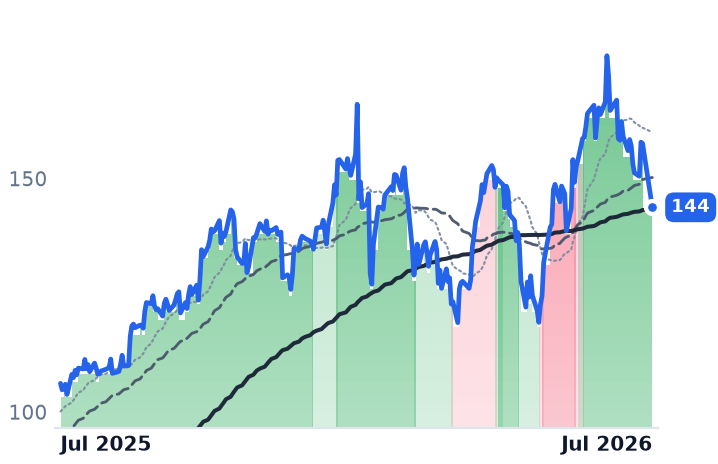
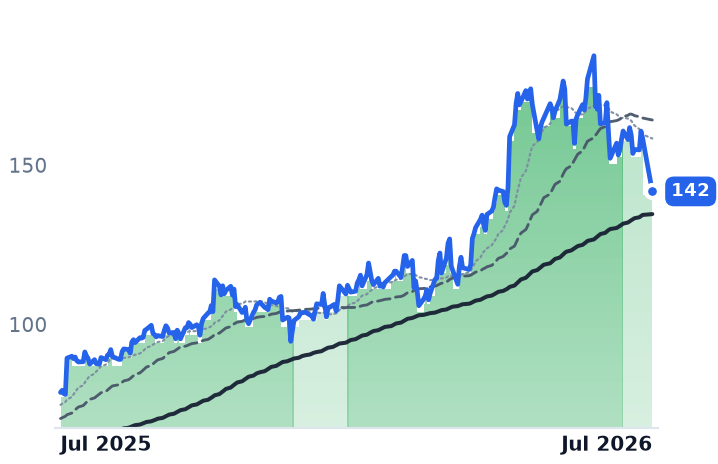
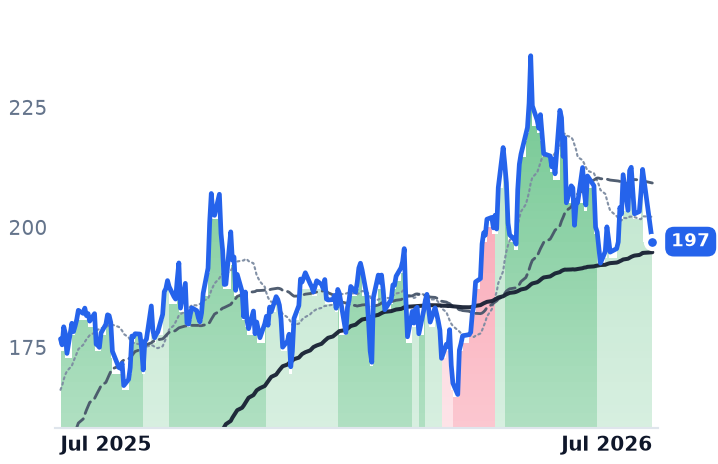
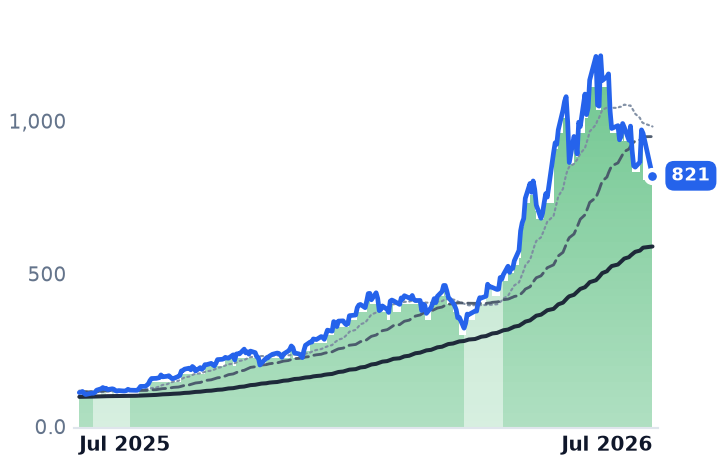
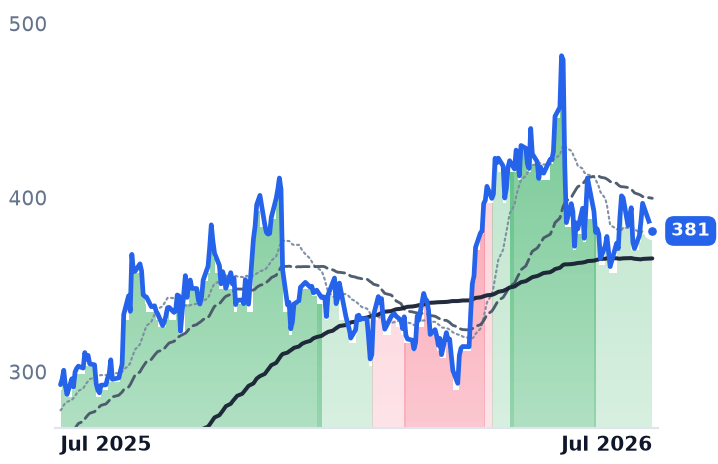
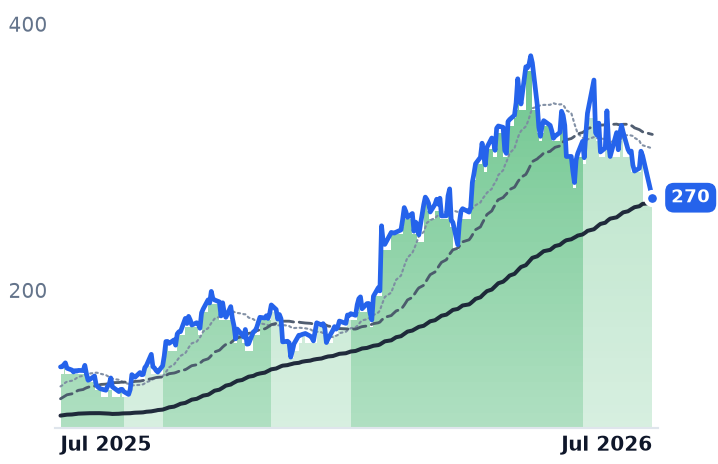
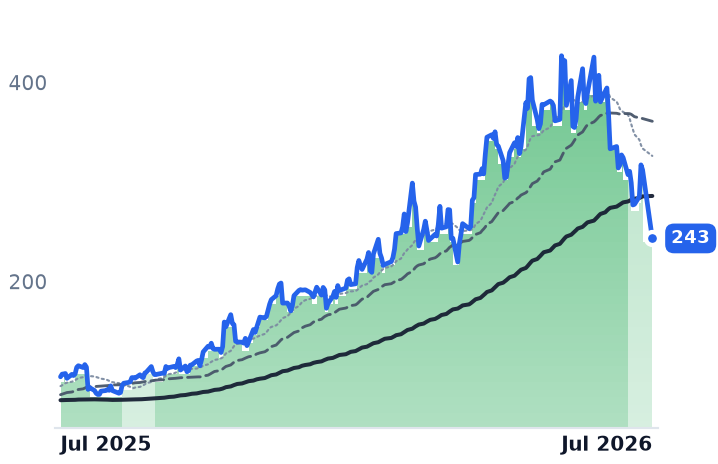
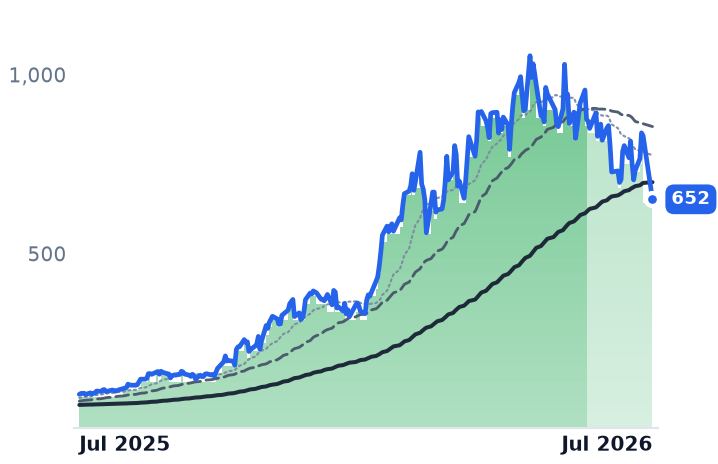
Vicor, Wolfspeed, Corning and Samsung Electro-Mechanics are down 40-60% from May-June peaks, but band data shows GLW and 009150.KS still in unbroken strongly bullish, VICR only slipping to mildly bullish on 20 July, and all four above their 200-day averages. Two of the scariest corroborating declines — Mueller -54% and KLA -88% — are stock-split artifacts.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
VICR | Vicor | Power Conversion & Control | 🟢 Cont. Bull | −47.6% | +317.9% |
WOLF | Wolfspeed | Analog & Power Management | 🟢 Cont. Bull | −50.5% | −1.0% |
GLW | Corning | Connectors & Substrates | 🟢 Cont. Bull | −50.7% | +129.5% |
MLI | Mueller Industries | HVAC & Plumbing Systems | 🟢 Cont. Bull | +8.3% | −23.7% |
009150.KS | Samsung Electro-Mechanics | Hardware, Equipment & Parts | 🟢 Cont. Bull | −45.3% | +711.7% |
MPWR | Monolithic Power Systems | Analog & Power Management | 🟢 Cont. Bull | −2.2% | +74.5% |
ON | ON Semiconductor | Analog & Power Management | 🟢 Cont. Bull | −4.7% | +43.9% |
STM | STMicroelectronics | Processors & Accelerators | 🟢 Cont. Bull | −32.9% | +89.7% |
APH | Amphenol | Connectors & Substrates | 🟢 Cont. Bull | −13.6% | +35.5% |
NVT | nVent Electric | Power Distribution Systems | 🟢 Cont. Bull | −13.2% | +80.2% |
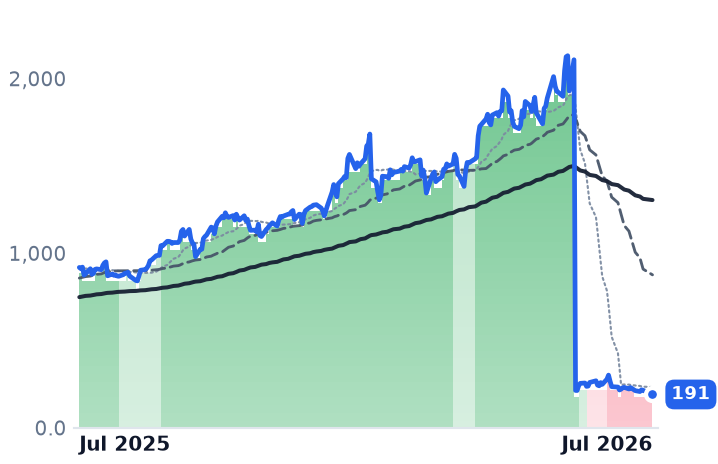
KLAC | KLA | Fabrication Equipment & Materials | ⚠️ Emerging Bear | −31.5% | −79.2% |
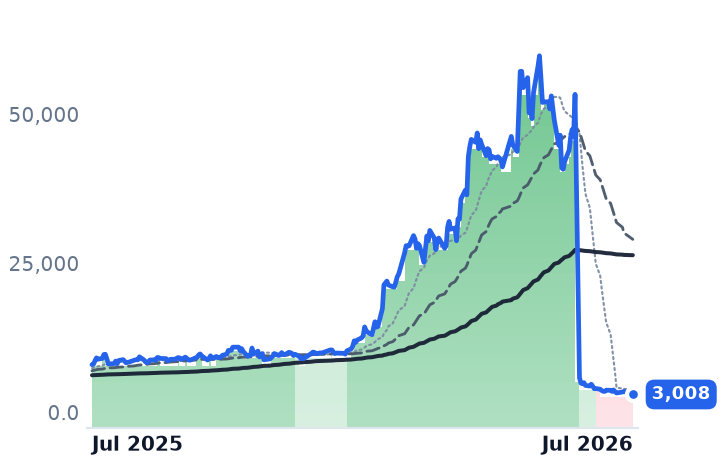
5801.T | Furukawa Electric | Electrical Equipment & Parts | 🟢 Cont. Bull | −31.9% | −62.4% |
NVDA | NVIDIA | Processors & Accelerators | 🟢 Cont. Bull | +1.0% | +11.5% |
MU | Micron Technology | Memory & Storage | 🟢 Cont. Bull | −28.3% | +638.6% |
AVGO | Broadcom | Data Center & Networking | 🟢 Cont. Bull | +2.3% | +30.2% |
VRT | Vertiv | Advanced Power Systems | 🟢 Cont. Bull | −12.2% | +89.3% |
COHR | Coherent | Photonics & Optics | 🟢 Cont. Bull | −37.8% | +133.3% |
LITE | Lumentum | Optical Networking | 🟢 Cont. Bull | −23.4% | +508.3% |
ANET | Arista Networks | Cloud Networking | 🟢 Cont. Bull | +3.4% | +44.4% |
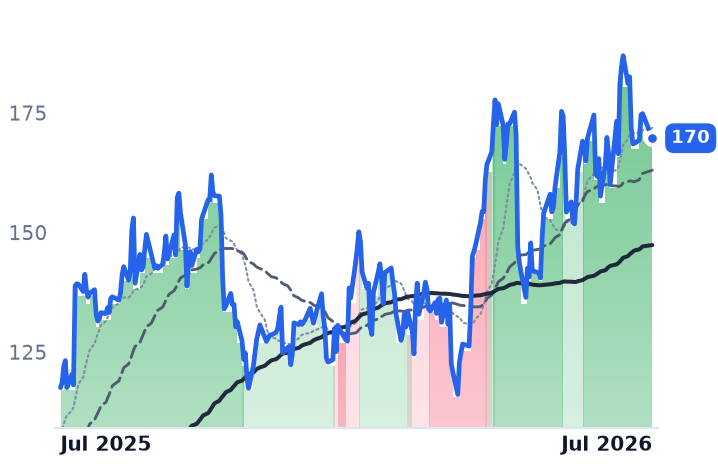
ETN | Eaton | Power Distribution Systems | 🟢 Cont. Bull | −5.4% | −0.8% |
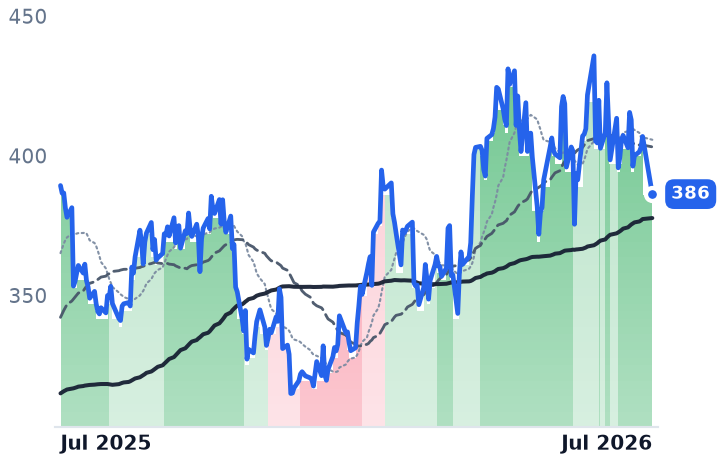
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | −0.0% | +17.3% |
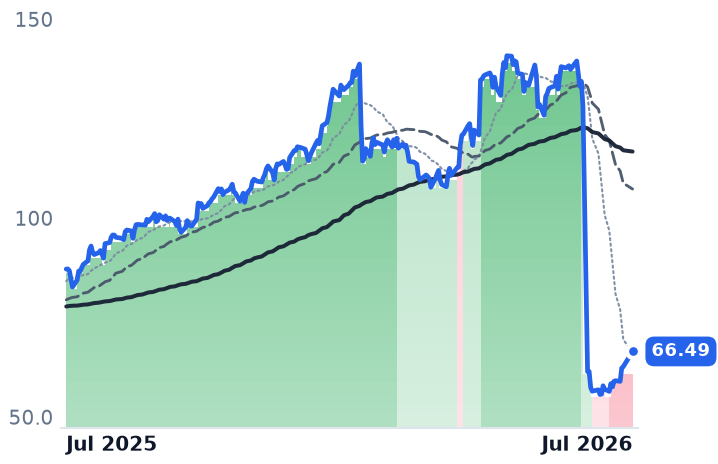
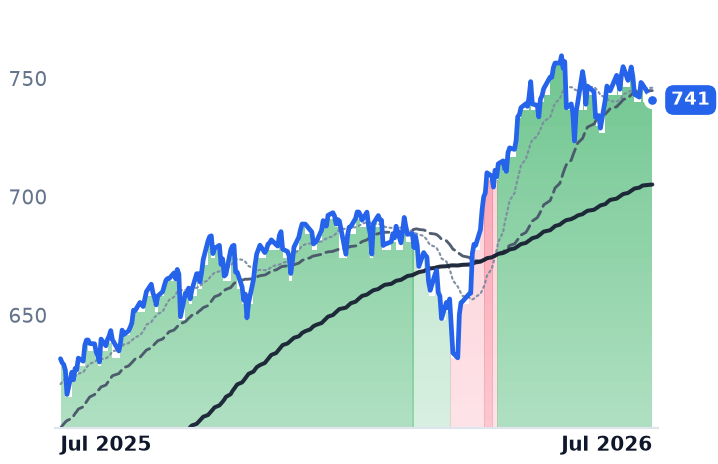
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
VICR | $11.1B | 76.9x | 62.3x | 23.5x | 17.5x | 41.4x | 31.0x | 80.3x | 0.5% |
WOLF | $1.8B | n/m | — | 2.8x | 2.9x | — | — | n/m | -19.3% |
GLW | $116.2B | 61.1x | 41.0x | 6.9x | 6.0x | 18.9x | 16.6x | 29.0x | 2.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MLI | $14.1B | 16.3x | 15.3x | 3.0x | 2.8x | 11.1x | 10.2x | 10.6x | 2.7% |
009150.KS | $100.8T | 104.9x | 68.5x | 8.1x | 7.1x | 40.0x | 34.9x | 46.4x | 0.4% |
MPWR | $68.1B | 84.5x | 50.5x | 20.8x | 16.4x | 37.7x | 29.7x | 64.3x | 0.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ON | $33.0B | 53.7x | 26.5x | 5.3x | 5.0x | 14.2x | 13.5x | 26.9x | 5.4% |
STM | $49.8B | 107.2x | 41.7x | 3.7x | 3.5x | 10.9x | 10.1x | 22.5x | 0.8% |
APH | $214.4B | 41.4x | 32.7x | 7.4x | 6.0x | 19.2x | 15.7x | 24.4x | 2.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NVT | $27.4B | 46.0x | 33.0x | 5.7x | 5.0x | 15.3x | 13.6x | 28.6x | 2.1% |
KLAC | $268.8B | 55.9x | 37.5x | 19.8x | 14.8x | 32.3x | 24.2x | 47.4x | 1.4% |
5801.T | $2.3T | 25.1x | 19.4x | 1.6x | 1.5x | 9.1x | 8.1x | 14.7x | 0.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NVDA | $5.5T | 34.3x | 25.0x | 21.5x | 13.9x | 29.0x | 18.7x | 28.3x | 2.2% |
MU | $1.0T | 19.9x | 12.2x | 11.2x | 7.8x | 15.4x | 10.7x | 14.5x | 2.6% |
AVGO | $1.6T | 41.9x | 28.9x | 18.1x | 15.2x | 26.3x | 22.1x | 31.5x | 2.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
VRT | $97.1B | 55.8x | 37.5x | 8.5x | 6.9x | 22.2x | 18.2x | 38.2x | 3.0% |
COHR | $46.8B | 54.6x | 25.2x | 6.6x | 4.4x | 17.5x | 11.8x | 31.5x | -2.2% |
LITE | $77.1B | n/m | 39.2x | 25.6x | 12.2x | 61.4x | 29.4x | n/m | 0.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ANET | $232.5B | 57.4x | 44.8x | 22.1x | 18.3x | 35.0x | 29.1x | 45.3x | 2.2% |
ETN | $168.6B | 44.0x | 32.0x | 5.6x | 5.1x | 15.6x | 14.2x | 29.3x | 2.7% |
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
VICR | Revenue | +40.0% | +52.9% | +22.8% |
| EPS | +82.0% | +61.4% | +31.5% | |
WOLF | Revenue | +0.7% | −15.2% | +23.7% |
| EPS | +275.2% | −39.2% | −22.4% | |
GLW | Revenue | +18.0% | +19.3% | +20.9% |
| EPS | +30.5% | +32.6% | +36.6% | |
MLI | Revenue | +21.1% | +7.7% | +8.8% |
| EPS | +16.5% | +6.0% | +11.4% | |
009150.KS | Revenue | +26.8% | +32.3% | +30.0% |
| EPS | +127.8% | +107.2% | +54.8% | |
MPWR | Revenue | +49.3% | +28.9% | +20.5% |
| EPS | +55.0% | +31.2% | +20.6% | |
ON | Revenue | +9.2% | +13.1% | +13.9% |
| EPS | +37.1% | +40.9% | +30.2% | |
STM | Revenue | +22.4% | +18.7% | +13.2% |
| EPS | +104.2% | +98.3% | +45.6% | |
APH | Revenue | +55.3% | +18.5% | +12.8% |
| EPS | +61.0% | +22.8% | +14.1% | |
NVT | Revenue | +42.8% | +21.1% | +15.3% |
| EPS | +54.3% | +27.3% | +19.0% | |
KLAC | Revenue | +12.2% | +33.9% | +19.0% |
| EPS | +14.5% | +47.8% | +21.0% | |
5801.T | Revenue | +8.8% | +19.6% | +13.1% |
| EPS | +84.6% | +119.9% | +28.7% | |
NVDA | Revenue | +65.1% | +84.2% | +43.2% |
| EPS | +59.0% | +91.7% | +42.0% | |
MU | Revenue | +248.0% | +92.8% | +11.4% |
| EPS | +804.9% | +111.2% | +7.9% | |
AVGO | Revenue | +67.2% | +64.2% | +61.6% |
| EPS | +73.0% | +64.9% | +59.2% | |
VRT | Revenue | +37.1% | +30.2% | +21.3% |
| EPS | +62.9% | +36.7% | +26.4% | |
COHR | Revenue | +22.1% | +50.0% | +38.2% |
| EPS | +56.5% | +72.4% | +49.9% | |
LITE | Revenue | +83.9% | +109.8% | +56.8% |
| EPS | +314.0% | +163.9% | +60.0% | |
ANET | Revenue | +42.6% | +30.8% | +24.6% |
| EPS | +42.6% | +27.9% | +23.2% | |
ETN | Revenue | +20.0% | +11.2% | +9.7% |
| EPS | +12.6% | +19.3% | +17.2% |
Forward fiscal years only. Blank means no analyst coverage for that year.
What the tape actually says
The drawdown is real and it is deep. Measured peak-to-22-July, WOLF is -60.2% (peak 26 May), VICR -42.8% (30 June), 009150.KS -40.7% (19 June) and GLW -39.7% (29 June), against ON -31.1%, STM -17.7%, MPWR -17.2%, NVT -14.0% and APH -10.7%. But it is not confined to second-tier components: COHR -26.9%, LITE -21.2%, MU -20.9%, VRT -20.0%, AVGO -17.6% and NVDA -10.0% are all off post-May highs while SPY is only -1.6%. The dated trigger is the semiconductor sell-off that began 1 July, when Micron shed ~13% and ~$138B of value on reports SK Hynix was slowing HBM capacity expansion, alongside AI-ROI skepticism and a hawkish Fed.
The trend-band evidence cuts directly against the "early leg of a downtrend" reading. GLW and 009150.KS have been in unbroken strongly bullish bands since at least 2 February; WOLF has been mildly bullish since 2 July; VICR only downgraded strongly bullish to mildly bullish on 20 July, three sessions before the latest data. All five names remain above their approximate 200-day averages, and on longer horizons the cohort is still up hard — 009150.KS +98% over three months and +893% over twelve, VICR +381% over twelve.
Two corroborators are data artifacts
Mueller's -54% is a two-for-one split that began split-adjusted trading on 1 July; adjusted, MLI is roughly -7% over three months, and its strongly bearish band flip is split-contaminated. KLAC's -88% is a ten-for-one split effective 12 June and Furukawa's -91% a 10-for-1 split effective 1 July. Copper offers no help either — LME cash was about 4.5% below early-June levels in early July.
Multiples, not demand
Going in, GLW traded at 106x trailing earnings and VICR at 109x and 35x sales. Vicor's Q2 was an operational beat — revenue $143.4M, +49% YoY, 58% gross margin, backlog +26% sequentially — yet shares slipped because ~$15M of one-time royalty revenue flattered margin and the first CHiP fab is nearing full utilization. Corning fell 13.3% on 1 July with no demand news after a Q1 that showed core sales +18% and Optical +36% YoY; its Q2 guide of ~$4.6B and a 28 July print both postdate the sell-off. onsemi does not report until 3 August, so its -31% carries no guidance cut. In Korea, Hana kept a ₩3,000,000 target versus a ₩1,345,000 close on persistent MLCC/FCBGA tightness — and that leg had its own earlier shakeout on 2 June.
Only Wolfspeed shows genuine fundamental damage: -27% GAAP gross margin and Q4 revenue guided to $140-160M, with July declines tied to chip-sector weakness and share-supply overhang and a Chinese SiC price war that long predates July. Two hypothesised drivers behave differently than assumed: DDR5 up 7% in July and ~448% YoY is a real margin tax on hardware, but NVIDIA's 800 VDC reference architecture names a dozen silicon and power partners — it widens the supplier set rather than in-sourcing it. VICR's slide did come on rising volume (1.76M shares on 21 July versus 500-900k typical in June), the one distribution-flavoured detail in the pack.