

Geothermal's pure-play fell 23% in the same 30 days PGEO rose 22.6%
Prompt v1.0
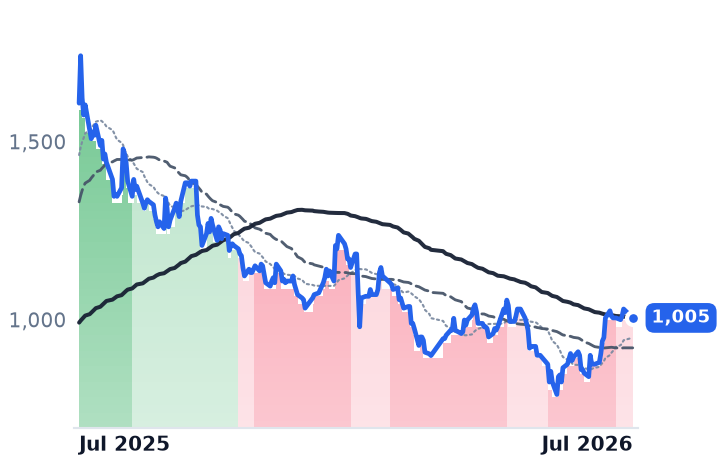
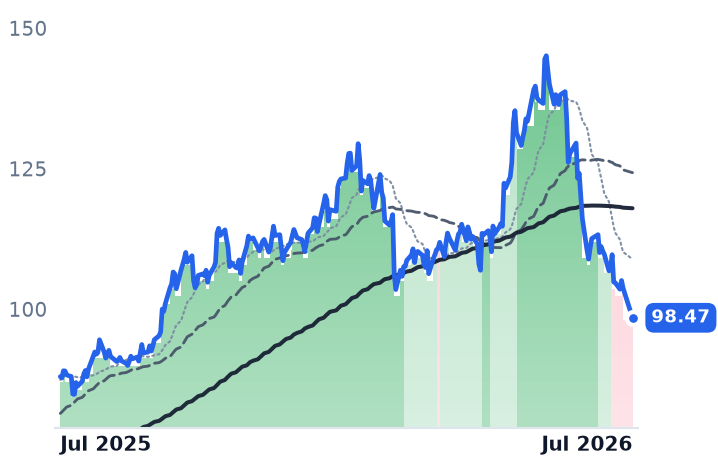
PGEO.JK's +22.6% month is a gap-free bounce off a 52-week low, not a trend entry — it is still 6.9% below its 200-day and only left strongly bearish on 17 July. The cohort test now fails hard: listed EGS pure-play Fervo fell 23.3% over the identical window and Ormat de-rated 25% off a dated 16 June short-seller-style initiation.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
PGEO.JK | PT Pertamina Geothermal Energy Tbk | — | 🔴 Cont. Bear | +19.6% | −37.5% |
ORA | Ormat Technologies | Geothermal & Specialized | 🟢 Cont. Bull | −10.9% | +11.9% |
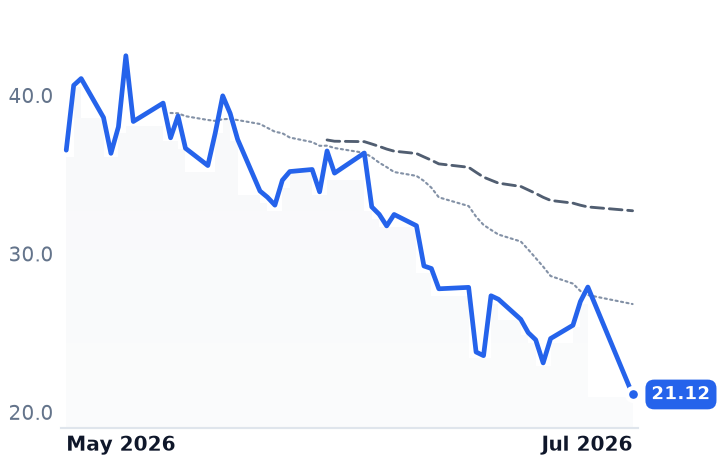
FRVO | Fervo Energy | Emerging & Specialized Energy | 🔴 Cont. Bear | −33.5% | −42.2% |
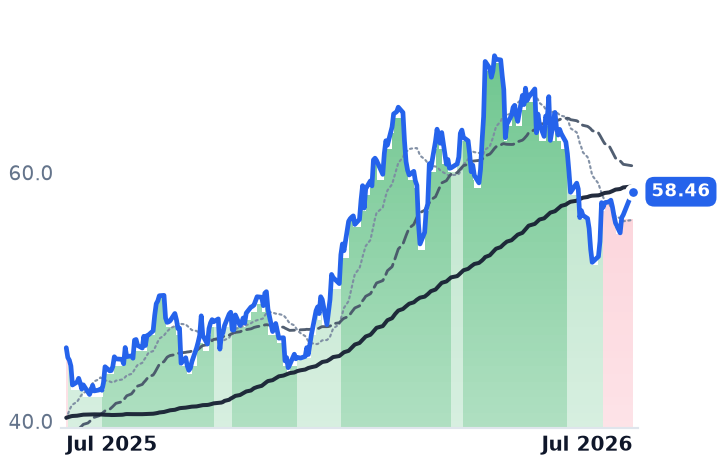
BKR | Baker Hughes | Well Services & Stimulation | 🟢 Cont. Bull | +3.8% | +27.3% |
CWEN | Clearway Energy | Wind & Solar Developers | ⚠️ Emerging Bear | −10.6% | +4.4% |
BEP | Brookfield Renewable Partners | Diversified Renewable Generators | 🟢 Cont. Bull | −8.3% | +18.1% |
NEE | NextEra Energy | Vertically Integrated Utilities | ⚠️ Emerging Bear | +0.7% | +27.8% |
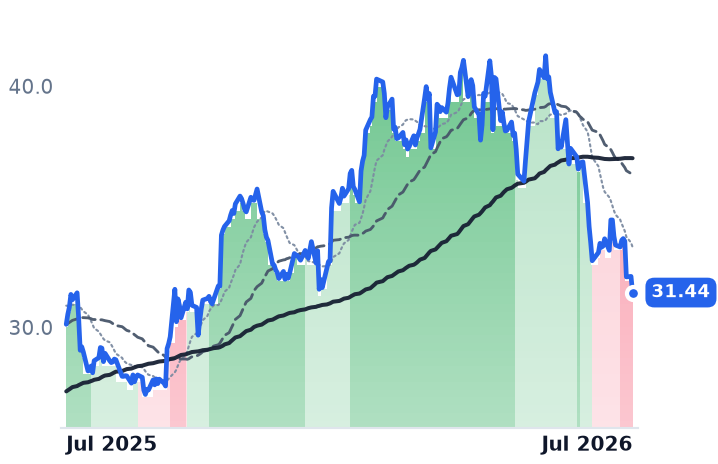
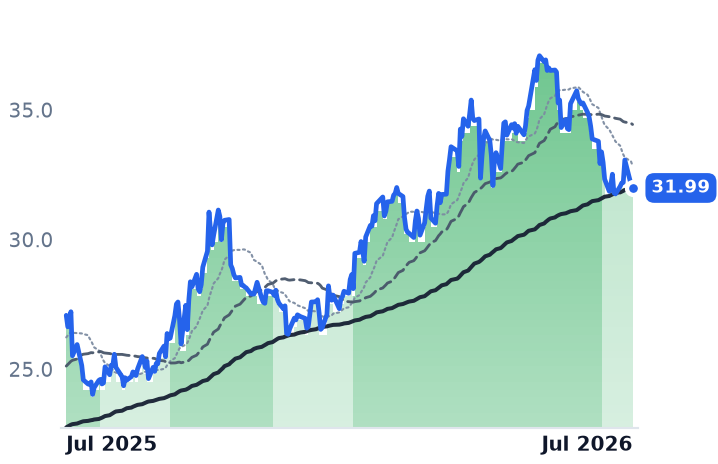
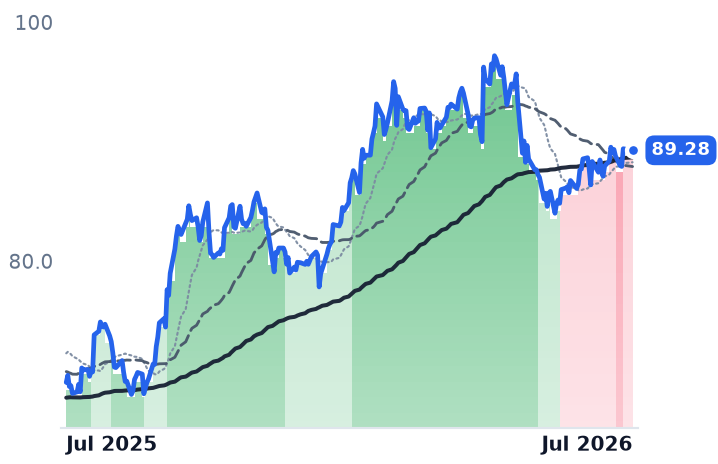
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
PGEO.JK | — | — | — | — | — | — | — | — | — |
ORA | $8.1B | 62.8x | 57.4x | 6.9x | 7.0x | 25.2x | 25.4x | 18.8x | -2.7% |
FRVO | $6.9B | n/m | — | — | — | — | — | n/m | -7.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BKR | $63.6B | 20.4x | 26.8x | 2.3x | 2.3x | 9.7x | 9.8x | 14.3x | 3.6% |
CWEN | $6.5B | 793.3x | — | 4.4x | 3.9x | 8.5x | 7.5x | 14.3x | 9.0% |
BEP | $10.6B | 75.5x | — | 1.7x | 1.6x | 6.9x | 6.4x | 10.0x | -44.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NEE | $194.7B | 23.8x | 23.1x | 6.9x | 6.3x | 10.3x | 9.4x | 17.3x | 1.2% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
ORA | Revenue | +19.2% | +1.7% | +10.7% |
| EPS | +4.8% | +8.5% | +29.3% | |
FRVO | Revenue | +4533.3% | +1135.0% | +195.3% |
| EPS | −96.2% | +22.8% | −38.0% | |
BKR | Revenue | +0.4% | +7.9% | +3.5% |
| EPS | −2.8% | +19.8% | +13.6% | |
CWEN | Revenue | +17.0% | +11.6% | +12.6% |
| EPS | −164.1% | −148.8% | +63.8% | |
BEP | Revenue | +6.1% | +11.0% | −0.0% |
| EPS | +4.7% | −20.8% | +4.8% | |
NEE | Revenue | +9.0% | +9.3% | +8.6% |
| EPS | +9.4% | +8.8% | +8.4% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The cohort check that closes the case
This desk flagged this morning that geothermal's policy edge was real while the trade was not a cohort. Three new pieces of evidence now settle it.
First, the pure-play. Fervo Energy (FRVO) — which IPO'd on 13 May 2026 at $27 and closed its first day up 35% at $36.54 on AI-datacenter demand — fell from $36.36 on 22 June to $27.90 on 22 July, a 23.3% decline over the exact window PGEO gained 22.6%. It printed $23.11 on 16 July, below its IPO price. That happened despite a company drilling record at Cape Station Phase II: total depth in 21 days, 19,448 ft, a 7,500-ft lateral into a 460°F resource and Q1 numbers showing a Google framework agreement for up to 3 GW through 2033 plus $421.4m of Cape Station project financing — against $0.061m of revenue and a $31.83m net loss. Operational execution is not being paid for.
Second, Ormat's slide has a date. Bernstein initiated ORA at Underperform with a $115 target on 16 June, citing conventional-exploration risk and doubts it can compete with Fervo in EGS — shares were $133.96. ORA closed 22 July at $103.74, below the bear case, 10.5% under its 200-day, with bands walking from strongly bullish (15 May–2 July) to mildly bearish from 14 July. That is a valuation unwind, not a demand failure: Ormat signed a 150 MW portfolio PPA with NV Energy in February to serve Google's Nevada datacenters, corporate geothermal PPAs tripled to 635 MW in 2025, and guidance stands at $1,110–1,160m revenue with Q2 results due 5 August.
What PGEO actually is
The advance was gap-free on real volume (47.6m shares 8 July, 49.4m 10 July), and the Rp53.09 dividend was paid 3 July — before the rally, so no ex-date artifact. But it started from a 52-week low of 790 on 8 June, leaves the stock 43.7% below its 1,830 high, 8.8% down YTD, and below its 1,105.8 200-day. It also overlaps a broad Indonesian market move: the JCI rallied 2.34% to 5,879 on 8 July and reached 6,171 by 28 July, though investors are now digesting Bank Indonesia governor Perry Warjiyo's unexpected resignation.
Fundamentals are genuinely improving — production up 14.5% to 2,284 GWh in five months and Lumut Balai Unit 2 lifting managed capacity to 727 MW — with BRI Danareksa lifting its target to Rp1,300 on 16 July, ~26% above spot. The policy leg is the strongest part: geothermal keeps full 48E/45Y credits on a 2033 begin-construction window stepping to zero after 2035, versus solar and wind facing an end-2027 in-service cliff. Indonesia's own reform is partial: the new PPA regulation sets 30-year terms with geothermal provisions, but tariffs were held flat for Q1 2026. Baker Hughes, the drilling layer, is down from 62.54 to 56.60 since April. Policy and offtake are confirming; equity breadth is not.