

US LNG exporters: the re-rating already happened, not an early leg
Prompt v1.0
Venture Global's +31.6% month is real and gap-free, but the US LNG export cohort is not exiting bear bands — VG, LNG, CQP, GLNG, FLNG, NEXT and EE have all been in bull bands since Q1 and every one trades above its 200-day average. This is a mid-to-late-stage 2026 re-rating whose macro leg (record feedgas, cheap Henry Hub, firm JKM) is already in the price, with consensus and forward TTF pointing the other way.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
VG | Venture Global | LNG Export & Infrastructure | 🌱 Emerging Bull | +9.1% | −19.3% |
LNG | Cheniere Energy | LNG Export & Infrastructure | 🟢 Cont. Bull | +3.4% | +11.2% |
NFE | New Fortress Energy | Regulated Gas | 🔴 Cont. Bear | −2.9% | −91.7% |
CQP | Cheniere Energy Partners | LNG Export & Infrastructure | 🌱 Emerging Bull | +5.8% | +20.3% |
GLNG | Golar LNG | Marine LNG & LPG Transportation | 🟢 Cont. Bull | −2.0% | +22.7% |
FLNG | FLEX LNG | Marine LNG & LPG Transportation | 🟢 Cont. Bull | +5.5% | +39.1% |
NEXT | Nextdecade | LNG & Energy Transition | 🌱 Emerging Bull | −16.6% | −46.1% |
EE | Excelerate Energy | LNG Infrastructure | 🟢 Cont. Bull | +0.8% | +58.1% |
NG=F | Natural Gas Sep 26 | — | 🔴 Cont. Bear | −15.8% | −10.3% |
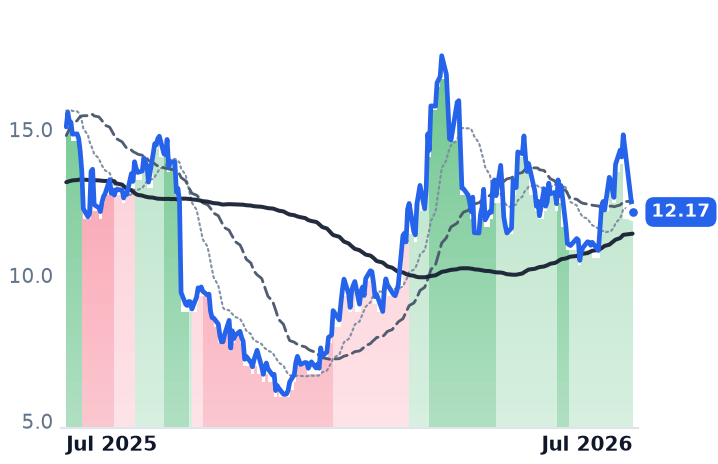
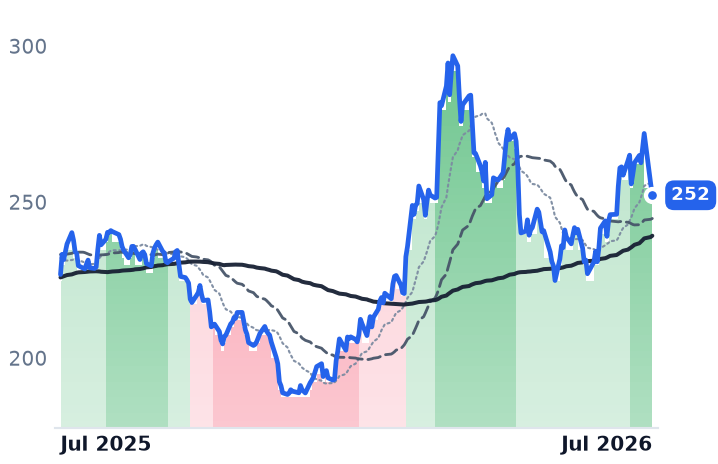
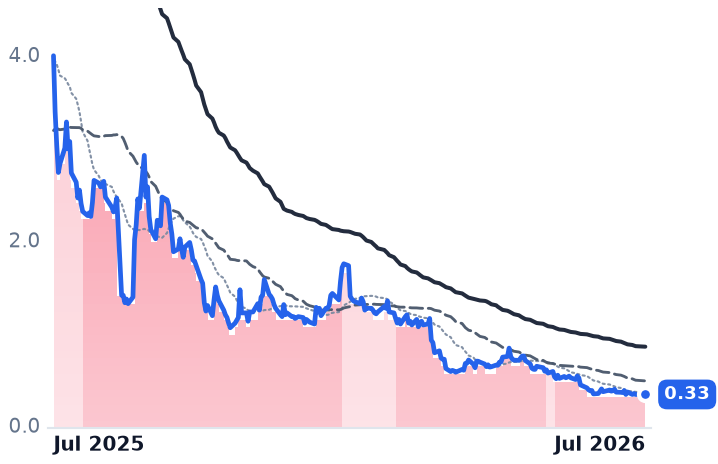
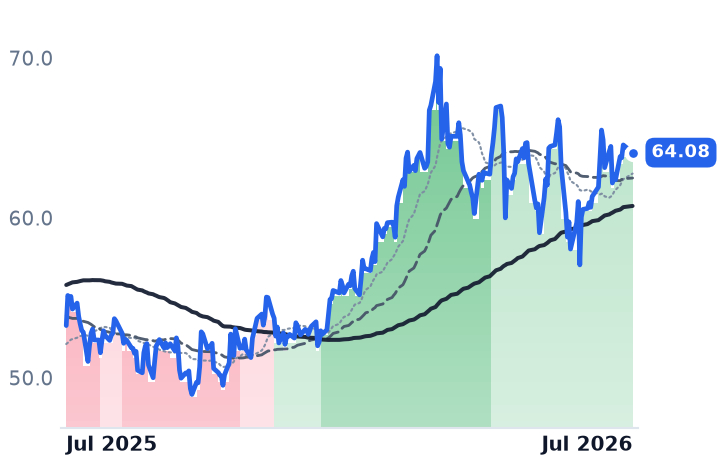
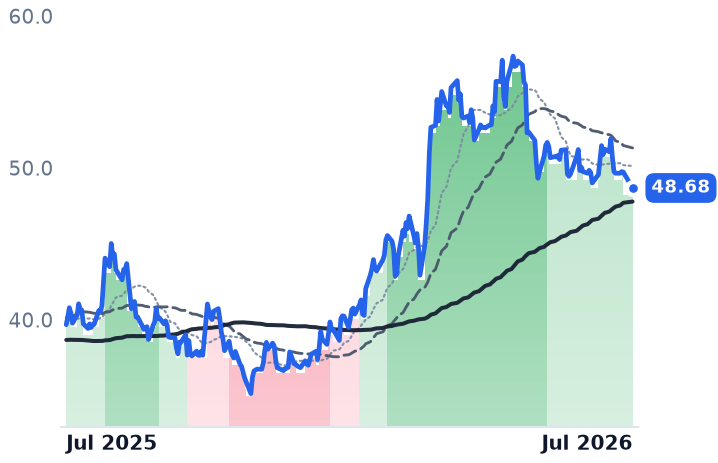
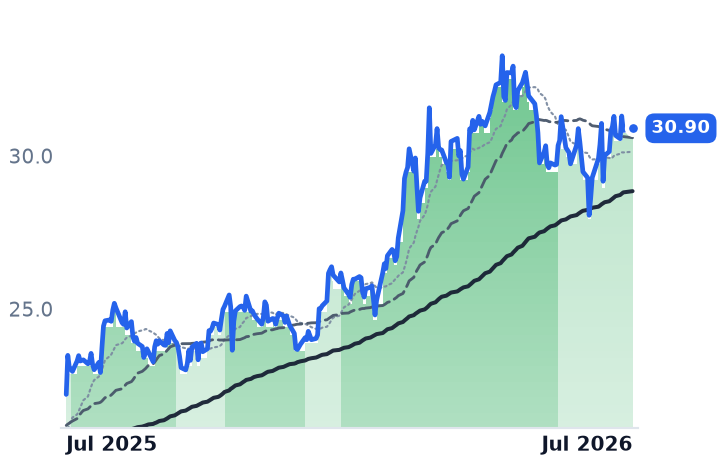
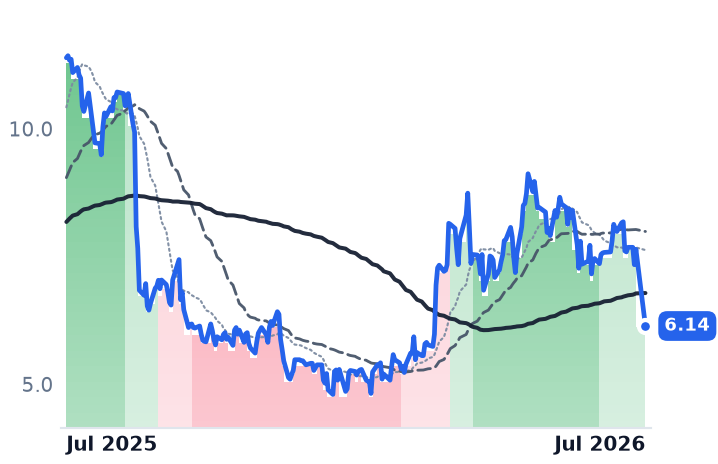
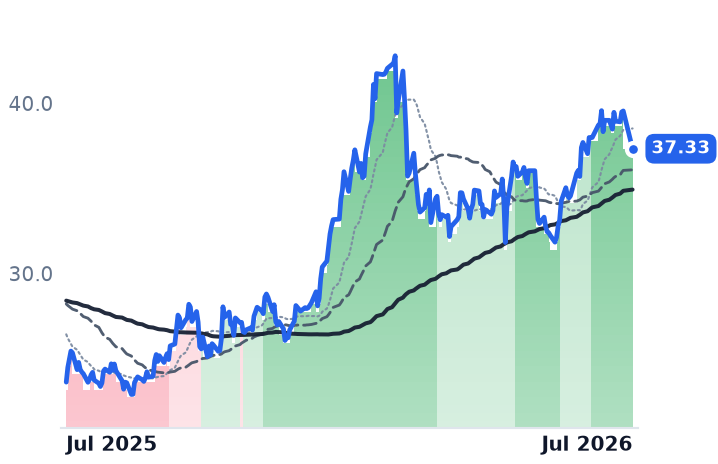
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
VG | $34.2B | 10.3x | 9.2x | 2.0x | 1.9x | 4.2x | 3.9x | 4.4x | -27.5% |
LNG | $56.9B | 20.1x | — | 2.6x | 2.6x | 4.8x | 4.8x | 10.0x | 12.4% |
NFE | $197.4M | n/m | — | 0.2x | 0.1x | 1.0x | 0.4x | n/m | -519.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CQP | $33.4B | 11.5x | 17.6x | 2.9x | 2.8x | 7.8x | 7.5x | 11.3x | 9.8% |
GLNG | $5.8B | 88.0x | 70.1x | 14.8x | 14.5x | 31.5x | 31.0x | 39.0x | -7.4% |
FLNG | $1.7B | 23.0x | 15.7x | 5.1x | 5.0x | 10.2x | 9.9x | 13.3x | 5.9% |
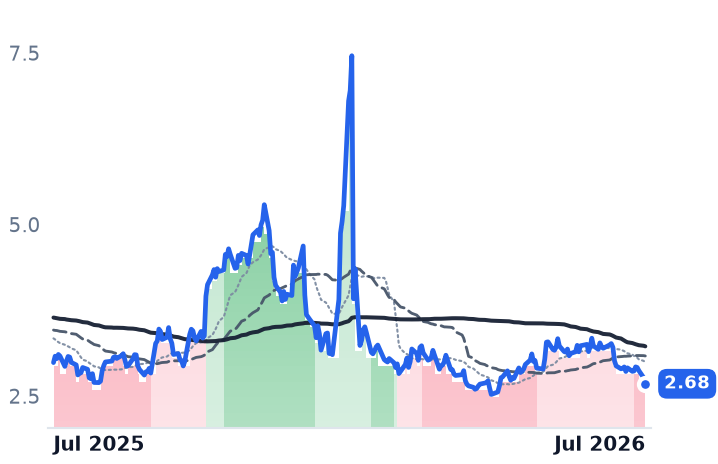
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NEXT | $1.9B | n/m | — | n/m | 6.1x | — | — | n/m | -201.3% |
EE | $4.1B | 28.5x | 22.9x | 3.1x | 2.7x | 9.3x | 8.1x | 11.6x | 820.6% |
NG=F | — | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
VG | Revenue | +33.3% | −12.6% | +29.6% |
| EPS | +83.8% | −52.8% | +75.1% | |
LNG | Revenue | +11.9% | +6.0% | +3.4% |
| EPS | −141.4% | −345.2% | −8.0% | |
NFE | Revenue | +89.1% | +3.5% | −36.7% |
| EPS | −71.2% | −105.6% | −185.7% | |
CQP | Revenue | +12.8% | −3.2% | +4.3% |
| EPS | −4.9% | +9.5% | +1.7% | |
GLNG | Revenue | +0.8% | +7.2% | +103.0% |
| EPS | −41.4% | −4.2% | +409.1% | |
FLNG | Revenue | +4.1% | +0.8% | +2.1% |
| EPS | +13.6% | +3.8% | +10.2% | |
NEXT | Revenue | — | +267.6% | +129.4% |
| EPS | +25.3% | −62.3% | −17.3% | |
EE | Revenue | +30.6% | +19.1% | +11.6% |
| EPS | +13.2% | +28.6% | +40.2% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The band evidence contradicts the "early leg" framing
The premise was that US liquefaction owners might be exiting bear trends. They aren't — because they were never in them. Across the cohort, VG, Cheniere, CQP, Golar, Flex, NextDecade and Excelerate have all sat in mildly bullish or strongly bullish crossover bands continuously since Q1 2026, and every one trades above its 200-day average: VG $14.82 vs $10.67, LNG $255.88 vs $232.18, CQP $64.56 vs $58.89. VG's last bear band ended 2026-03-06. The only genuine band upgrade in 30 days was Cheniere's mildly bullish→strongly bullish on 2026-07-14. The lone bear is New Fortress Energy, in strongly bearish since 2026-06-02 at $0.33 against a $1.02 200-day average — a restructuring story, not a cohort read.
Year-to-date the re-rating is already large: VG +117%, NEXT +45%, EE +41%, GLNG +34%, LNG +32%, FLNG +24%, CQP +21%, all while Henry Hub fell 25% to $2.75. That is the cheap-feedgas thesis — it has simply been paid for.
The macro leg is confirmed but maturing
The spread story checks out for the rally window: JKM for August delivery pushed into the high-$17s while Henry Hub slid to its lowest in six weeks on softer weather and stronger inventories, with Hormuz tension lifting JKM and TTF as US prices fell — a spread near $15/MMBtu. Volumes back it: US LNG feedgas demand is running above 20 Bcf/d, and Golden Pass shipped its first cargo on 22 April 2026 as the ninth US export terminal.
But the forward deck narrows the arb. Kpler sees 37-41 Mt/yr of new liquefaction ramping into a 2026 surplus, and the IEA forecasts TTF at $10.55/MMBtu in 2026 and $9.30 in 2027 versus $12.31 in 2025. The EU demand backstop is shakier than headlines suggest: the US-EU framework's $750B energy pledge implies $250B/yr against $76B of actual 2024 EU purchases, which analysts call unrealistic without a sixfold increase.
VG is idiosyncratic, not cohort beta
VG's move had no single gap, but four high-volume repricing days (+6.8%, +6.8%, +9.2%, +8.9%) map to company news: the Atlantic-SEE Greece SPA doubling to 1.0 MTPA, an EnBW deal for ~0.82 MTPA, and a CP2 filing on 7 July to export up to 620.5 Bcf/yr. On a 3-month view the cohort is mixed — LNG +3.9%, CQP +3.5%, GLNG -5.6%.
Runway is thin: 19 analysts average a $15.24 target, ~3% above the last close, while insiders sold into the rally, including the CFO's $3.14m and the general counsel's entire stake. The BP arbitration found VGCP in breach with damages to be quantified in a separate 2026 hearing against $4B+ of claims. Cheniere's 5.9% drop on 27 July preceded earnings — Q2 results are set for 6 August.