

The 'LatAm Capitulation Basket' Is Built on a Faulty Premise
Prompt v1.0
SBS's apparent -81% five-day collapse is entirely a 1-for-5 stock split artifact — no economic value was destroyed and the underlying business is accelerating. MEG is a US company, not LatAm. HAPV3 and EDN have distinct idiosyncratic drivers with no shared macro thread. EWZ is up ~60% year-over-year. There is no LatAm basket selloff.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
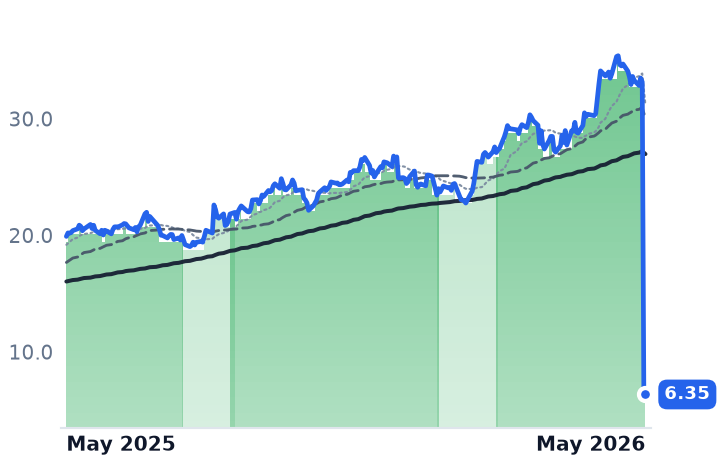
SBS | Companhia de Saneamento Básico do Estado de São Paulo - SABESP | International Diversified | 🟢 Cont. Bull | −81.4% | −68.1% |
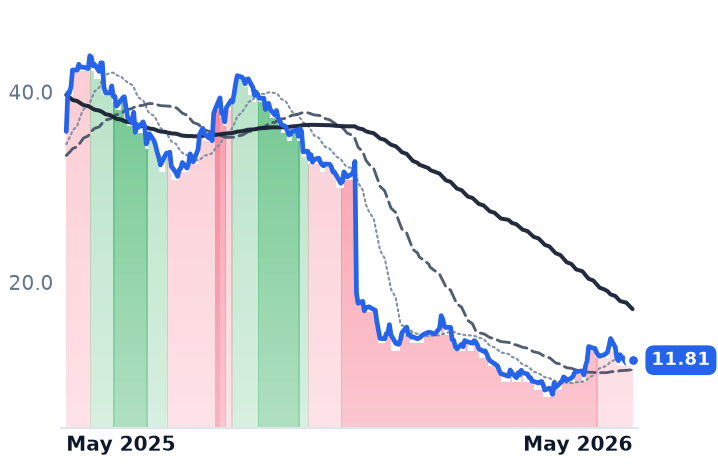
HAPV3.SA | Hapvida Participações e Investimentos | Insurance - Specialty | 🔴 Cont. Bear | −10.9% | −67.1% |
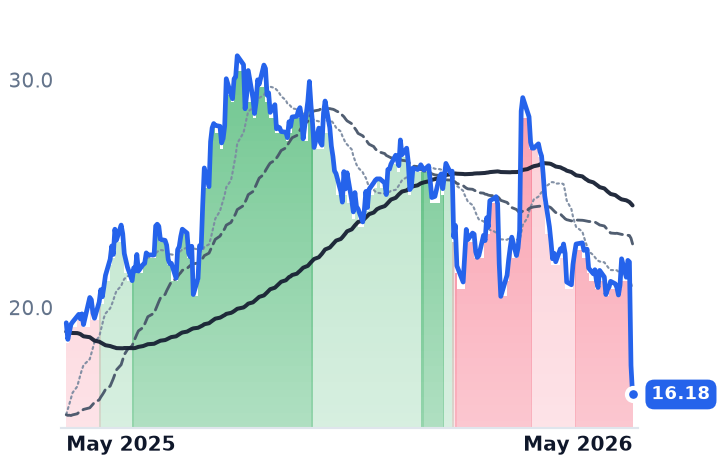
MEG | Montrose Environmental | Hazardous & Specialty Waste | 🔴 Cont. Bear | −25.5% | −16.3% |
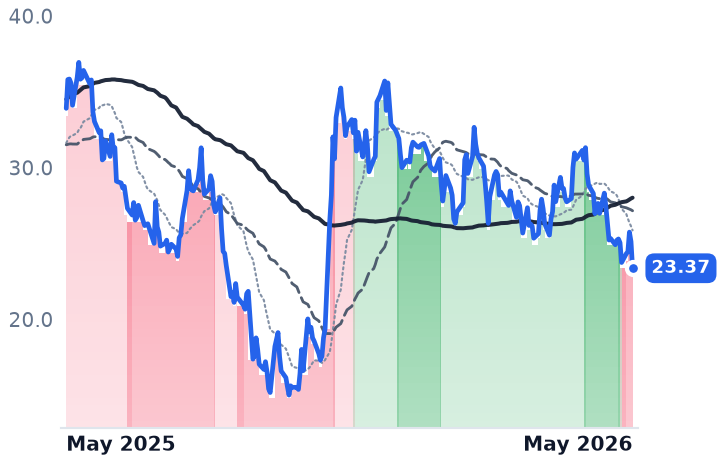
EDN | Empresa Distribuidora y Comercializadora Norte Sociedad Anónima | International | 🌱 Emerging Bull | −19.0% | −31.1% |
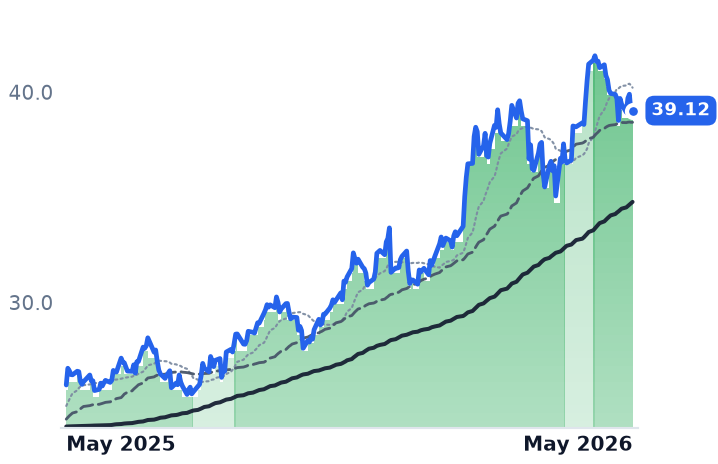
EWZ | iShares MSCI Brazil ETF | Asset Management | 🟢 Cont. Bull | −5.3% | +50.0% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SBS | $21.9B | 2.8x | — | 2.8x | — | 7.8x | — | 8.7x | 5.4% |
HAPV3.SA | $5.6B | n/m | 13.6x | 0.2x | 0.2x | 1.7x | 1.6x | 5.8x | 4.7% |
MEG | $565.7M | n/m | — | 0.7x | 0.8x | 2.1x | 2.1x | 17.6x | 9.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
EDN | $767.4M | 4.6x | — | 0.4x | — | 1.5x | — | 3.8x | -20.2% |
EWZ | $7.4B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
SBS | Revenue | +8.1% | +18.3% | +12.5% |
| EPS | −23.6% | +35.8% | +18.9% | |
HAPV3.SA | Revenue | +4.5% | +5.4% | +5.7% |
| EPS | −54.3% | +77.5% | +37.5% | |
MEG | Revenue | −8.9% | +8.6% | +8.8% |
| EPS | +1152.5% | −219.8% | +103.9% | |
EDN | Revenue | +49.9% | +23.9% | −26.0% |
| EPS | −88.1% | +1060.9% | −10.1% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The Core Premise Doesn't Hold
The hypothesis rests on SBS suffering an "-81% five-day collapse" as a leading indicator of broader LatAm stress. That number is real — but the cause is not a capitulation event. Sabesp shareholders approved a 1-for-5 forward stock split at an Extraordinary General Meeting on April 28, 2026, with ADR ex-split trading beginning May 7, when each existing ADR holder received four additional ADRs. On a split-adjusted basis, SBS declined roughly 4% over that window — a rounding error, not a vertical collapse.
The institutional read confirms this. Wellington Management disclosed crossing the 5% ownership threshold in Sabesp on the same April 28 date, accumulating 35.9 million ordinary shares. The split is explicitly designed to increase retail accessibility — bringing the share price from ~R$34 into the ~R$6.80 range to attract B3 retail participation and lift daily trading volumes through Q2 2026. Jefferies initiated SBS with a Buy rating in March 2026, with a split-adjusted price target of ~$7.32.
Operationally, Sabesp is executing: Q1 2026 earnings were strong, with a R$3.7 billion capex surge, and 2025 full-year investments hit a record R$15.2 billion — more than double 2024 levels. The key residual risk is regulatory: R$15.2 billion in 2025 capex must be validated by regulator ARSESP for inclusion in the Regulated Asset Base, and partial non-recognition would reduce returns on capital. On valuation, SBS trades at a trailing EV/EBITDA of 3.66x, P/B of 0.51x, and FCF yield of 36.4% — compressed multiples consistent with a regulated utility still building its concession track record post-privatization.
The Other Three Names Have No Common Thread
MEG is not a LatAm equity. Montrose Environmental Group is headquartered in North Little Rock, Arkansas, and has zero Latin American exposure. Its ~26% two-day drop reflected a company-specific Q1 2026 earnings miss: revenue fell 5.2% year-over-year to $168.5M, net loss widened to -$12.7M, and management had pre-guided Q1 as its seasonally weakest quarter. Full-year 2026 guidance of $840M–$900M revenue and $125M–$130M adjusted EBITDA was maintained. Its 90-day decline from ~$29.22 (Feb 27) to ~$16.18 (May 8) is entirely idiosyncratic to US environmental services dynamics.
HAPV3.SA (Hapvida) is a genuine Brazilian HMO story, but it's a chronic sector-level pressure play — not a macro shock. The company posted a 2025 net loss of R$141.7 million, with Q4 2025 gross margin at only 9.1%, reflecting persistent healthcare cost inflation and claims pressure. Notably, HAPV3 had already recovered from its March 2026 trough of R$8.21 back to R$14.09 by late April before pulling back to R$11.81. Forward P/E on consensus recovery estimates is 13.6x, and P/B is 0.12x — suggesting deep value but also structural uncertainty in Brazilian managed care.
EDN (Edenor) has declined ~25% from its April 6 peak of ~$31.14 to ~$23.37 on May 8 — but this reflects Argentina-specific regulatory and tariff-reset dynamics, with ARS-denominated revenues heavily distorted by hyperinflationary accounting (2025 nominal revenues +71% YoY). It shares no catalyst with the Brazilian names.
Brazil Macro Is Not in Crisis
The macro framing of the hypothesis — BRL collapse, Bovespa breakdown, fiscal/political shock — is not supported by the data. EWZ, the iShares MSCI Brazil ETF, traded at ~$39.12 on May 8 with a 1-year total return of +60%, well within a strong bull trend. EWZ rallied +18.5% from its March 20 trough of $35.06 to an April 13 peak of $41.53 before a mild ~6% pullback. Brazil's Ibovespa slipped about 1% recently below 179,000 on central bank caution — moderate noise, not regional stress.
The four tickers in this watchlist have a 5-day return correlation close to zero on a fundamental basis: one experienced a mechanical split, one is a US name with a quarterly miss, one is a Brazilian HMO recovering from a sector trough, and one is an Argentine utility navigating local tariff cycles. The "basket" is a construction artifact, not a signal.