

Grid-Storage Bifurcation: FLNC's Hyperscaler Surge vs. EOSE/SMR Collapse
Prompt v1.0
Fluence Energy's near-doubling in five days on hyperscaler supply agreements and a record $5.6B backlog stands in sharp contrast to Eos Energy's post-earnings crater and NuScale's pre-commercial limbo — three competing grid/storage solutions diverging violently within the same AI-power-demand thesis. Meanwhile, established IPPs CEG and NRG are each down 20–25% from late-2025 peaks, suggesting the market is narrowing its conviction to contract-secured storage leaders rather than speculative power plays.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
FLNC | Fluence Energy | Energy Storage | ⚠️ Emerging Bear | +75.3% | +324.6% |
EOSE | Eos Energy Enterprises | Energy Storage & Batteries | ⚠️ Emerging Bear | +42.5% | +26.5% |
SMR | NuScale Power | Advanced Power Systems | 🔴 Cont. Bear | +36.3% | −29.5% |
CEG | Constellation Energy | Wholesale Generators | 🔴 Cont. Bear | +6.0% | +7.0% |
NRG | NRG Energy | Retail-Focused Operators | ⚠️ Emerging Bear | −15.8% | −7.5% |
VST | Vistra | Retail-Focused Operators | 🔴 Cont. Bear | −4.5% | +1.6% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FLNC | $1.4B | n/m | — | 0.5x | 0.4x | 5.8x | 4.7x | n/m | -9.4% |
EOSE | $929.5M | n/m | — | 4.3x | 3.0x | — | — | n/m | -45.3% |
SMR | $1.5B | n/m | — | 549.6x | 88.6x | — | — | n/m | -40.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CEG | $107.0B | 29.0x | 24.7x | 3.5x | 3.2x | 20.0x | 18.4x | 15.8x | 0.3% |
NRG | $21.2B | — | 11.3x | — | 0.6x | — | — | 10.5x | 1.6% |
VST | $54.4B | 27.0x | 18.7x | 3.4x | 2.4x | 26.3x | 18.7x | 11.3x | 2.5% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
FLNC | Revenue | −2.5% | +29.2% | +23.8% |
| EPS | +277.1% | −76.7% | −169.5% | |
EOSE | Revenue | +104.1% | +87.2% | +86.5% |
| EPS | −82.9% | −69.8% | −181.4% | |
SMR | Revenue | −59.6% | +507.1% | +271.3% |
| EPS | −77.1% | +14.4% | −16.3% | |
CEG | Revenue | +37.2% | +2.5% | +5.3% |
| EPS | +28.9% | +10.4% | +26.4% | |
NRG | Revenue | +17.7% | +0.8% | +3.7% |
| EPS | +14.0% | +24.5% | +15.8% | |
VST | Revenue | +16.7% | +9.7% | +5.4% |
| EPS | +80.8% | +18.5% | +18.5% |
Forward fiscal years only. Blank means no analyst coverage for that year.
What's happening
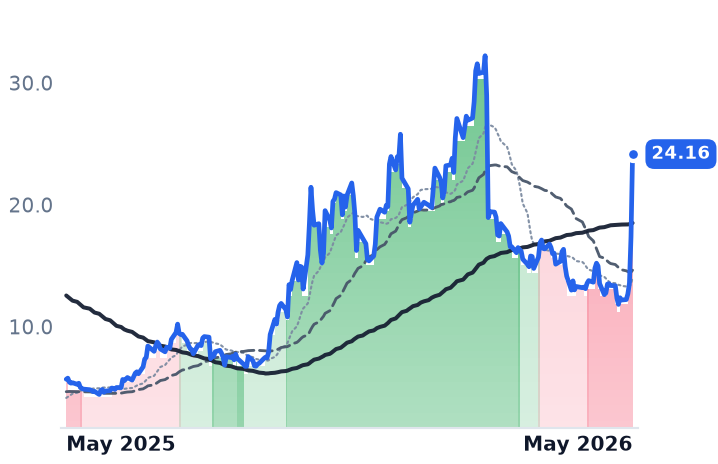
Fluence Energy (FLNC) surged from ~$12.19 on May 1 to $24.16 on May 8, 2026 — a ~98% five-day move — after Q2 FY2026 earnings reported May 6 delivered two hyperscaler master supply agreements and a record $5.6B backlog. The stock is technically still in a strongly bearish trend band and sits roughly 26% below its February 2026 peak near $32, meaning the violent rally is a recovery-within-a-downtrend rather than a breakout to new highs.
Roth/MKM doubled its price target to $26 and upgraded to Buy, citing order growth as the key driver. Goldman Sachs raised to $22, Canaccord to $28, and JPMorgan hiked to $17 while keeping Neutral — a broad but uneven analyst upgrade cycle. The revenue miss ($464.9M vs. $628M+ consensus) was forgiven; what moved the stock was Fluence's 41.3 GW / 147 GWh pipeline expansion and ~$900M total liquidity, along with reaffirmed FY2026 guidance of $3.2–$3.6B revenue and $40–$60M Adjusted EBITDA, with full-year revenue described as already covered by backlog.
Important context: FLNC reported FY2025 revenue of $2.3B with gross margin improving to 13.1%, and had 85% of FY2026 revenue already secured at that point. The caution flag is that FLNC's YTD performance is still -11%, and the recovery thesis hinges on lumpy quarterly execution as hyperscaler orders convert to shipped revenue. FLNC is also RSI overbought and appears on most-shorted stock lists with elevated short interest, a setup that amplifies both the squeeze and subsequent consolidation risk. A prior red flag: Fluence cut FY2025 guidance by $700M at the midpoint in Q2 2025, blaming tariff-driven project pauses and ~$20M EBITDA impact — illustrating how quickly contract timing can shift.
The EOSE setup: resolved going-concern, but dilution looms
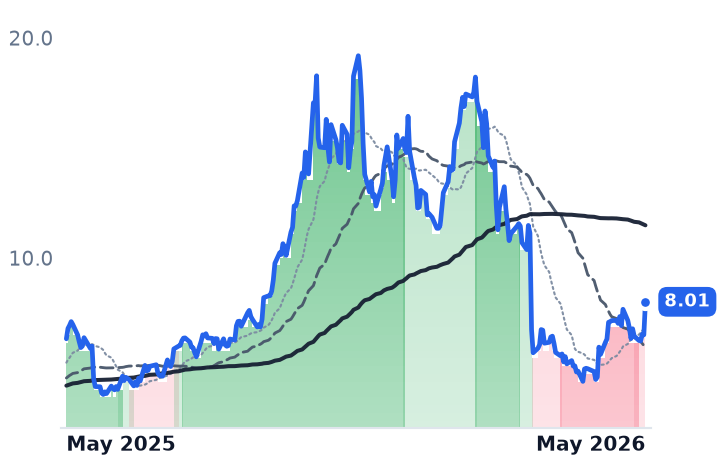
Eos Energy (EOSE) is a different beast. Its ~56% six-month decline traces directly to a Q4 2025 earnings miss — $58M revenue vs. a ~$94M consensus — that triggered a ~57% single-session crash in late February 2026. Yet full-year 2025 revenue of $114.2M represented 7x year-over-year growth, and 2026 guidance of $300–$400M implies another 3–4x step-up.
The going-concern overhang is formally resolved: EOSE ended 2025 with $624.6M cash after a $600M convertible notes and equity raise, with 2 GWh annualized production capacity achieved. The headline net loss of $969.6M was driven by $746.8M of non-cash fair value adjustments, not cash operating losses. Backlog stands at $701.5M (2.8 GWh) across 8 customers, and the DOE Loan Programs Office committed $303.5M total to support 8 GWh capacity by 2027, with the second advance of $22.7M already drawn.
However, EOSE is seeking shareholder authorization to expand authorized shares from 600M to 800M and add 5M shares to its incentive plan at its June 2026 annual meeting — a structural dilution overhang that is a real near-term constraint on any re-rating. The stock has bounced from an April trough near $4.48 to $8.01 and shifted from strongly bearish to mildly bearish, but remains well below its pre-earnings level near $13.
SMR: structurally weakest, longest runway to revenue
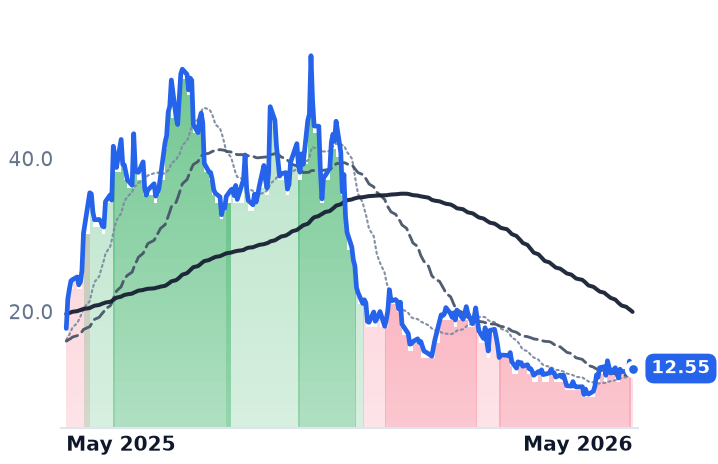
NuScale (SMR) is down ~56% over six months, from ~$28.43 in November 2025 to $12.55 on May 8, stabilizing from April lows near $9.16. Unlike FLNC and EOSE, the decline isn't post-earnings punishment — it's a slow repricing of a pre-commercial story. NuScale received NRC design approval for its 77 MWe module in May 2025, making it the only SMR design NRC-approved, but no binding commercial contracts have been signed. The flagship UAMPS project in Idaho was cancelled in November 2023 after cost estimates ballooned from $3.6B to $9.3B and target electricity cost rose to $89/MWh from $55/MWh.
NuScale's Romania project final investment decision may slip to early 2027, and even after a commercial contract is signed, the NRC licensing process for an actual plant can take 30+ months. First revenue is years away.
The IPP backdrop: AI-power thesis broadly repriced
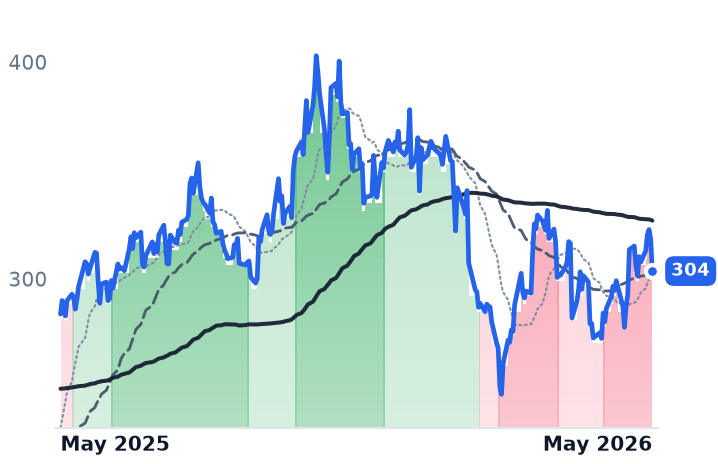
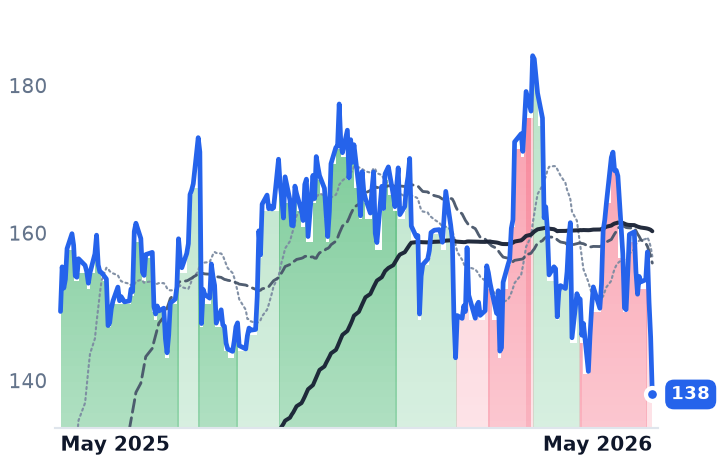
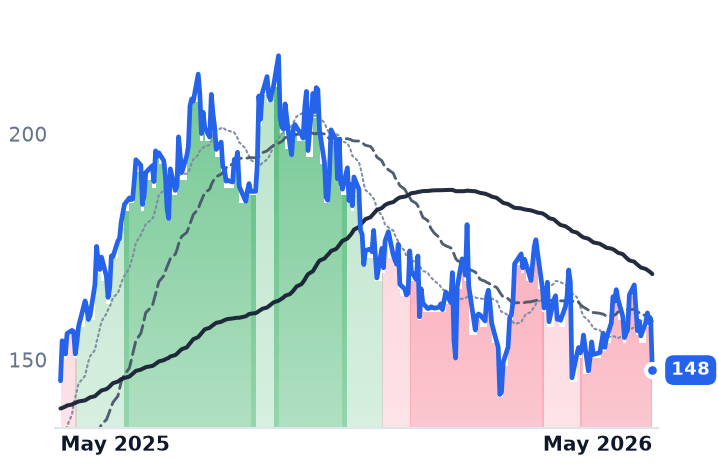
The peer context amplifies FLNC's differentiation. Constellation Energy (CEG) has fallen ~24% from its October 2025 peak to $303.63 and has been in a persistent strongly bearish trend band since early March. NRG Energy is down ~23% over six months to $138.11, sitting in mildly bearish. These established power providers — once the primary beneficiaries of the AI electricity narrative — are being repriced as the market grows skeptical that datacenter load growth translates directly into margin expansion for utilities. In that context, FLNC's hyperscaler-contracted storage story represents a more direct and defensible claim on the same capex cycle.
The structural divergence in plain terms
FLNC has contract-secured backlog, hyperscaler relationships, and near-term revenue visibility — but carries post-squeeze consolidation risk and a track record of lumpy quarterly delivery. EOSE has resolved its existential funding risk and owns a differentiated zinc chemistry, but faces execution-versus-guidance scrutiny and near-certain dilution. SMR has regulatory credibility but no commercial contracts, a history of cost overruns at scale, and a decade-plus commercialization timeline. The three names share the same demand thesis but represent fundamentally different risk profiles and time horizons within it.