

AI Interconnect Sub-Layer: NVT, CRDO, and APH Emerge as Runway Names
Prompt v1.0
With optical peers AAOI and LITE already blown off 200–300% in 90 days, the actionable gradual-uptrend stories in the AI server/interconnect sub-layer are narrowing to three: NVT (power/cooling infrastructure, 48% 90-day move with 6–18% PT upside still intact), CRDO (PCIe/AEC retimer franchise, 53% 90-day move with ~10% PT upside and DustPhotonics optical optionality), and APH (connector compounder, -11% 90-day pullback against record fundamentals, ~32% upside to median PT). DELL is confirmed blown-off (+115% in 90 days), SMCI remains structurally impaired, and ALAB is high-quality but re-rated.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
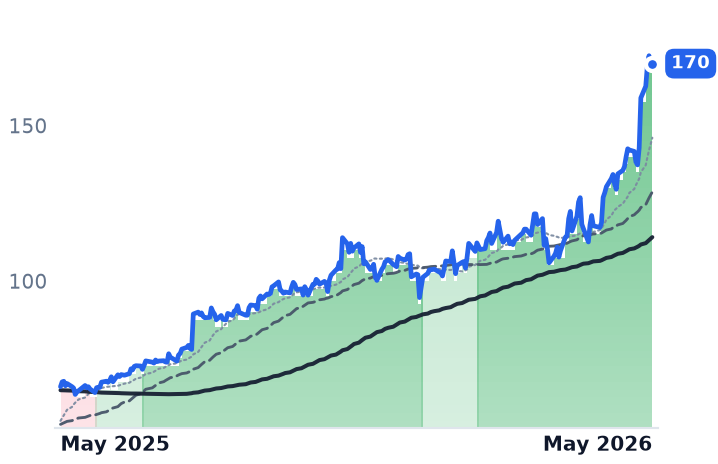
NVT | nVent Electric | Power Distribution Systems | 🟢 Cont. Bull | +30.4% | +157.4% |
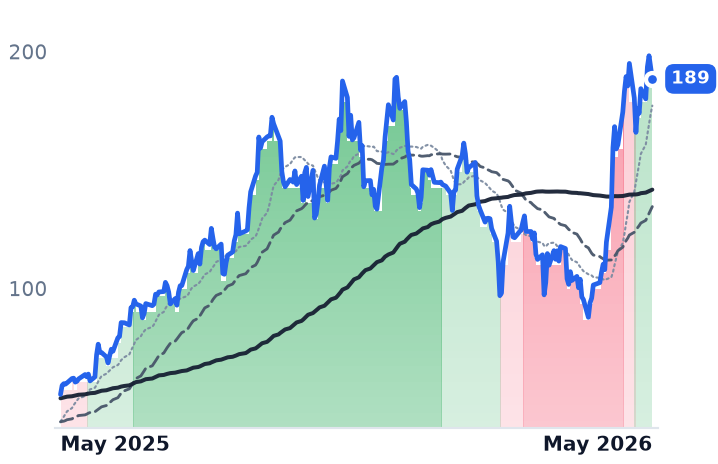
CRDO | Credo Technology | Data Center & Networking | ⚠️ Emerging Bear | +57.6% | +241.3% |
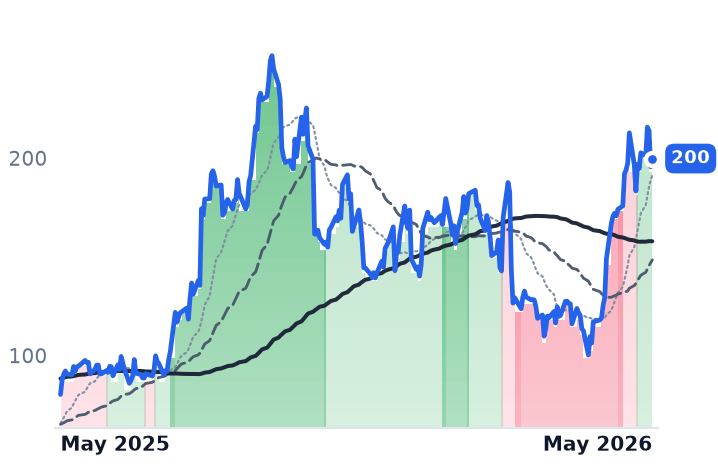
ALAB | Astera Labs | Data Center & Networking | ⚠️ Emerging Bear | +34.0% | +148.9% |
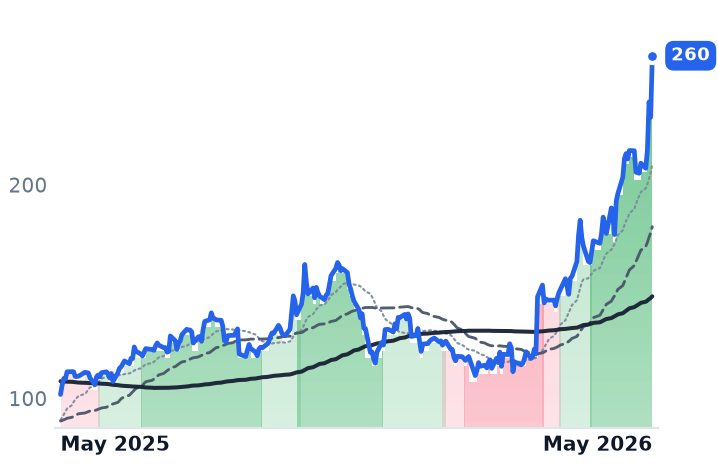
DELL | Dell Technologies | Enterprise Servers | 🟢 Cont. Bull | +46.9% | +155.7% |
APH | Amphenol | Connectors & Substrates | 🟢 Cont. Bull | −9.0% | +52.7% |
SMCI | Super Micro Computer | Enterprise Servers | 🔴 Cont. Bear | +40.0% | +5.5% |
AAOI | Applied Optoelectronics | Optical Networking | 🟢 Cont. Bull | −1.1% | +716.6% |
LITE | Lumentum | Optical Networking | 🟢 Cont. Bull | +0.7% | +1159.5% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NVT | $18.2B | 26.8x | 20.9x | 3.4x | 3.1x | 9.4x | 8.6x | 16.5x | 3.5% |
CRDO | $43.0B | 88.0x | 37.3x | 32.2x | 17.5x | 47.3x | 25.7x | 82.0x | 0.9% |
ALAB | $62.5B | 168.0x | 91.3x | 52.0x | 32.7x | 69.2x | 43.6x | 186.8x | 0.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DELL | $373.9B | 32.2x | 21.7x | 2.5x | 1.9x | 12.5x | 9.7x | 21.6x | 2.3% |
APH | $214.4B | 41.4x | 32.7x | 7.4x | 6.0x | 19.2x | 15.7x | 24.4x | 2.2% |
SMCI | $26.8B | 11.4x | 9.6x | 0.7x | 0.4x | 6.3x | 3.7x | 8.5x | -26.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AAOI | $5.9B | n/m | 93.3x | 9.8x | 5.6x | 34.0x | 19.3x | n/m | -7.0% |
LITE | $74.1B | n/m | 37.6x | 24.6x | 11.7x | 59.0x | 28.1x | n/m | 0.7% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
NVT | Revenue | +51.0% | +30.6% | +14.3% |
| EPS | +61.3% | +30.2% | +20.4% | |
CRDO | Revenue | +211.9% | +85.0% | +49.7% |
| EPS | +423.2% | +86.8% | +48.2% | |
ALAB | Revenue | +129.5% | +61.3% | +29.7% |
| EPS | +124.4% | +62.4% | +27.3% | |
DELL | Revenue | +16.2% | +73.9% | +20.9% |
| EPS | +27.3% | +159.7% | +19.4% | |
APH | Revenue | +55.3% | +18.5% | +12.8% |
| EPS | +61.0% | +22.8% | +14.1% | |
SMCI | Revenue | +77.7% | +69.8% | +17.7% |
| EPS | +33.5% | +54.7% | +23.3% | |
AAOI | Revenue | +131.7% | +182.3% | +72.7% |
| EPS | −327.3% | +650.0% | +92.2% | |
LITE | Revenue | +83.9% | +110.8% | +57.6% |
| EPS | +314.0% | +164.8% | +61.2% |
Forward fiscal years only. Blank means no analyst coverage for that year.
What's Happening
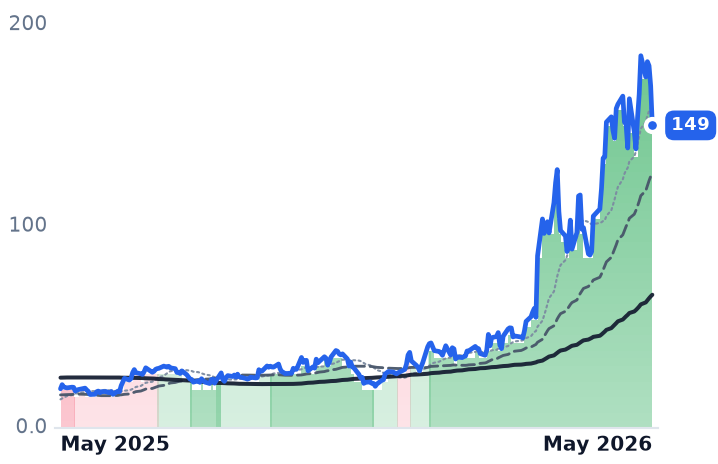
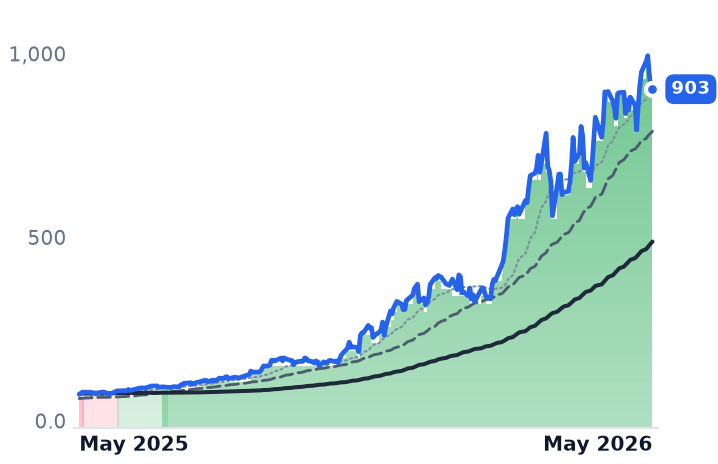
The AI server/interconnect investment landscape has bifurcated sharply over the past 90 days. Optical leaders have already captured their largest moves — AAOI surged from ~$48 to ~$149 (+211%) and LITE from ~$577 to ~$904 (+57%) over the same window, leaving little "gradual uptrend" thesis remaining. Meanwhile, several power-delivery, connector, and retimer names have been moving in a more measured cadence — or pulling back outright — even as their fundamental underpinnings accelerate.
NVT: The Clearest Gradual Follower
nVent Electric posted a historically strong Q1 2026: record sales of $1.242B (+53% YoY, +34% organic), adjusted EPS of $1.09 versus $0.64 consensus — a 70% beat — and a backlog that tripled year-over-year to $2.6B. The company raised full-year 2026 EPS guidance to $4.45–$4.55 on $4.9–$5.0B revenue. Data center infrastructure (liquid cooling, enclosures, power management) now represents over 55% of total sales, up from 12% at spin-off, with that segment growing 80%+ organically in Q1.
The price response has been sustained but not parabolic: NVT moved from $114.62 to $169.95 over 90 days (+48.3%), including a 30-day surge of +32.1% following earnings. After the blowout Q1 report, at least six Wall Street firms raised price targets, with RBC lifting to $180, UBS to $200, and Roth Capital to $185, all citing AI data center demand and backlog momentum. At ~$170, consensus post-earnings PT range of $180–$200 implies 6–18% further upside. Forward P/E of ~37x is premium but grounded in 21–23% organic growth guidance — well below the multiples commanded by optical blowoff peers.
CRDO: Parabolic but Thesis Intact
Credo Technology has delivered the group's strongest 90-day move (+53%, from $123 to $188), yet the fundamental thesis continues to expand rather than exhaust. Q3 FY26 revenue came in at $407M (+201% YoY) with non-GAAP gross margins of 68.5%, and Q4 guidance of $335–$345M implies the company remains on track for >170% full-year FY26 growth exceeding $1.3B.
On the product side, Credo's Toucan PCIe retimer achieved PCI-SIG compliance at 32.0 GT/s for PCIe 6.0 in February 2026, and the Blue Heron 224G AI scale-up retimer launched targeting UALink, ESUN, and Ethernet protocols on a 3nm process. The company confirmed PCIe Gen 5 and Gen 6 retimer design wins across five hyperscaler AEC customers, each representing >10% of revenue. The PCIe retimer market is projected to reach $2.8B by 2033 at an 11.5% CAGR, while CRDO's scale-up networking TAM could top $40B by 2030.
The $750M DustPhotonics acquisition adds silicon photonics PIC capability in-house, with optical revenues expected to exceed $500M in fiscal 2027; Needham maintained its Buy/$220 PT post-announcement. Consensus PT of ~$208 implies ~10% further upside from current $188 — modest, but the DustPhotonics optionality is not yet in most models.
APH: Pulled Back, Fundamentals Unbroken
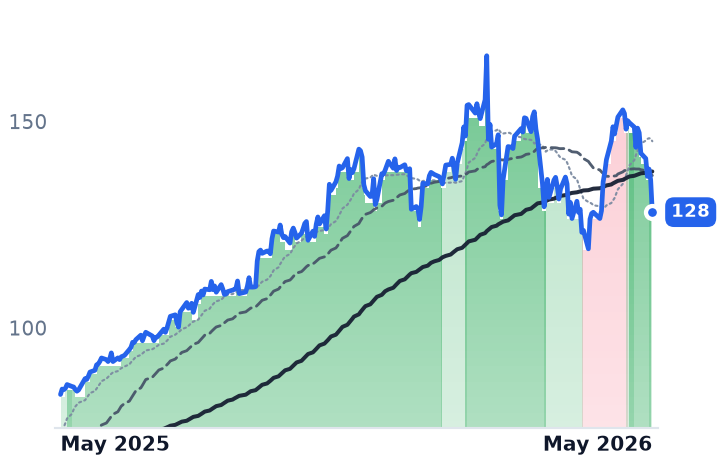
Amphenol is the outlier in this set: the stock has declined 11.2% over 90 days (from $144 to $128) even as its fundamental metrics hit records. Q1 2026 saw sales of $7.62B (+58% YoY, +33% organic), adjusted EPS of $1.06 (+68% YoY), and a book-to-bill of 1.24x — indicating orders outpacing shipments. IT datacom (primarily AI-driven) accounted for 41% of revenue, up 99% YoY.
The January 2026 acquisition of CommScope's CCS business for ~$14.8B materially expanded APH's fiber optic interconnect and data center penetration; CCS is expected to contribute $4.1B in FY2026 sales and $0.15 EPS accretion. 23 Wall Street analysts cover APH with a median price target of $169 (range $135–$210), with an overall Strong Buy consensus, implying ~32% upside from $128 — well above the 15% hurdle set in the hypothesis screen.
Exclusions and Why
DELL is a confirmed blown-off name: the stock surged from $121 to $260 (+115%) over 90 days. Goldman Sachs raised its Dell price target to $215 with a Buy rating in April 2026, but at $260, the stock has already blown through most targets. Dell's Q4 FY26 AI server revenue surged 342% YoY, and the CFO confirmed the pipeline 'has never been higher', but the upside cadence is no longer "gradual."
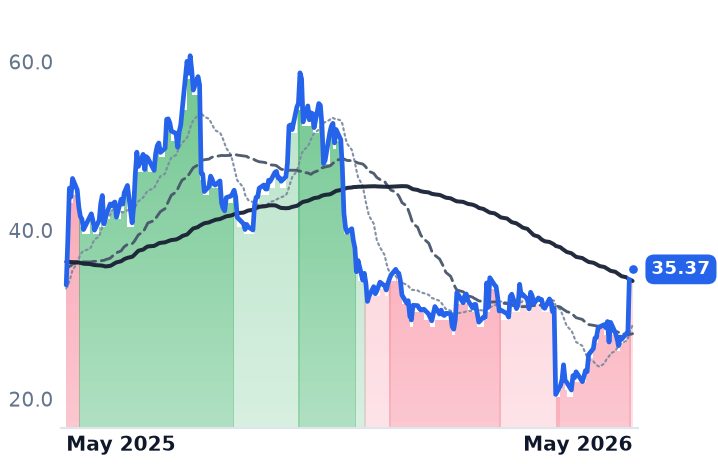
SMCI remains structurally impaired. The stock is up only 5.5% over 90 days, but that masks a trough of $23.22 in late March before a partial recovery. Gross margins collapsed to 6.4% in Q2 FY26 (vs. historical 14–17% targets), and FY26 full-year guidance remains single-digit. SMCI also faces a federal export-control overhang following U.S. charges for allegedly smuggling AI technology to China, adding legal risk to an already-compressed margin structure.
ALAB is high-quality but recently re-rated: Astera Labs reported Q1 2026 revenue of $308M (+93% YoY) with Q2 guidance of $355–$365M, but the stock's 90-day path (peak $188 → trough $100 → back to $200) reflects a sharp post-earnings re-rating rather than gradual accumulation. Forward P/E of ~67x and P/S of ~22x leave limited cushion if execution falters.
Bottom Line
NVT, CRDO, and APH are the three names in the AI server/interconnect sub-layer where the combination of confirmed hyperscaler/platform catalysts, sustained (not single-day) price moves, and intact sell-side PT upside remains most coherent. NVT is the cleanest gradual-uptrend story with the largest backlog acceleration; CRDO has the strongest revenue growth momentum and optical expansion optionality; APH offers the most PT upside from a position of fundamental strength and post-acquisition scope.