

AI Memory Leaders Are Blown Off — The Runway Is in the Second Tier
Prompt v1.0
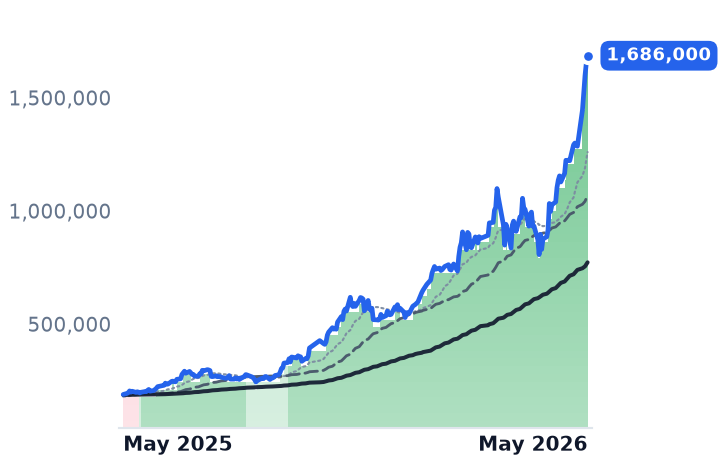
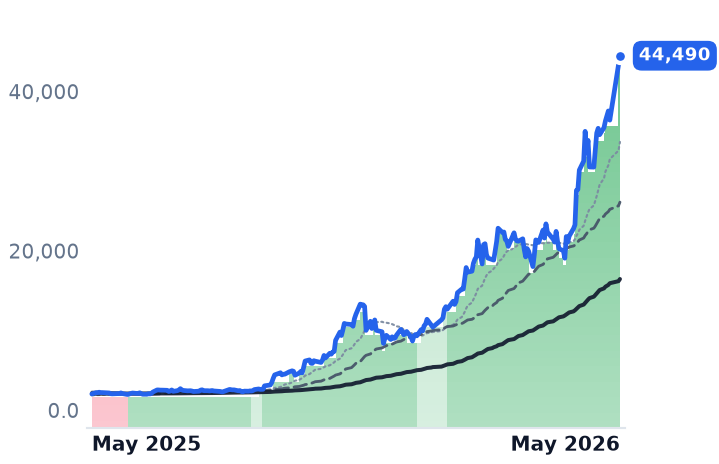
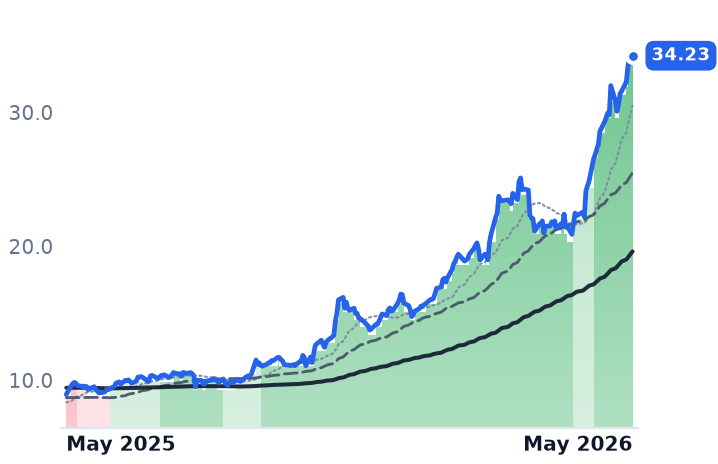
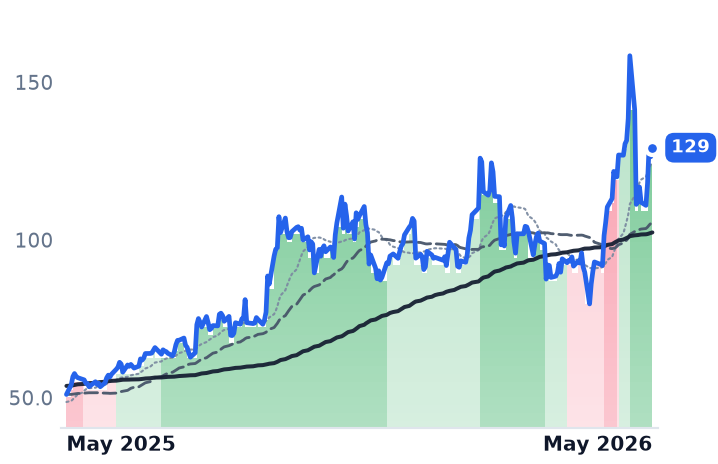
The headline AI memory names (SNDK +161%, SK Hynix +96%, MU +82%, STX +92% over 90 days) have already re-rated violently, with consensus price targets implying little-to-negative upside from current levels. The structural HBM/DRAM pricing cycle remains intact, but the actionable momentum has shifted to the packaging and controller tier: AMKR, ASX, and RMBS are showing sustained 30–44% moves over 90 days — gradual, not blowoff — with structural AI infrastructure demand still building.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
MU | Micron Technology | Memory (DRAM/NAND) | 🟢 Cont. Bull | +77.2% | +771.9% |
WDC | Western Digital | Data Storage Devices | 🟢 Cont. Bull | +42.1% | +993.1% |
STX | Seagate Technology | Data Storage Devices | 🟢 Cont. Bull | +56.3% | +728.3% |
SNDK | Sandisk | Specialty Manufacturing & Components | 🟢 Cont. Bull | +83.5% | +4039.7% |
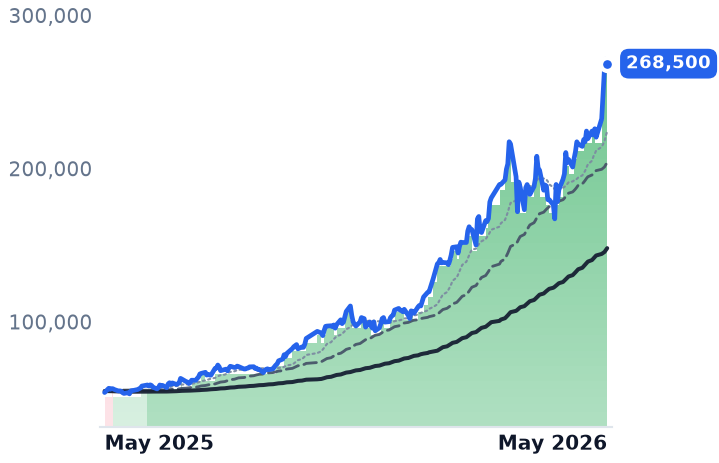
000660.KS | SK hynix | Semiconductors | 🟢 Cont. Bull | +68.9% | +792.1% |
285A.T | Kioxia | Hardware, Equipment & Parts | 🟢 Cont. Bull | +60.6% | +2074.5% |
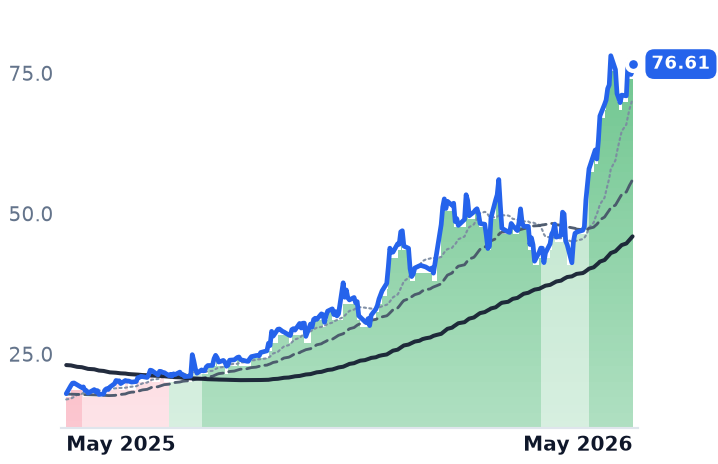
005930.KS | Samsung Electronics | Consumer Electronics | 🟢 Cont. Bull | +31.6% | +398.6% |
AMKR | Amkor Technology | Packaging & Assembly | 🟢 Cont. Bull | +38.9% | +326.9% |
ASX | ASE Technology | Packaging & Assembly | 🟢 Cont. Bull | +39.7% | +282.9% |
RMBS | Rambus | Interconnect & Storage IP | 🟢 Cont. Bull | +22.4% | +153.3% |
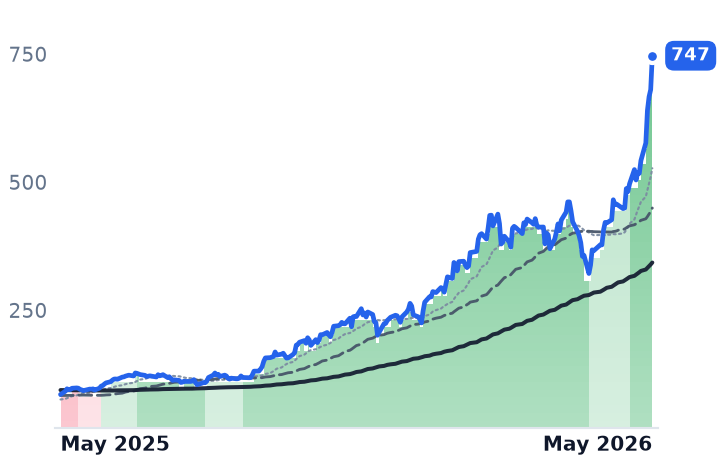
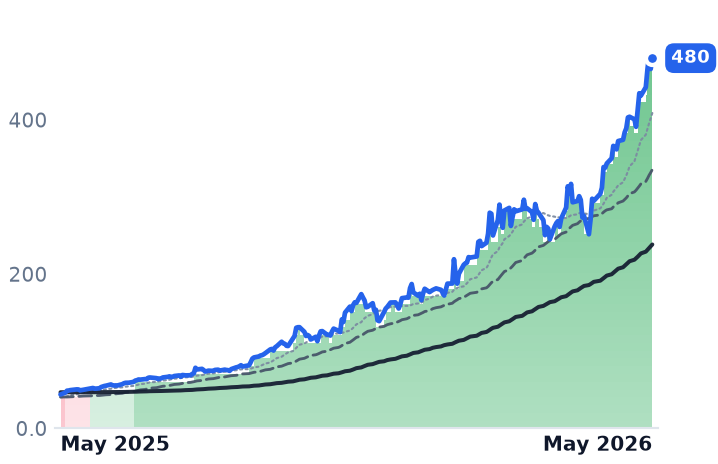
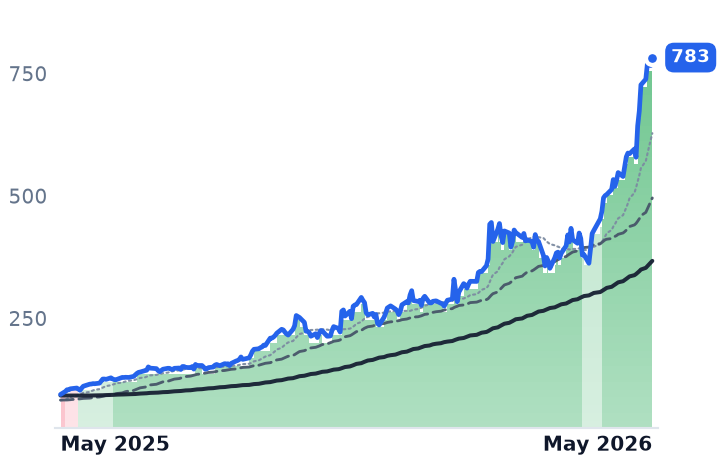
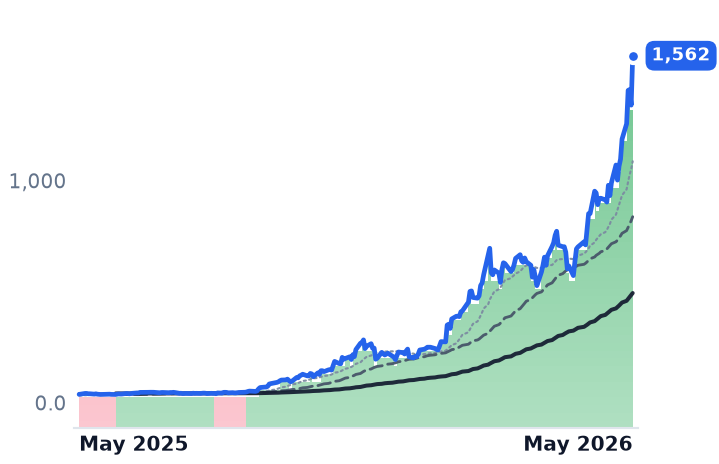
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MU | $1.0T | 19.9x | 12.2x | 11.2x | 7.8x | 15.4x | 10.7x | 14.5x | 2.6% |
WDC | $166.1B | 25.6x | 48.3x | 14.1x | 12.9x | 31.1x | 28.4x | 31.1x | 1.7% |
STX | $178.4B | 73.9x | 53.5x | 16.2x | 14.8x | 39.0x | 35.7x | 53.6x | 1.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SNDK | $208.5B | 46.2x | 21.8x | 15.8x | 10.6x | 28.2x | 19.0x | 37.1x | 2.1% |
000660.KS | $1135.3T | 15.5x | 6.1x | 8.6x | 3.6x | 12.6x | 5.3x | 11.8x | 3.6% |
285A.T | $23.7T | 140.8x | 8.3x | 14.1x | 3.9x | 54.5x | 15.2x | 39.1x | 0.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
005930.KS | $1800.1T | 22.0x | 7.0x | 4.6x | 2.8x | 17.8x | 10.8x | 13.9x | 2.0% |
AMKR | $14.7B | 26.3x | 23.8x | 2.0x | 1.9x | 12.7x | 12.3x | 11.2x | 3.5% |
ASX | $86.9B | 44.3x | — | 3.8x | — | 19.5x | — | 18.9x | -1.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
RMBS | $10.2B | 42.2x | 30.9x | 13.4x | 12.3x | 17.2x | 15.7x | 31.6x | 2.9% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
MU | Revenue | +248.0% | +92.8% | +11.4% |
| EPS | +804.9% | +111.2% | +7.9% | |
WDC | Revenue | +36.9% | +37.2% | +26.5% |
| EPS | +106.2% | +72.8% | +48.0% | |
STX | Revenue | +32.7% | +35.9% | +24.9% |
| EPS | +86.9% | +77.9% | +48.0% | |
SNDK | Revenue | +169.2% | +113.5% | +7.0% |
| EPS | +2283.0% | +167.8% | +5.6% | |
000660.KS | Revenue | +225.0% | +34.1% | +9.7% |
| EPS | +373.8% | +29.8% | +6.7% | |
285A.T | Revenue | +33.2% | +168.7% | +20.3% |
| EPS | +96.3% | +452.8% | +24.1% | |
005930.KS | Revenue | +93.0% | +19.5% | +7.5% |
| EPS | +521.0% | +25.1% | +5.2% | |
AMKR | Revenue | +14.7% | +12.0% | +10.8% |
| EPS | +96.6% | +7.9% | +24.7% | |
ASX | Revenue | +26.2% | +23.7% | +19.7% |
| EPS | +104.8% | +50.1% | +34.1% | |
RMBS | Revenue | +17.3% | +19.6% | +24.8% |
| EPS | +21.5% | +23.6% | +25.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The Violent Leaders: Already Priced
The AI2: Memory & Storage cohort has produced some of the most violent re-ratings in the market over the past 90 days, but the window for gradual entry into the primary names appears closed. SNDK is up ~161% over 90 days, Kioxia (285A.T) +136%, SK Hynix (000660.KS) +96%, Seagate (STX) +92%, and Micron (MU) +82% — all firmly in blowoff territory. WDC is up ~75% over 90 days with a ~40% 30-day sprint that mirrors SNDK's trajectory.
The price target arithmetic underscores the compression. MU consensus sits around $551 (per analyst PT data from TheStreet), implying roughly 4% upside from its current ~$542 level — essentially nothing for a stock that has already moved 82%. STX is even more telling: the stock has run over 600% in the past year, and the median analyst PT of ~$469 sits roughly 38% below the current ~$766 price — consensus sees this as overshot.
MU's fundamentals are genuinely exceptional — Q2 FY2026 revenue of $23.9B beat estimates by 19.5%, EPS of $12.20 beat $9.21 consensus by 32.7%, and Micron was added to the S&P 100 in March 2026, driving passive flows. But the market has absorbed the beat: forward PE is ~11x, not cheap enough to ignore cyclical peak risk, and management itself acknowledged that even at full allocation, it can only fulfill 50–67% of key customer HBM demand — a supply constraint, not a demand signal that argues for further near-term re-rating.
The Macro Backdrop: Still Constructive
The pricing cycle underpinning the entire cohort remains unambiguously strong. TrendForce reported in January 2026 that server DRAM prices were expected to climb more than 60% QoQ in Q1 2026, driven by memory makers prioritizing server applications. The Supplyframe DRAM Price Index for Q2 2026 showed prices 146.3% higher year-over-year, DDR5 server RDIMM prices +49.7% sequentially, and HBM3e capacity locked to AI GPU/ASIC customers through end of year.
On HBM specifically, Samsung and SK Hynix reportedly plan a ~20% HBM3e price hike for 2026, with NVIDIA H200 export approval to China (each GPU uses six HBM3e stacks), Google TPU v7, and Amazon Trainium demand all pulling forward. HBM4 chips are expected to fetch ~$500 each versus ~$300 for HBM3e, and NAND contract prices rose ~10% in Q4 2025 on AI data-center SSD demand. TrendForce also flagged that DDR5 profitability is projected to surpass HBM3e in Q1 2026, creating a capacity reallocation dynamic that could tighten both markets simultaneously.
The key downside risk is real but not imminent: analysts warn that double-digit HBM price declines could materialize in 2027 as HBM4 supply scales and competition intensifies. That's a 2027 problem, not a 2026 story — but it limits the duration of runway for the most cycle-exposed names.
The Gradual Followers: Where the Move Is Intact
Three second-tier names stand out as still in the accumulation phase rather than the exhaust phase:
AMKR (Amkor Technology) is up ~36% over 90 days and ~32% over 30 days — a sustained but non-violent move. Amkor is a direct structural beneficiary of the HBM advanced packaging bottleneck: AMKR and ASX Technology are identified as direct beneficiaries of CoWoS advanced packaging constraints, with SK Hynix and NVIDIA as contracted customers. Amkor has a $7B Arizona facility under construction. An Investor Day is scheduled for May 21, 2026, providing a near-term catalyst. Short interest is 7.2% of float with 3.0 days to cover — manageable, not a crowded squeeze setup.
ASX (ASE Technology) is up ~44% over 90 days and ~38% over 30 days — slightly more extended than AMKR but still below the violent threshold. ASE's 2026 outlook includes double-digit revenue growth with materially widening margins, and it sits alongside Amkor as a primary CoWoS and advanced packaging vendor for the AI chip supply chain.
RMBS (Rambus) is up ~30% over 90 days and ~17% over 30 days — the most gradual of the three. Rambus supplies memory interface chips and IP for AI servers; Q1 2026 saw 15% YoY product revenue growth, and a new SOCAMM2 product targeting AI server LPDDR5X is expected to drive second-half acceleration. There is a meaningful overhang to acknowledge: Rambus disclosed a grand jury subpoena in Q1 2026, which triggered a -21–25% single-day dislocation. The core AI/data-center business continues to grow, but the legal risk is real and warrants monitoring.
SK Hynix: The Middle Case
Samsung (005930.KS) is up ~60% over 90 days and ~30% over 30 days — less violent than its Korean peer SK Hynix, which holds a 62% HBM shipment share as of Q2 2025 and is projected to maintain >50% HBM4 market share through 2026. Samsung trails on HBM execution but is catching up on the DRAM pricing cycle. The move is meaningful but consensus runway from current levels is unclear without updated PT data; it occupies a gray zone between the violent leaders and the gradual followers.
Summary
The HBM/DRAM pricing supercycle is real and the macro data is strong — but that story is now fully reflected in the primary DRAM/NAND names. MU's consensus PT implies ~4% upside; STX's implies 38% downside. The structural infrastructure buildout — advanced packaging, memory interface IP — is still in the accumulation phase across AMKR, ASX, and RMBS, with 30–44% 90-day moves that have not yet crossed into blowoff territory.