

BTC Miners' AI/HPC Pivot Is a Cohort Re-Rating, Not Crypto Beta
Prompt v1.0
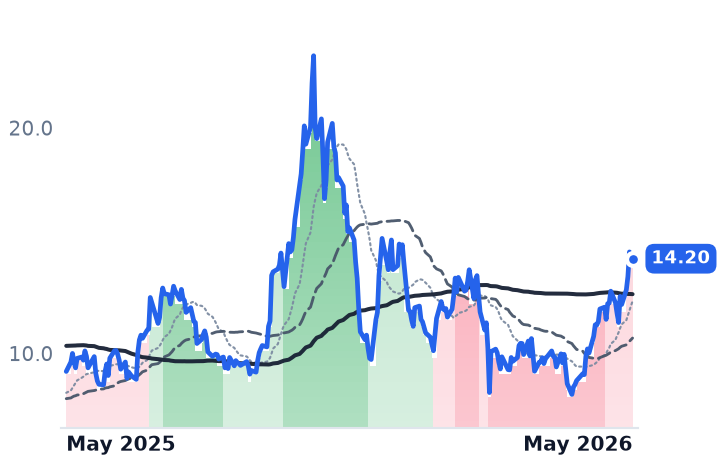
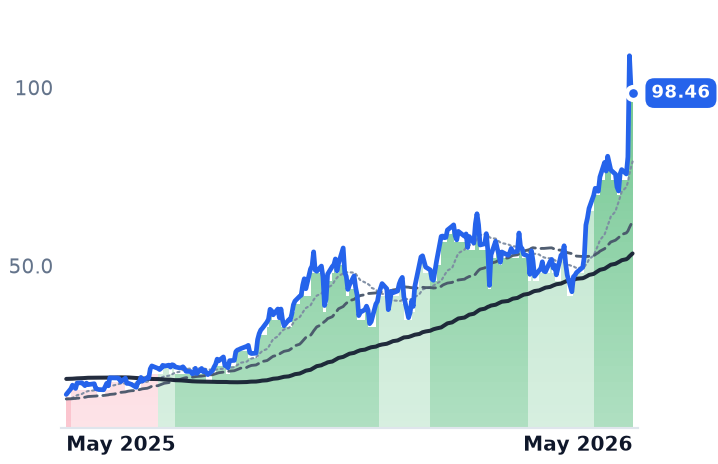
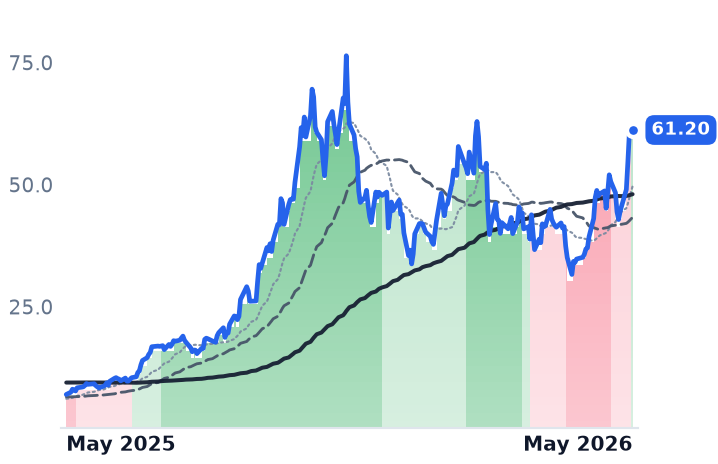
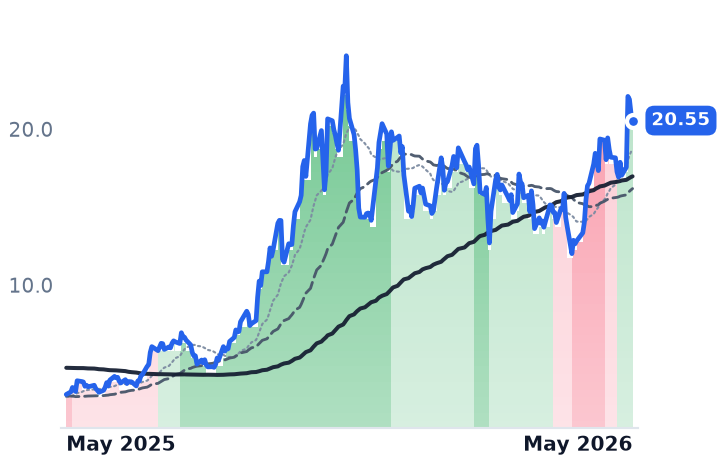
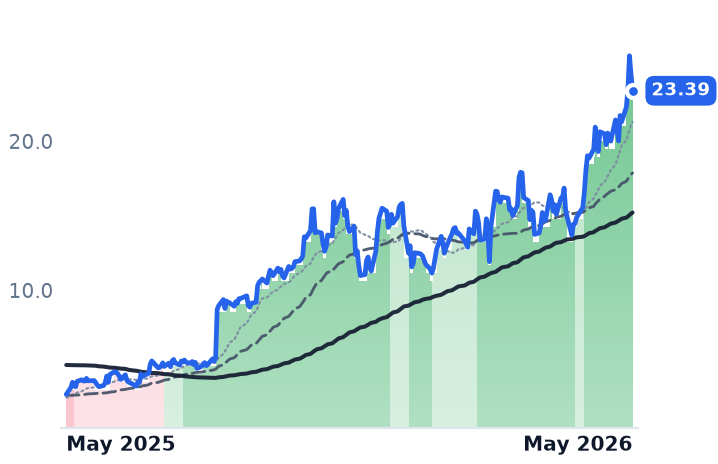
Bitcoin miners are beating BTC itself by 60-80 percentage points year-to-date as the market re-rates them as AI/HPC infrastructure operators. BITF/KEEL's ~86% 1-month surge is confirmed as a sector-wide move — with HUT +49%, IREN +56%, WULF +24%, and CIFR +24% over the same window — driven by signed hyperscaler leases across peers and KEEL's own narrative re-brand, even as KEEL itself has yet to sign a single HPC contract.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
BITF | Bitfarms | Financial - Capital Markets | ⚠️ Emerging Bear | +89.0% | +267.6% |
KEEL | Keel Infrastructure | Data Center & Cloud Infrastructure | ⚠️ Emerging Bear | +89.0% | +267.6% |
RIOT | Riot Platforms | Bitcoin Mining | ⚠️ Emerging Bear | +44.3% | +184.0% |
MARA | Marathon Digital | Bitcoin Mining | 🔴 Cont. Bear | +33.8% | −17.9% |
CLSK | CleanSpark | Asset Management - Cryptocurrency | ⚠️ Emerging Bear | +39.2% | +54.3% |
HUT | Hut 8 | Bitcoin Mining | 🟢 Cont. Bull | +55.3% | +608.9% |
IREN | IREN | Digital Assets & Blockchain | ⚠️ Emerging Bear | +65.1% | +769.3% |
CIFR | Cipher Mining | Bitcoin Mining | 🟢 Cont. Bull | +25.6% | +589.6% |
WULF | TeraWulf | Bitcoin Mining | 🟢 Cont. Bull | +22.9% | +677.1% |
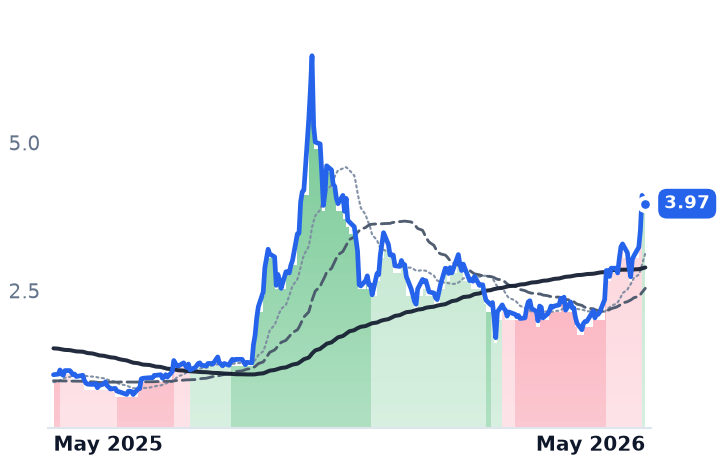
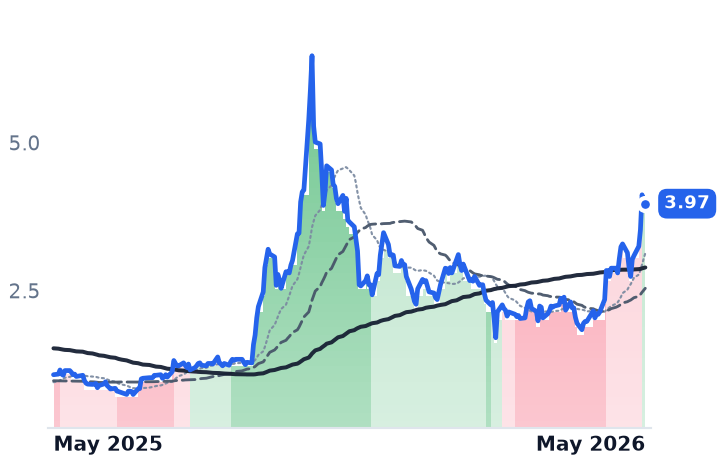
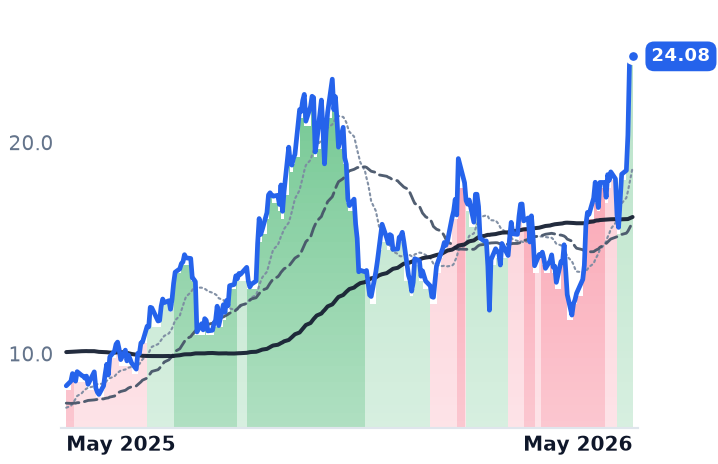
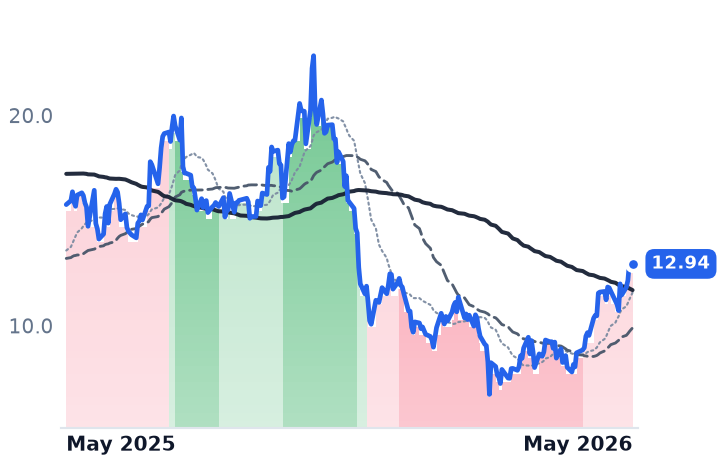
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BITF | $1.3B | n/m | — | 6.5x | 11.6x | — | — | n/m | -25.8% |
KEEL | $1.9B | n/m | — | 12.6x | 17.1x | — | — | n/m | -18.6% |
RIOT | $7.7B | n/m | — | 11.3x | 11.7x | — | — | n/m | -11.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MARA | $3.7B | n/m | — | 4.6x | 4.3x | — | — | n/m | -42.4% |
CLSK | $3.4B | n/m | — | 4.5x | 5.2x | 23.6x | 27.1x | 23.9x | -31.9% |
HUT | $10.0B | n/m | — | 34.4x | 33.6x | 136.1x | 133.0x | 228.7x | -7.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
IREN | $13.5B | 948.3x | — | 17.9x | 4.8x | 33.4x | 8.9x | 32.1x | -13.4% |
CIFR | $7.0B | n/m | — | 36.8x | 32.4x | — | — | n/m | -21.3% |
WULF | $8.3B | n/m | — | 50.2x | 30.2x | 89.1x | 53.5x | n/m | -30.2% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
BITF | Revenue | −59.0% | +43.2% | +251.4% |
| EPS | +8.9% | −40.1% | −547.2% | |
KEEL | Revenue | −59.1% | +12.9% | +81.9% |
| EPS | +59.7% | −46.8% | +71.4% | |
RIOT | Revenue | +0.1% | +20.6% | +15.0% |
| EPS | +453.3% | −59.3% | −36.7% | |
MARA | Revenue | −11.4% | +20.3% | −23.2% |
| EPS | +227.3% | −65.4% | −244.5% | |
CLSK | Revenue | −16.7% | +22.0% | +6.7% |
| EPS | −347.9% | −78.2% | −697.2% | |
HUT | Revenue | +23.6% | +91.9% | +153.5% |
| EPS | −1503.4% | −29.1% | −122.5% | |
IREN | Revenue | +38.3% | +300.2% | +91.3% |
| EPS | −1004.3% | −68.5% | −1007.5% | |
CIFR | Revenue | −13.0% | +266.6% | +20.9% |
| EPS | +275.5% | −77.9% | −109.0% | |
WULF | Revenue | +54.7% | +233.2% | +79.8% |
| EPS | +51.9% | −89.0% | −265.7% |
Forward fiscal years only. Blank means no analyst coverage for that year.
What's happening
The BTC miner cohort has violently decoupled from spot bitcoin. Over the trailing 30 days, BITF/KEEL gained ~86% (from $2.14 to $3.97), HUT gained ~49% (from $66.08 to $98.46), and IREN gained ~56% (from $39.32 to $61.20) — all while BTC-USD moved only ~10% (from $72,979 to $80,293) in the same window. Zooming out, BTC-USD is down roughly 22% from its $103K six-month high, yet all 10 of the largest publicly traded Bitcoin mining companies are positive year-to-date in 2026, with gains up to 85%+. This is not crypto beta. It is an infrastructure re-rating.
The catalyst stack: peers are signing, KEEL is pitching
The re-rating has specific, verifiable operational anchors across the cohort — but they are unevenly distributed.
Hut 8 secured a $9.8 billion, 15-year, 352 MW lease at its Beacon Point AI campus on triple-net, take-or-pay terms, tripling its contracted AI capacity to 597 MW — the primary driver of HUT's 35%+ single-day surge on May 6. Riot Platforms reported Q1 2026 data center revenue of $33.15M, with CEO Jason Les calling it "a definitive inflection point for Riot, as we officially transitioned into an active, revenue-generating data center operator"; AMD also exercised an option to double its Rockdale footprint to 50 MW with options for an additional 150 MW. TeraWulf has locked $12.8 billion in HPC contracts and is up 73-85% year-to-date. IREN holds a $9.7 billion AI cloud contract with Microsoft, deploying 140,000 GPUs across 200 MW of Childress data centers targeting $3.4 billion in annualized run-rate revenue, and secured $3.6 billion in GPU financing from Goldman Sachs and JPMorgan at under 6% interest. CleanSpark is in advanced discussions with a direct investment-grade hyperscaler, per Needham, which raised its price target to $18.
KEEL is a different story. Bitfarms officially rebranded as Keel Infrastructure Corp. and completed its U.S. redomiciliation from Canada to Delaware, with the KEEL ticker beginning trading on April 6, 2026. CEO Ben Gagnon declared "We are no longer a Bitcoin company, we are an infrastructure-first owner and developer for HPC/AI data centers across North America", with shareholders voting over 99% in favor. Chardan initiated coverage with a Buy rating spotlighting the shift to HPC and AI. Notably, a widely-cited claim about a "major long-term government infrastructure contract" was corrected as a press error — no such contract exists.
KEEL completed its Latin American exit, selling its 70 MW Paso Pe (Paraguay) site in April 2026 for ~$13M (revised down from $30M due to declining BTC mining economics), giving it a 100% North American portfolio: Panther Creek (350+ MW), Sharon (110 MW), Moses Lake WA (18 MW), Quebec (170 MW), and Scrubgrass (up to 1+ GW, 2028+).
The valuation gap: pre-lease vs. post-lease
KEEL currently trades at approximately $1.9M per available 2027 megawatt — squarely in the bitcoin miner valuation range of $1.7–2.1M/MW — while companies that have signed leases trade at $4–6M/MW. That is a 2–3x potential re-rating upon lease execution. Management targets permitting completion by mid-to-late summer 2026 and first lease execution before year-end, with revenue delivery targeted for 2027.
KEEL has $520M in cash and Bitcoin on hand after issuing $588M in convertible notes (with 125% capped calls cash-settled at $11.88/share, limiting economic dilution to that level) and repaying the Macquarie debt facility. The current ratio is ~3.1 and D/E is ~0.11, suggesting runway to reach lease milestones without a near-term equity raise. That said, the share count grew ~63% from Q1 2024 to FY2025 (338.7M to 551.7M diluted shares), reflecting significant prior-period dilution that already weighs on per-share math.
Why the fundamentals are not there yet — and why that matters
KEEL's FY2025 net loss was $284.5M on $229M revenue (net margin -124%), and gross profit was -$18.9M (-8.2% gross margin), reflecting the transitional cost of winding down BTC mining while HPC revenue has not yet commenced. The company is pre-revenue in HPC — a category where peers like IREN (forward FY2026 consensus revenue ~$942M, +84% YoY) and RIOT ($33M quarterly data center revenue already on the books) are already monetizing.
The structural backdrop is real: hyperscalers and neoclouds are locking in 24–36 month supply agreements because new power generation cannot come online fast enough. KEEL's pre-permitted 2.2 GW pipeline has genuine strategic value in that environment. But the stock's ~86% 1-month surge is a narrative re-rating — the market is pricing in a scenario that requires lease execution by late 2026 and site delivery in 2027 to be justified. Until then, KEEL remains a high-optionality, pre-revenue story in a cohort where several peers have already crossed the operational threshold.