

AI-Power Turnaround Cohort: Real Catalysts, Extreme Valuations, Vertical Spikes
Prompt v1.0
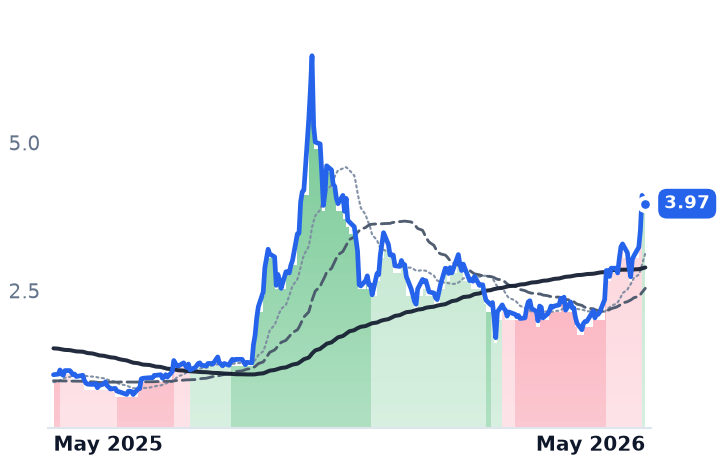
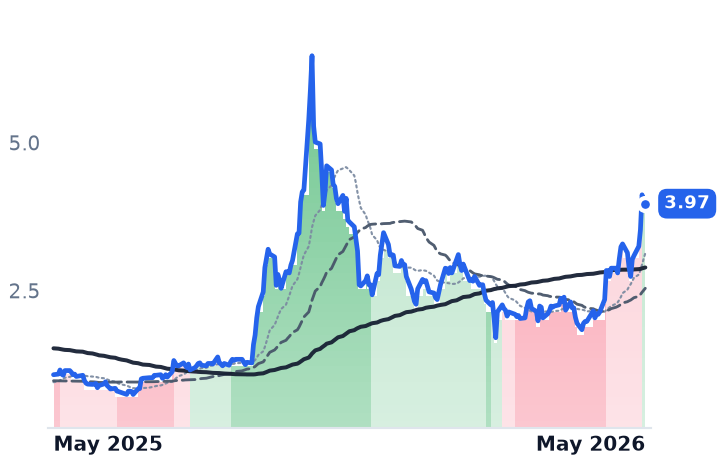
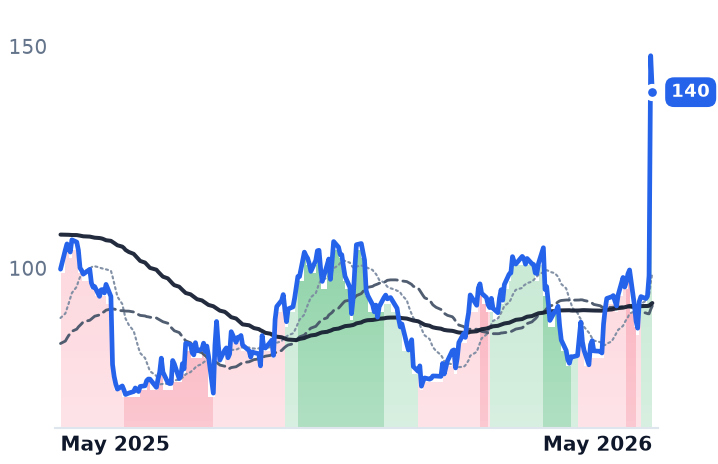
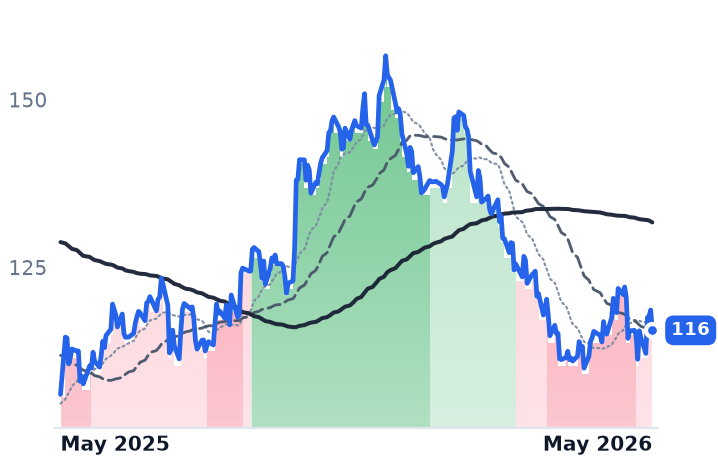
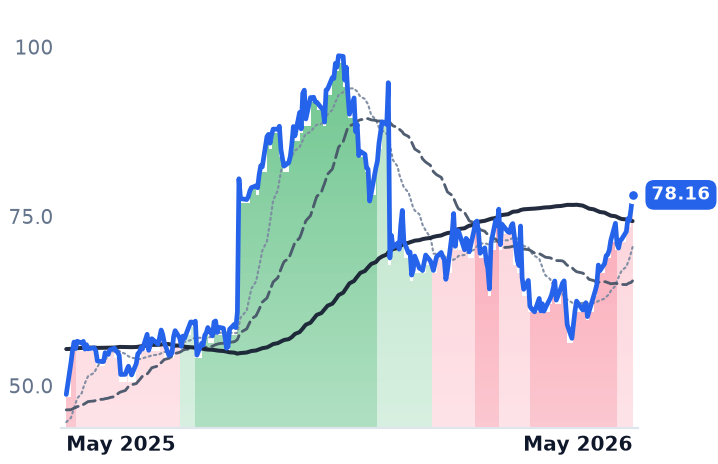
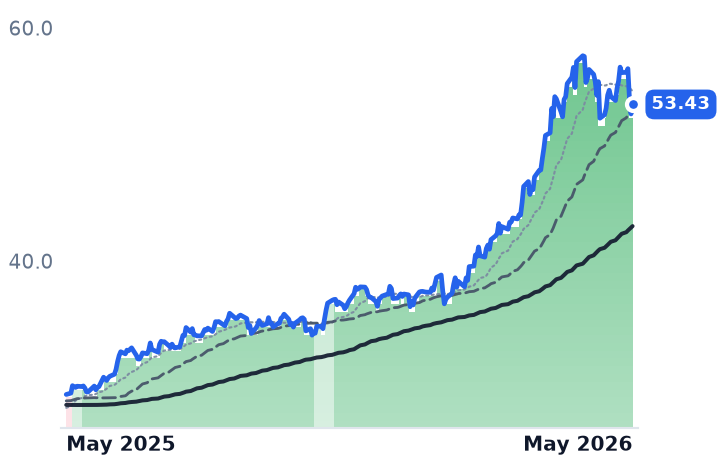
WOLF, FCEL, BITF/KEEL, and BE are all rallying on genuine AI-datacenter power catalysts — not generic short squeezes — but every move is a vertical spike in early May 2026, not a gradual multi-leg recovery. Fundamentals remain deeply challenged for most names, and valuations are extreme relative to current revenue and profitability.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
AI | C3.ai | AI & Enterprise Software | 🔴 Cont. Bear | +15.0% | −57.8% |
WOLF | Wolfspeed | Discrete & Power | 🌱 Emerging Bull | +90.7% | +110.9% |
FCEL | FuelCell Energy | Fuel Cell & Hydrogen | 🌱 Emerging Bull | +109.2% | +220.1% |
BE | Bloom Energy | Fuel Cell & Hydrogen | 🟢 Cont. Bull | +63.0% | +1381.4% |
BITF | Bitfarms | Financial - Capital Markets | ⚠️ Emerging Bear | +89.0% | +267.6% |
KEEL | Keel Infrastructure | Data Center & Cloud Infrastructure | ⚠️ Emerging Bear | +89.0% | +267.6% |
STRL | Sterling Infrastructure | Infrastructure & Civil Construction | 🟢 Cont. Bull | +93.9% | +375.3% |
FLEX | Flex | Electronic Manufacturing Services | 🟢 Cont. Bull | +89.5% | +269.5% |
AAON | AAON | HVAC Systems | 🌱 Emerging Bull | +53.9% | +40.0% |
A | Agilent Technologies | Life Sciences Instruments & Consumables | ⚠️ Emerging Bear | +0.2% | +9.0% |
P | Everpure | Other | ⚠️ Emerging Bear | +29.9% | +60.5% |
E | Eni S.p.A | Upstream Exploration & Production | 🟢 Cont. Bull | −4.0% | +87.1% |
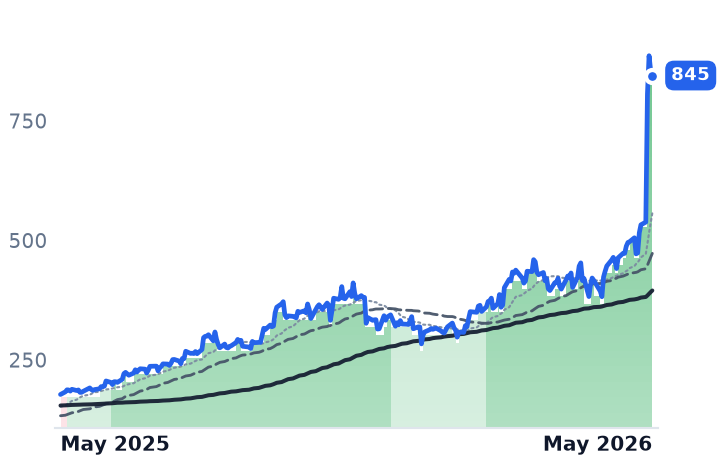
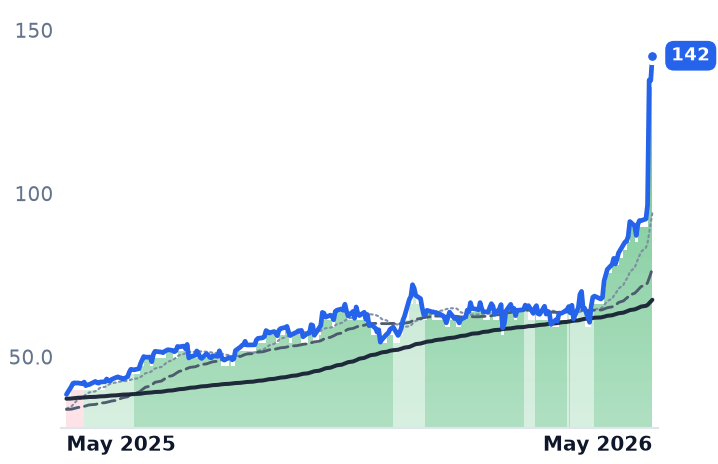
12-month price & trend
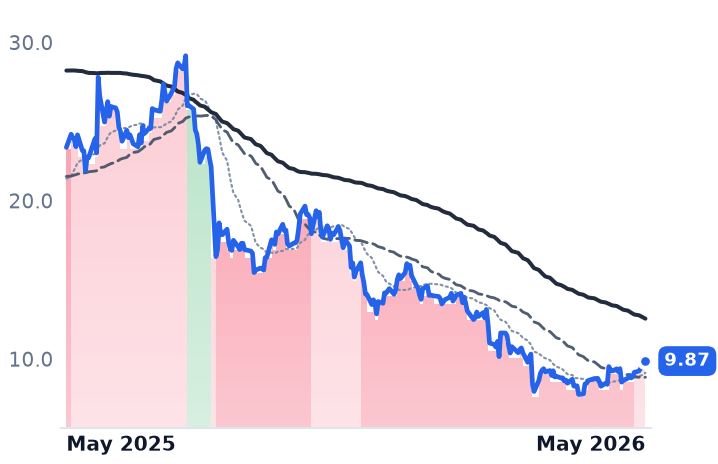
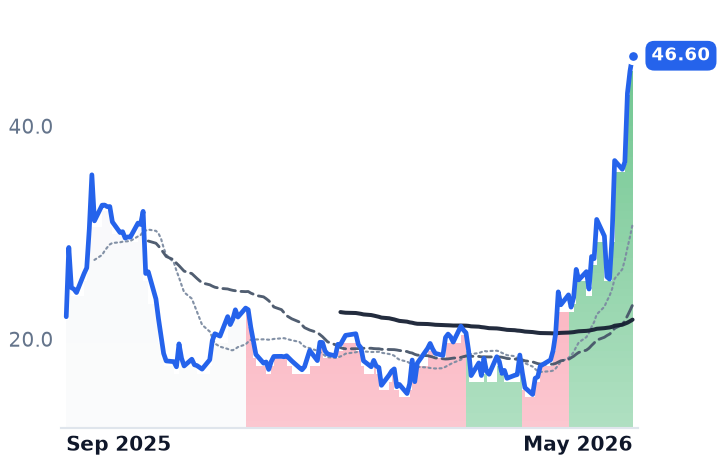
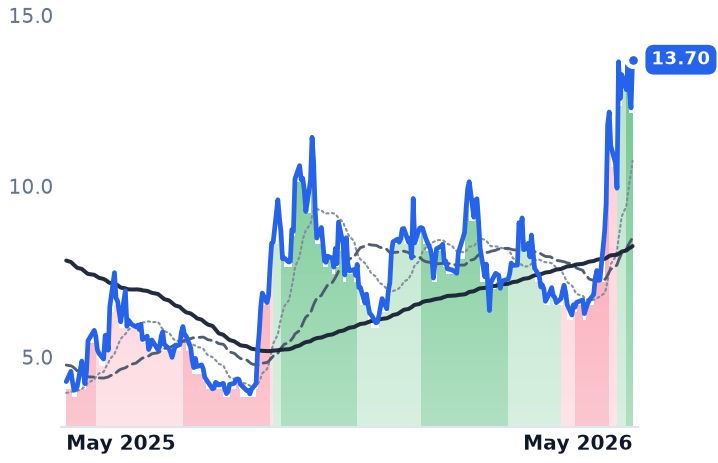
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AI | $1.4B | n/m | — | 5.4x | 6.0x | 17.5x | 19.6x | n/m | -14.1% |
WOLF | $1.7B | n/m | — | 2.4x | 2.6x | — | — | n/m | -43.9% |
FCEL | $1.1B | n/m | — | 6.7x | 7.0x | — | — | n/m | -11.6% |
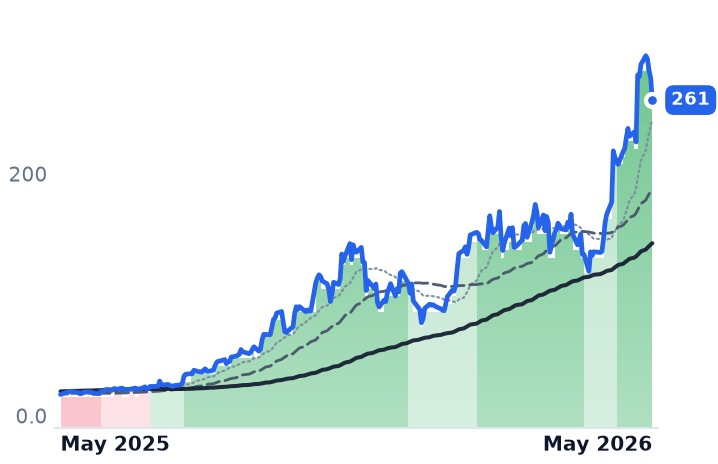
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BE | $67.7B | 275.0x | 87.8x | 21.7x | 16.7x | 69.6x | 53.5x | 194.0x | 0.9% |
BITF | $1.3B | n/m | — | 6.5x | 11.6x | — | — | n/m | -25.8% |
KEEL | $1.9B | n/m | — | 12.6x | 17.1x | — | — | n/m | -18.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
STRL | $18.3B | 52.7x | 31.6x | 6.3x | 4.9x | 27.3x | 21.0x | 30.8x | 2.4% |
FLEX | $48.0B | 50.2x | 27.7x | 1.6x | 1.4x | 17.3x | 14.6x | 26.9x | 2.2% |
AAON | $11.1B | 93.8x | 61.7x | 6.9x | 5.5x | 26.2x | 21.0x | 44.5x | -1.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
A | $31.6B | 24.5x | 18.7x | 4.5x | 4.3x | 8.6x | 8.2x | 18.2x | 3.1% |
P | $27.0B | 142.6x | 28.8x | 7.4x | 5.3x | 10.5x | 7.6x | 70.4x | 0.9% |
E | $81.7B | 27.6x | 10.4x | 0.9x | 0.9x | 19.0x | 18.8x | 8.0x | 4.3% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
AI | Revenue | −35.5% | −10.4% | +10.1% |
| EPS | +213.4% | −43.4% | −42.7% | |
WOLF | Revenue | +0.7% | −14.8% | +24.1% |
| EPS | +275.2% | −30.1% | −11.8% | |
FCEL | Revenue | +8.2% | +42.4% | +55.0% |
| EPS | −74.3% | −12.0% | −47.7% | |
BE | Revenue | +112.4% | +65.1% | +46.0% |
| EPS | +374.5% | +83.5% | +60.7% | |
BITF | Revenue | −59.0% | +43.2% | +251.4% |
| EPS | +8.9% | −40.1% | −547.2% | |
KEEL | Revenue | −59.1% | +12.9% | +81.9% |
| EPS | +59.7% | −46.8% | +71.4% | |
STRL | Revenue | +58.0% | +18.5% | +26.4% |
| EPS | +82.4% | +27.3% | +20.2% | |
FLEX | Revenue | +6.8% | +26.3% | +30.0% |
| EPS | +24.2% | +44.7% | +51.5% | |
AAON | Revenue | +44.5% | +15.1% | +21.9% |
| EPS | +55.9% | +53.8% | +35.7% | |
A | Revenue | +6.9% | +6.1% | +6.7% |
| EPS | +7.2% | +10.1% | +11.0% | |
P | Revenue | +20.4% | +15.9% | +9.7% |
| EPS | +17.9% | +23.0% | +19.8% | |
E | Revenue | +9.5% | −6.6% | +2.9% |
| EPS | +72.8% | −9.5% | +2.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
What's Happening
The so-called "second-derivative AI-power" cohort — silicon carbide power semis (WOLF), stationary fuel cells (FCEL, BE), and bitcoin miners pivoting to HPC (BITF/KEEL) — has posted eye-catching returns over the past one to three months. The hypothesis that capital is rotating out of extended infrastructure names (STRL, FLEX, AAON) into previously-left-for-dead power-electronics names is partially correct in its direction but wrong in its framing.
The evidence points to a single coordinated thematic re-rating event in late April / early May 2026, apparently triggered by Bloom Energy's Project Jupiter announcement with Oracle (April 27) and reinforced by Bloom's blowout Q1 2026 earnings print (April 28), which raised full-year guidance to $3.4–$3.8B. Critically, STRL, FLEX, and AAON also spiked violently the same week — STRL from $538 to $844, FLEX from $92 to $142, AAON from $93 to $139 — which undermines the rotation narrative entirely. This was a sector-wide re-rating, not a catch-up trade.
Name-by-Name Breakdown
WOLF (Wolfspeed — SiC Power Semis) The post-bankruptcy balance sheet is genuinely cleaner: approximately $1.3B in cash and $3.7B in debt forgiveness provide a real floor. A Toyota design win and a 300mm SiC wafer manufacturing milestone are concrete industrial achievements. AI-datacenter revenue grew 50% quarter-over-quarter. But the fundamental picture remains broken: FY26 revenue guidance is just $665M (down ~12% year-over-year), gross margins are deeply negative, and the expected net loss is $577M. The rally reflects option value on a restructuring, not current earnings power.
FCEL (FuelCell Energy) FCEL is riding a 275% surge in its pipeline from data center customers and has introduced a new 12.5MW Power Block product aimed squarely at that market. However, Q1 2026 revenue was only $30.5M with negative gross margins, and the trailing FY25 EPS guidance stands at approximately -$2.07. The demand signal is real; the ability to monetize it profitably remains unproven.
BITF/KEEL (formerly Bitfarms — HPC/AI Pivot) KEEL rebranded from Bitcoin miner to HPC/AI infrastructure developer on April 1, 2026, with a 2.2GW pipeline. First leases are targeted for 2026, with meaningful revenue not expected until 2027. Today it generates effectively zero AI-related revenue. This rally is purely narrative-based — the longest duration risk in the cohort by a wide margin.
BE (Bloom Energy) BE is the genuinely de-risked name in the group, trading around $261 with a $62B market cap. The 2.45GW Project Jupiter contract with Oracle and a $14B service backlog are real, contracted revenue anchors. But the price already reflects this: trailing P/E exceeds 12,000x, and forward P/E sits at approximately 122x. BE is no longer a "left-for-dead" turnaround — it is a fully re-rated AI-power infrastructure name.
Why It Matters
The cross-cohort pattern here is instructive. These are not gradual, multi-leg recoveries driven by accumulating fundamental evidence. Every name spiked vertically in a compressed window, which raises the question of durability. When the same week sees both the "laggards" and the "already-extended" names spike simultaneously, the signal is thematic momentum — not fundamental rotation.
Valuation gaps are stark. BITF/KEEL trades at approximately 9.9x trailing price-to-sales on near-zero AI revenue. BE trades at approximately 25x trailing / 17x forward price-to-sales. WOLF and FCEL carry deeply negative gross margins. Against semiconductor peers with positive margins and established customer relationships, these multiples embed significant execution risk.
The Common Thread
The genuine unifying thesis is AI-datacenter power density and grid reliability. Hyperscalers are signing unprecedented power offtake agreements (the Oracle/Bloom Project Jupiter deal being the clearest example), and any company with a credible claim to supplying firm, dispatchable, or high-efficiency power to data centers has been repriced. The debate now is whether that repricing was one event — already complete — or the beginning of a multi-year re-rating as contracts, revenues, and margins follow.