

AI Observability vs. Horizontal SaaS: A Real But Uneven Bifurcation
Prompt v1.0
DDOG, AKAM, and FROG surged 34–42% in five days on genuine Q1 2026 AI-attach earnings beats, while horizontal SaaS peers bleed from multiple compression despite solid fundamentals. The bifurcation is real and earnings-driven — but how much runway remains at current prices differs sharply across the three winners.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
DDOG | Datadog | Data & Analytics Platforms | ⚠️ Emerging Bear | +83.7% | +85.5% |
AKAM | Akamai Technologies | Network & Application Delivery | 🌱 Emerging Bull | +34.8% | +93.7% |
FROG | JFrog | Developer Tools & DevOps | ⚠️ Emerging Bear | +58.7% | +80.9% |
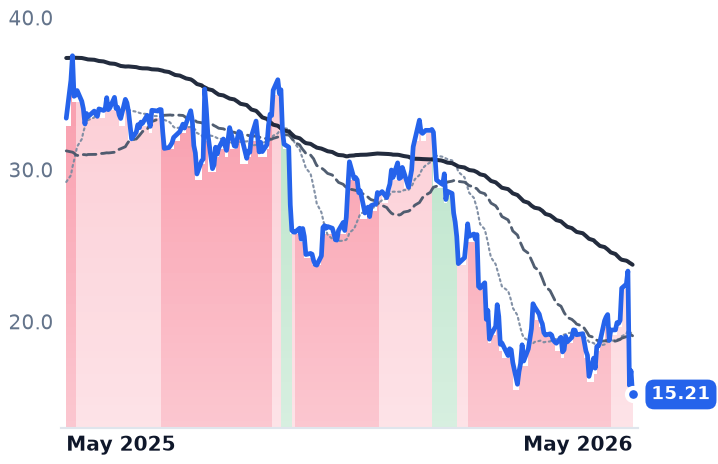
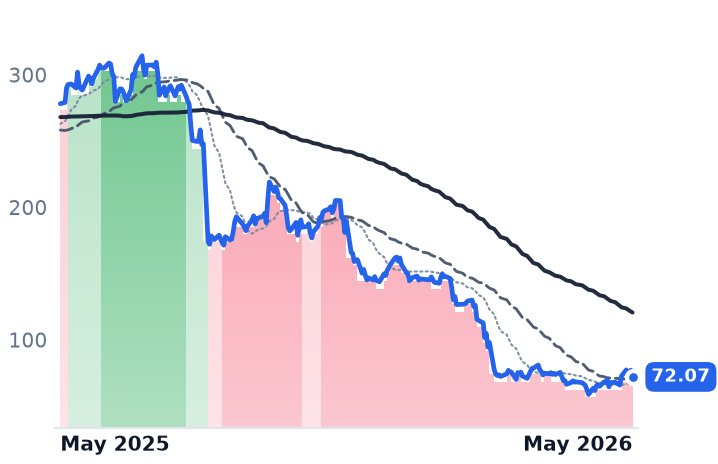
HUBS | HubSpot | Customer Experience & CRM | 🔴 Cont. Bear | −3.8% | −67.3% |
KVYO | Klaviyo | Marketing Automation | 🔴 Cont. Bear | −14.5% | −54.4% |
MNDY | monday.com | Other | 🔴 Cont. Bear | +15.5% | −74.1% |
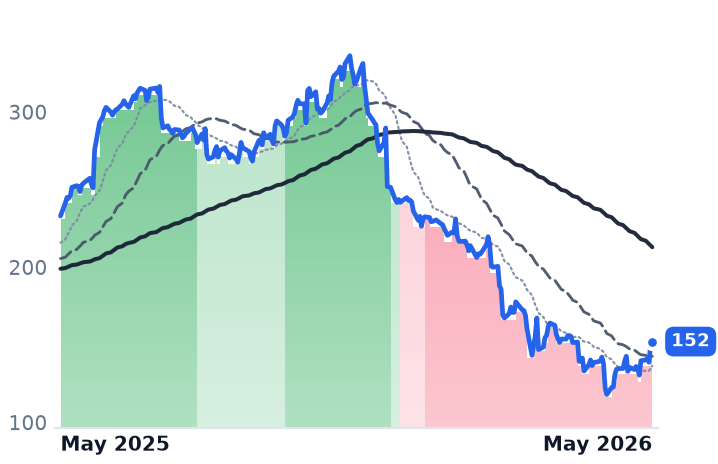
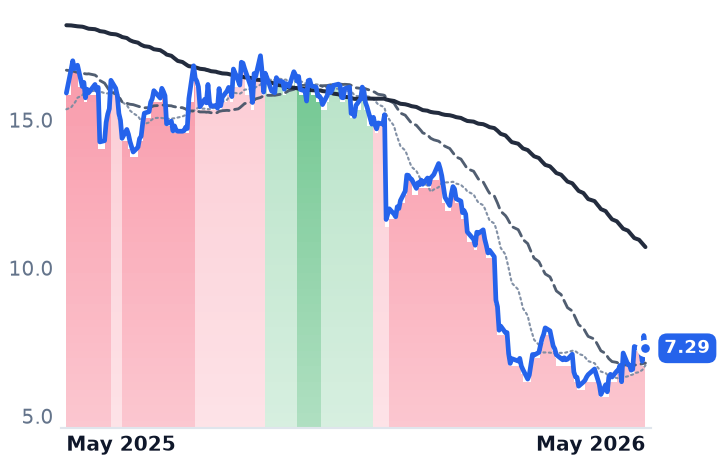
ZS | Zscaler | AI & Data Intelligence | ⚠️ Emerging Bear | +24.5% | −34.7% |
PD | PagerDuty | Developer Tools & DevOps | 🔴 Cont. Bear | +20.1% | −54.2% |
FSLY | Fastly | Cloud Infrastructure & Platform | 🟢 Cont. Bull | −30.4% | +167.1% |
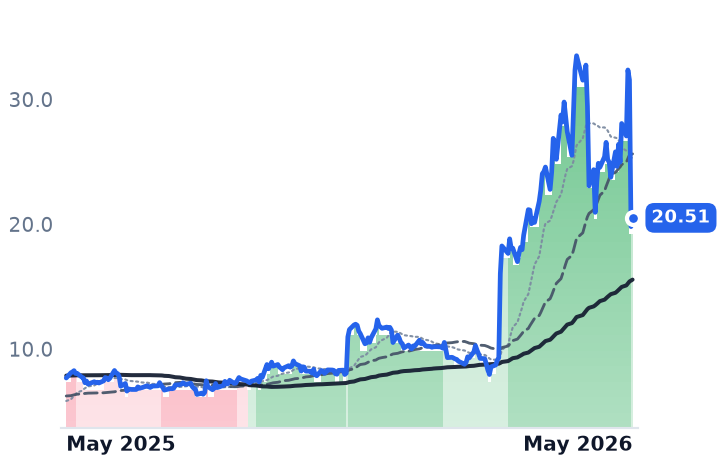
12-month price & trend
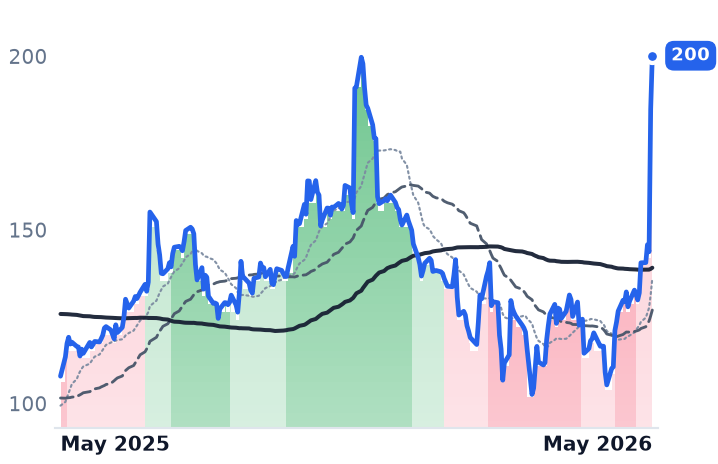
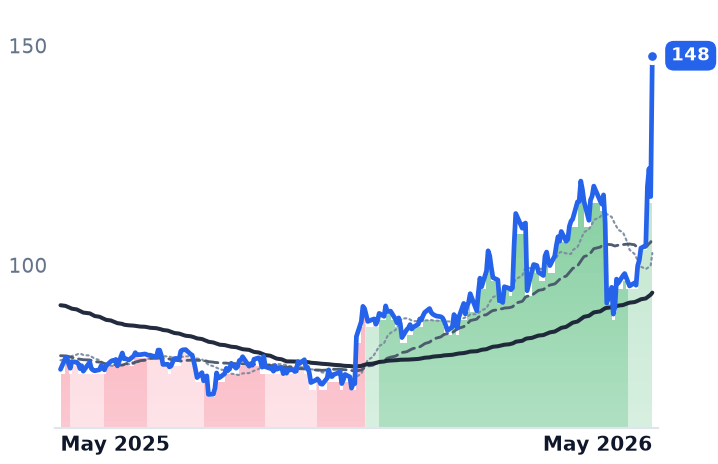
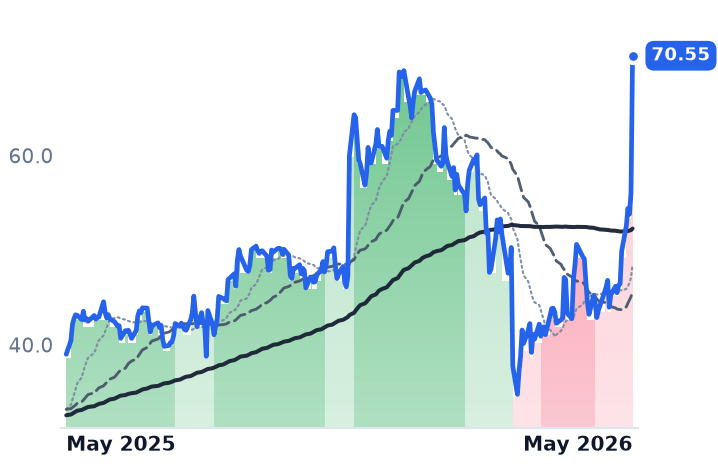
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DDOG | $88.0B | 497.4x | 101.3x | 22.2x | 20.1x | 27.9x | 25.3x | 337.6x | 1.3% |
AKAM | $16.7B | 40.6x | 17.2x | 3.9x | 3.7x | 6.9x | 6.6x | 19.1x | 3.8% |
FROG | $11.1B | n/m | 96.0x | 18.5x | 17.5x | 23.8x | 22.5x | n/m | 1.5% |
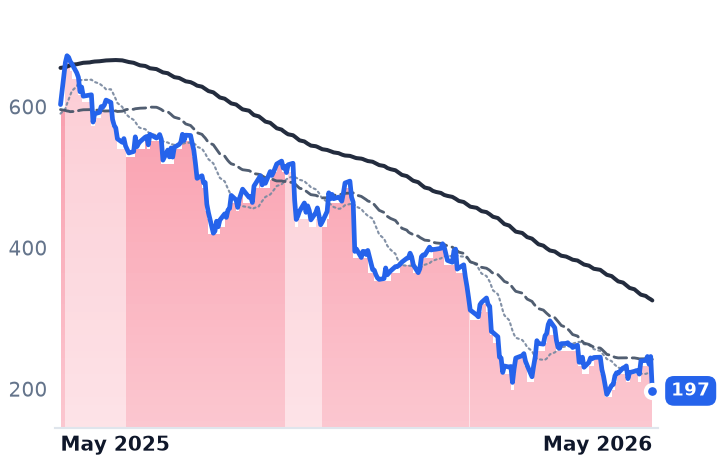
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
HUBS | $11.5B | 79.1x | 17.0x | 3.3x | 3.1x | 4.0x | 3.7x | 37.9x | 6.7% |
KVYO | $5.7B | n/m | 22.3x | 4.3x | 3.7x | 5.8x | 5.0x | 309.0x | 4.0% |
MNDY | $4.7B | 39.8x | 20.3x | 3.6x | 3.2x | 4.1x | 3.6x | 51.1x | 6.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ZS | $29.7B | n/m | 40.1x | 9.4x | 7.6x | 12.2x | 9.9x | 251.1x | 3.2% |
PD | $1.1B | 5.7x | 9.0x | 2.2x | 2.2x | 2.6x | 2.6x | 23.0x | 11.5% |
FSLY | $4.7B | n/m | 58.7x | 6.8x | 6.3x | 11.1x | 10.3x | n/m | 0.9% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
DDOG | Revenue | +28.9% | +21.5% | +23.5% |
| EPS | +20.9% | +17.3% | +23.1% | |
AKAM | Revenue | +7.4% | +11.0% | +10.4% |
| EPS | −5.0% | +6.5% | +11.1% | |
FROG | Revenue | +20.6% | +17.5% | +19.4% |
| EPS | +20.4% | +17.6% | +27.4% | |
HUBS | Revenue | +18.5% | +14.9% | +14.0% |
| EPS | +37.2% | +22.5% | +18.5% | |
KVYO | Revenue | +24.8% | +19.5% | +18.4% |
| EPS | +31.2% | +22.3% | +23.0% | |
MNDY | Revenue | +19.8% | +16.1% | +16.1% |
| EPS | +7.0% | +21.4% | +10.9% | |
ZS | Revenue | +25.2% | +16.9% | +16.7% |
| EPS | +29.0% | +11.2% | +17.6% | |
PD | Revenue | +5.4% | +0.7% | +2.8% |
| EPS | +42.1% | +16.9% | +7.1% | |
FSLY | Revenue | +20.6% | +11.9% | +10.6% |
| EPS | +870.1% | +11.5% | +13.1% |
Forward fiscal years only. Blank means no analyst coverage for that year.
What's Happening
The week of May 5–8, 2026 produced one of the cleanest sector bifurcations in recent software history. Three observability/edge/DevOps names — DDOG (+42.4% in 5 days), AKAM (+41.3%), and FROG (+34.2%) — all reported Q1 2026 results inside the same five-day window and exploded higher. Meanwhile, application-layer SaaS names KVYO (-32.3%), HUBS (-17.9%), FSLY (-24.2%), MNDY (-6.8%), and ZS (-10.6% over 90 days) continued their prolonged compression.
Critically, this is an earnings-driven divergence, not rate or multiple beta. Each winner disclosed specific, quantifiable AI-attach metrics. The laggards, by contrast, are suffering from fear of AI displacement — sometimes despite beating their own numbers.
The Three Winners: How Much Runway Remains?
DDOG — Most Fundamental, Modest PT Headroom
Datadog is the cleanest case. Q1 FY2026 revenue crossed $1.01 billion for the first time (+32.2% YoY), crushing the ~$960M consensus estimate, with full-year guidance raised to $4.32B midpoint. Wedbush raised its price target to $220 from $190, citing all-time record sequential ARR adds and broad-based strength across AI-native customers — implying roughly 10% upside from the current $200.16 close. The AI attach is concrete: approximately 6,500 customers now use at least one Datadog AI integration, representing ~20% of total customers but ~80% of total ARR. Multi-product depth is deepening, with 56% of customers using four or more products and new launches including GPU Monitoring, AI-powered security agents, and an MCP Server for live debugging. One margin watch: gross margin compressed to 80.3% in Q1 2025 from 83.3% YoY, partly due to higher cloud hosting costs from running AI/LLM observability infrastructure — a trend worth monitoring as inference workloads scale. The prior analyst entry point was around $140 pre-earnings; at $200, the valuation is materially more stretched, with only ~10% to the freshest sell-side PT.
AKAM — Largest Deal in Company History, But Already Above Consensus PTs
Akamai's move is equally fundamental. Q1 FY2026 revenue was $1.07B (+5.8% YoY), Cloud Infrastructure Services grew 40%, and management guided for "significant acceleration of overall revenue growth heading into 2027 and beyond". The headline catalyst: a landmark $1.8 billion, seven-year AI cloud commitment from a frontier AI model provider — the largest deal in Akamai's history — anchored by its global edge of 4,300 locations in 700 cities enabling low-latency AI inference. Security and compute segments together accounted for 69% of Q1 revenue, with Guardicore, API security, and the newly launched Firewall for AI (protecting LLM applications) all seeing strong demand. The problem: Evercore ISI and Oppenheimer both rate AKAM Outperform but at $130 price targets — well below the current $147.71 close. AKAM has run past prior consensus. The megadeal is real; so is ~$450M in incremental CapEx and margin compression to 26–28% EBITDA.
FROG — Real MLOps Attach, Valuation Now More Acute
JFrog Q1 2026 showed 26% YoY revenue growth to $154M, cloud revenue up 50%, net dollar retention at 120% (up from 116%), and gross retention at 97%. Margin improvement is real: non-GAAP gross margin expanded to 83.8% from 82.5% YoY, and non-GAAP operating margin rose to 21.4% from 17.4%. The AI partnerships are substantive: JFrog ML is now available to all Enterprise cloud customers, with active integrations with Hugging Face (ML model security) and NVIDIA (NIM inference microservices), and GitHub named JFrog its 2025 Tech Partner of the Year. However, the CFO explicitly stated the company did not carry forward the full benefit of Q1 over-performance into full-year guidance, and MLOps monetization upside is expected to materialize gradually. At $70.55, FROG now trades at elevated P/S multiples versus its pre-earnings stance, with the CEO noting two structural AI tailwinds — AI coding agents supercharging compiled software volume and AI accelerating open-source consumption — but the monetization pace remains the swing factor.
The Laggard Cohort: Compression, Not Collapse
The bear side of the bifurcation is more nuanced than pure fundamental deterioration. KVYO is the starkest example: the stock dropped 32.3% in five days even though Q1 2026 earnings actually beat estimates (EPS $0.22 vs. $0.20, revenue $358M vs. $348.6M) and guidance was raised to $1.518B midpoint for the full year. KVYO hit its highest non-GAAP operating margin since IPO at 16% in Q1 — a fundamentally improving business now trading at deep washout levels. For HUBS, the stock peaked near $840 in November 2021 and sits roughly 85% below that peak even as revenue has more than tripled in the period — a multiple compression story, not a revenue collapse.
The overhang is sector-level. The OpenAI internal tools revelation in late 2025 triggered a sector-wide sell-off, with KVYO dropping 12% and Braze falling 11% in a single session; TD Cowen noted it "re-fueled the debate that SaaS is at risk of displacement by DIY solutions on top of LLMs". Application SaaS valuation discounts versus broader software have widened to ~37%, nearly double the level a year earlier; Morgan Stanley describes 2026 as a potential inflection but remains "selectively opportunistic rather than broadly bullish" until AI-driven revenue upside becomes visible.
Why It Matters
The bifurcation confirms a structural rotation inside software: observability, edge inference, and software supply chain platforms that sit underneath AI workloads are capturing spend; horizontal application SaaS that sits above the end-user is under existential multiple pressure regardless of near-term fundamentals. The three winners have earned their re-ratings through quantifiable disclosures — GPU monitoring, a $1.8B edge-AI megadeal, 120% NDR from MLOps attach — but the price-to-upside calculus now differs: DDOG retains modest PT headroom (~10%), AKAM has overshot prior sell-side targets, and FROG's monetization ramp is real but gradual by management's own admission.