

AI Power Cohort: CAT, CMI, GNRC Emerge as Mid-Tier Movers with Intact Runway
Prompt v1.0
Within the AI2 turbines/utilities/BTM cohort, CAT (+21% in 90 days), GNRC (+89% YTD), and CMI (record Power Systems margins despite -8% 90-day drag from truck-cycle headwinds) are the clearest "gradual follower" names — each with confirmed hyperscaler contract disclosures, backlog visibility into 2028+, and raised guidance. The IPP group (VST, CEG, TLN, NRG) and BE are already post-blowoff, while MHI and BWXT are consolidating at rich multiples.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
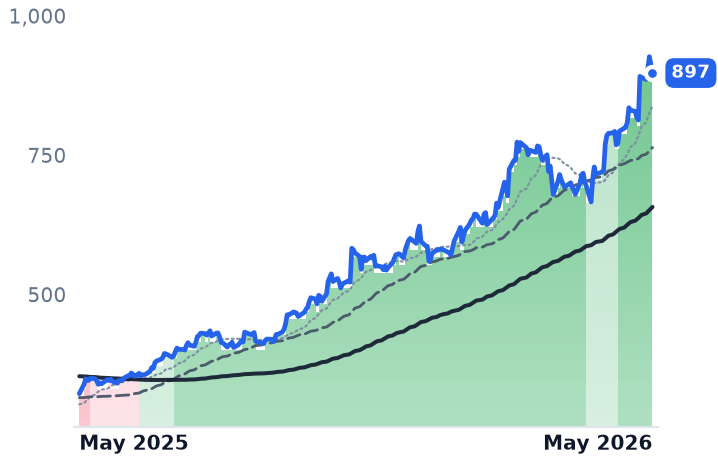
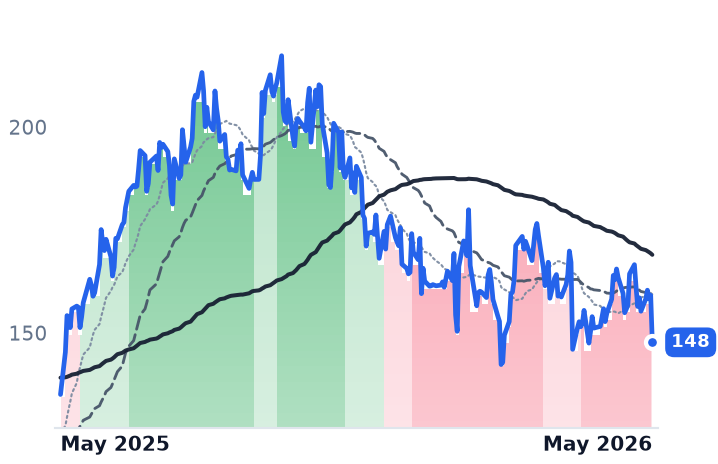
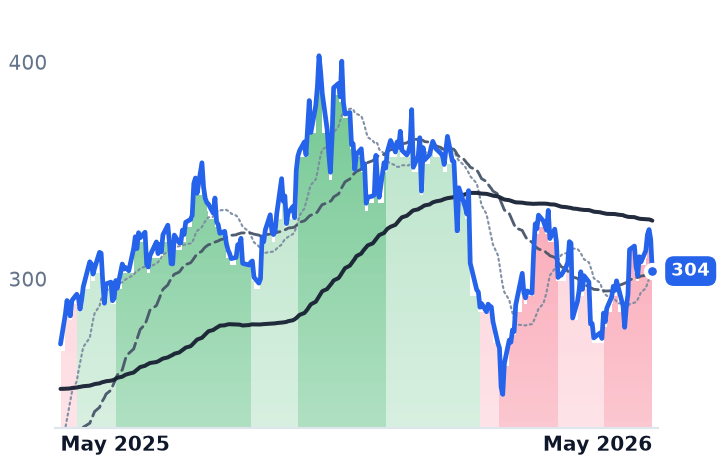
CAT | Caterpillar | Heavy Construction & Mining | 🟢 Cont. Bull | +14.2% | +178.6% |
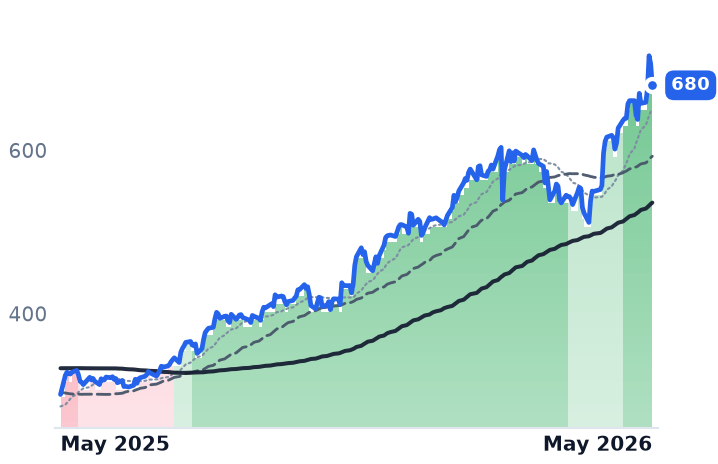
CMI | Cummins | Power & Propulsion Systems | 🟢 Cont. Bull | +11.2% | +125.7% |
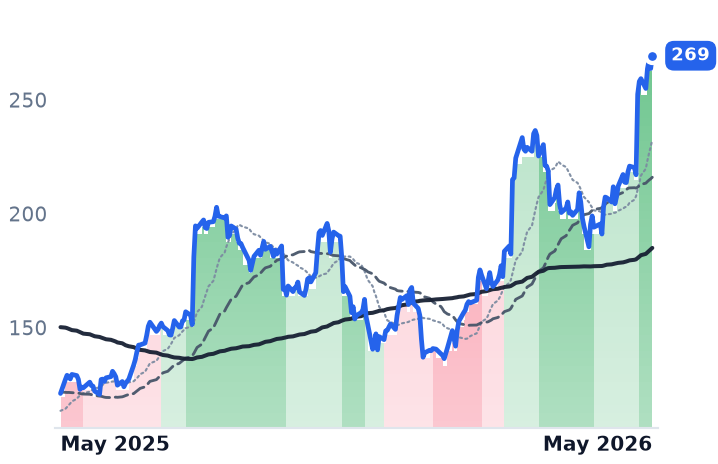
GNRC | Generac | Power & Propulsion Systems | 🟢 Cont. Bull | +29.9% | +122.5% |
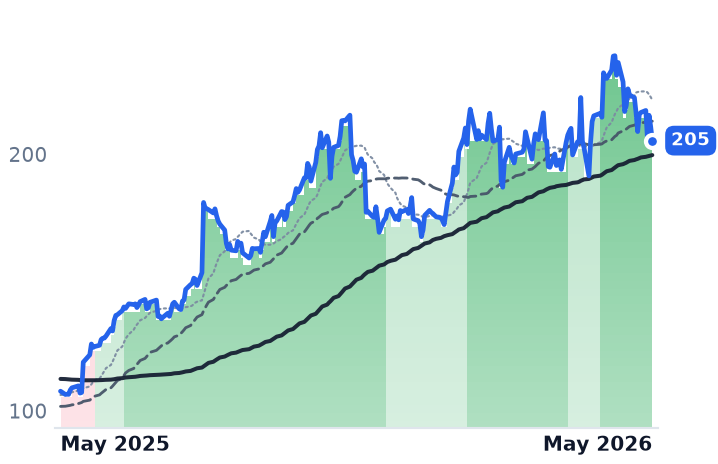
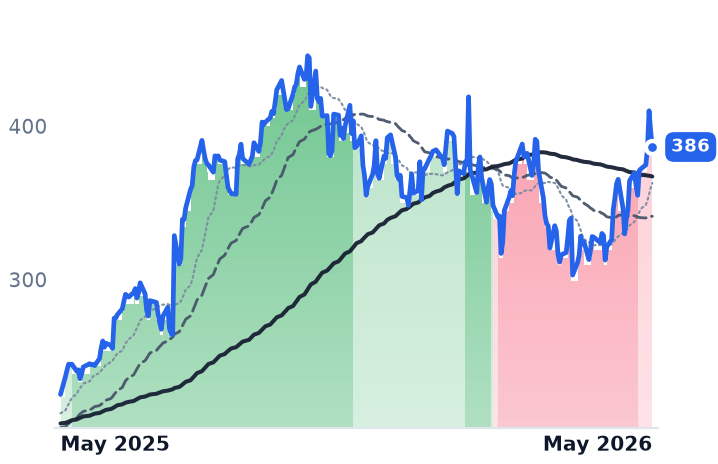
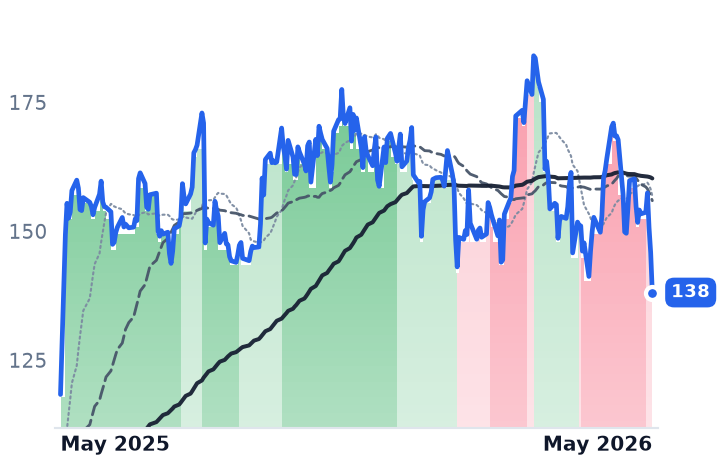
BWXT | BWX Technologies | Naval & Shipbuilding | 🟢 Cont. Bull | −10.8% | +90.7% |
VST | Vistra | Integrated Retail & Generation | ⚠️ Emerging Bear | −3.3% | +9.4% |
CEG | Constellation Energy | Diversified Renewable Generators | ⚠️ Emerging Bear | +8.3% | +12.5% |
TLN | Talen Energy | Wholesale Power Producers | ⚠️ Emerging Bear | +23.5% | +71.6% |
NRG | NRG Energy | Integrated Retail & Generation | ⚠️ Emerging Bear | −14.6% | +16.7% |
BE | Bloom Energy | Fuel Cell & Hydrogen | 🟢 Cont. Bull | +63.0% | +1381.4% |
GEV | GE Vernova | GE Vernova Integrated | 🟢 Cont. Bull | +7.5% | +161.1% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CAT | $409.2B | 43.7x | 36.2x | 5.8x | 5.4x | 17.8x | 16.5x | 29.3x | 2.8% |
CMI | $96.1B | 36.0x | 24.6x | 2.8x | 2.6x | 11.2x | 10.3x | 21.2x | 2.8% |
GNRC | $12.4B | 47.8x | 22.0x | 2.8x | 2.5x | 7.1x | 6.4x | 24.3x | 3.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BWXT | $15.9B | 44.6x | 36.5x | 4.5x | 4.2x | 20.5x | 19.0x | 31.2x | 2.0% |
VST | $47.4B | 23.5x | 15.5x | 3.0x | 2.0x | 22.9x | 15.7x | 10.3x | 2.9% |
CEG | $101.4B | 27.5x | 24.1x | 3.2x | 3.1x | 3.4x | 3.2x | 14.7x | 0.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TLN | $16.2B | n/m | 16.9x | 4.6x | 3.6x | 10.3x | 8.1x | 32.2x | 3.1% |
NRG | $25.4B | 31.5x | 13.5x | 0.7x | 0.7x | 4.2x | 4.4x | 11.5x | 1.4% |
BE | $67.7B | 275.0x | 87.8x | 21.7x | 16.7x | 69.6x | 53.5x | 194.0x | 0.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
GEV | $268.1B | 28.6x | 32.8x | 6.5x | 5.8x | 32.1x | 28.8x | 29.9x | 4.6% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
CAT | Revenue | +15.1% | +10.4% | +11.0% |
| EPS | +31.4% | +22.1% | +20.9% | |
CMI | Revenue | +10.5% | +7.7% | +9.0% |
| EPS | +24.4% | +15.5% | +15.0% | |
GNRC | Revenue | +15.4% | +20.3% | +13.1% |
| EPS | +47.6% | +20.9% | +20.5% | |
BWXT | Revenue | +20.2% | +9.9% | +7.5% |
| EPS | +24.1% | +11.5% | +11.3% | |
VST | Revenue | +20.8% | +8.9% | +4.9% |
| EPS | +89.5% | +20.6% | +16.1% | |
CEG | Revenue | +35.3% | +4.1% | +5.2% |
| EPS | +25.2% | +13.1% | +28.6% | |
TLN | Revenue | +85.4% | +16.2% | +4.4% |
| EPS | +258.6% | +48.7% | +19.6% | |
NRG | Revenue | +17.9% | +3.2% | +4.4% |
| EPS | +13.9% | +23.1% | +17.7% | |
BE | Revenue | +112.4% | +65.1% | +46.0% |
| EPS | +374.5% | +83.5% | +60.7% | |
GEV | Revenue | +23.4% | +14.6% | +15.3% |
| EPS | +322.4% | −19.0% | +40.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The Cohort Sorted: Leaders, Followers, and Laggards
The AI2 turbines/utilities/behind-the-meter universe has clearly bifurcated. The violent leaders — GEV (+65% YTD), BE (~+68% in 90 days), and the IPP quartet (VST, CEG, TLN, NRG) — have had their runs. What remains is a smaller set of names still in the gradual-mover phase, plus a group of regulated-utility and non-US OEM names that simply aren't participating in AI capex re-rating.
CAT: Validated Structural Re-Rating, Diminishing Consensus Headroom
Caterpillar is up approximately 21% over the trailing 90 days (Feb 9 close ~$742 → May 8 close ~$897), a textbook gradual sustained move. The catalyst stack is concrete: Power Generation sales jumped 44% in Q4 2025, and CAT committed to a 2GW generator contract for a West Virginia data center — one of the largest single power solution contracts in its history. Q1 2026 earnings confirmed the trend, with CAT signing an $840M Atlas Energy agreement and a Microsoft-Nvidia collaboration for a 1.35GW West Virginia infrastructure project targeted for late 2027 deliveries.
The caveat: analyst consensus sits at $865.83 (15 buy, 10 hold, 3 sell), implying roughly 3.5% upside from current prices. The Street has broadly repriced CAT's Power & Energy segment — what's arguably not yet fully modeled is EPS re-acceleration as the $51B backlog converts through 2027-28. At this stage CAT reads as a confirmed re-rating with limited near-term consensus-target upside but an unfinished earnings revision cycle.
CMI: The Cleanest Underappreciated Setup
Cummins is the most nuanced name. Its 90-day price action is net negative (~-8%, $742 → ~$682) due to a $199M Q1 2026 charge from the Accelera fuel-cell divestiture and truck-market softness — yet underneath, Power Systems is running at the highest margins in the company's history. CMI's Power Systems segment posted record Q1 2026 EBITDA of $577M at a 29.5% margin, representing nearly 39% of total adjusted EBITDA despite being only 23% of revenue. Cummins raised its full-year 2026 revenue guidance to +8–11% (from +3–8%) and EBITDA margin guidance to 17.75–18.5%, explicitly citing data center power generation demand.
Data-center-related revenue reached approximately $3.5B in 2025 (up from $2.6B in 2024), backlog extends into 2028, and active 2029 conversations are underway — with 95-liter engine capacity doubled ahead of schedule. North America power generation revenues increased 23% in Q1 2026.
The complication: consensus PT sits near $643 versus a share price around $660–682, meaning the Street's blended view is roughly "fairly priced" after CMI's near-doubling over the prior year. CMI's forward PE of 24.2x versus trailing 35.3x suggests the 2026 earnings power (consensus ~$28.19/share, 2027 ~$32.53/share) is not yet fully embedded in multiples if the truck cycle recovers alongside Power Systems growth. A May 21 Analyst Day is flagged to update long-term financial targets — a potential re-rating catalyst.
GNRC: Big Move, Shrinking Upside
Generac is the clearest data point for the hypothesis's "weakening" flags. The stock is up approximately 89% YTD 2026, with commercial data center backlog surging from $400M to $700M in under 90 days, two hyperscaler pilot-phase partnerships confirmed, and 2026 revenue guided to mid-teens growth. Q1 2026 C&I sales rose 28%, and domestic large-megawatt generator capacity is expected to surpass $1B by Q4 2026.
But the momentum has largely been captured. Consensus PT is approximately $270–272 versus current prices near $267 — though UBS raised its target to $305 (May 5) and Stephens/Argus targets sit at $290. The bull case now depends on select top-end targets, not the consensus. GNRC reads as a graduated mover whose gradual phase is largely complete.
The Rest of the Cohort
IPPs (VST, CEG, TLN, NRG): All confirmed hyperscaler PPA holders. VST holds 20-year AWS and Meta PPAs for 3,800+ MW combined; CEG holds a 20-year Microsoft TMI restart deal and a 1.1GW Meta nuclear deal; TLN provides 1,920 MW of nuclear power to Amazon through 2042. The four merchant IPPs produced a combined 71% average return in the first 9 months of 2025 alone — these are violent multi-year runs, not 30-90 day gradual movers. PJM capacity auction structurally validates the revenue floor at $329/MW-day with data centers representing ~45% of the last three auction's $47.2B total costs, but valuation has run ahead of the gradual-follower framework. NRG's 13GW LS Power acquisition at 7.5x EV/EBITDA adds capacity but hasn't yet closed the valuation discount to peers.
BWXT: Q1 2026 beat with 77% YoY backlog growth to $8.65B and a $1.4B Naval Nuclear Propulsion Program award on May 7 keep sell-side constructive — Globe and Mail notes BWXT's commercial segment backlog entered 2026 at $1.7B, up 85% YoY. But a 55x trailing PE, flat 90-day price action (~$203 → $205 with a peak-to-current drawdown of ~14%), and defense/naval anchor rather than commercial gas-turbine/BTM profile place BWXT outside the core narrative. A Yahoo Finance comparison notes BWXT's forward sales multiple of 4.96x as more attractive than speculative pure-play SMR names, but the stock is in post-run consolidation.
MHI (7011.T): Down ~9% over 90 days, reflecting JPY headwinds and non-participation in AI capex thematic at the stock level.
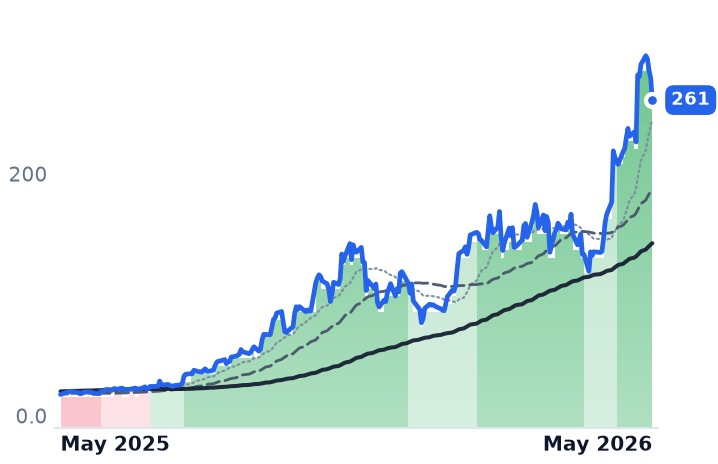
BE (Bloom Energy): ~+68% in 90 days ($155 → $261 with a $298 peak), a classic parabolic excluded by the hypothesis criteria.
Structural Backdrop
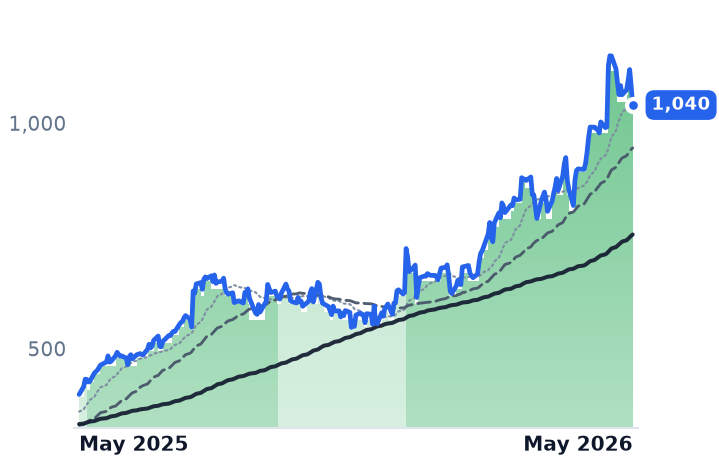
GEV remains the benchmark leader at +65% YTD with orders placed today not delivering until 2028 — confirming multi-year gas-turbine slot scarcity is structural, not cyclical. The mid-tier gradual movers like CAT and CMI are benefiting from the same demand wave with a valuation lag, while GNRC has largely closed its discount. The May 21 CMI Analyst Day is the next near-term event that could reframe whether Power Systems warrants a standalone re-rating discussion.