

INTC +147% in 3 Months: Re-Rating or Priced for Perfection?
Prompt v1.0
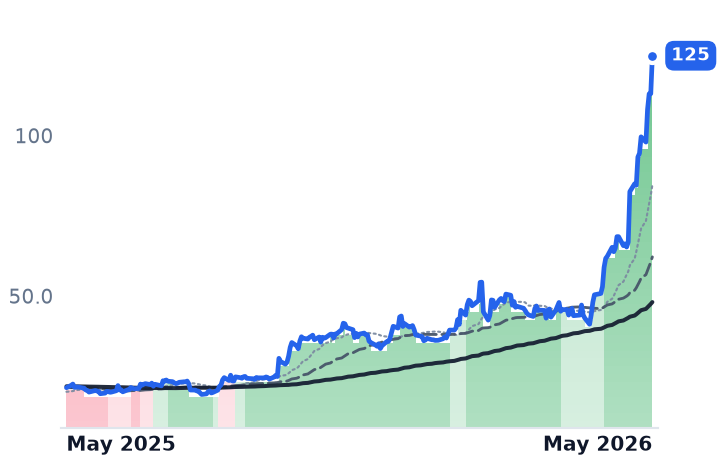
Intel has staged one of the most dramatic semiconductor turnarounds on the watchlist — +102% in one month, +147% in three — driven by a stacked catalyst sequence of earnings beats, a preliminary Apple foundry deal, and 18A yield progress. But the stock now trades at 104–140x forward earnings, well above AMD's ~56x and TSM's ~22x, with Wall Street's highest price target already breached. The gap between narrative and disclosed economics is wide.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
INTC | Intel | Specialty Semiconductors | 🟢 Cont. Bull | +102.4% | +483.1% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
INTC | $546.7B | n/m | 101.3x | 10.2x | 9.4x | 28.7x | 26.5x | 50.4x | -0.6% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
INTC | Revenue | +10.8% | +10.5% | +10.1% |
| EPS | +211.5% | +39.0% | +41.2% |
Forward fiscal years only. Blank means no analyst coverage for that year.
What's Driving the Move
Intel's rally from roughly $62 to $125 is not a single short squeeze — it's a multi-month re-rating built on a sequence of distinct catalysts. The company has delivered six consecutive earnings beats, culminating in a blowout Q1 2026 print: revenue of $13.6B (+7% YoY), non-GAAP EPS of $0.29 against a $0.00 guide, and non-GAAP gross margin of 41%, a staggering 650 basis points above guidance. DCAI segment revenue grew 22% YoY, and the ASIC business crossed a $1B annualized run rate — both operationally meaningful data points, not accounting noise.
On the foundry side, 18A process yields are running ahead of internal projections, and Panther Lake is described internally as the fastest new-product ramp in five years. Bloomberg reported on May 5 a preliminary Apple foundry manufacturing agreement — the single most important strategic signal in years, even if volumes, node selection, and pricing remain unconfirmed. Intel has also deepened collaborations with Google and SambaNova, and a partnership with SpaceX's Terafab project has added a defense/sovereign reshoring dimension to the narrative.
The Valuation Problem
Here is where the story gets complicated. INTC now trades at a forward P/E of approximately 104–140x (depending on estimate vintage), compared to AMD at ~56x and TSM at ~22x. Wall Street's consensus price target sits in the $65–80 range — roughly 48% below the current price — and the single highest analyst target of $118 has already been breached by the stock. Put plainly: no published sell-side model supports current prices on traditional DCF or earnings-multiple frameworks.
Free cash flow remains deeply negative at approximately -$3.87B. Intel Foundry posted a $2.4B operating loss in Q1 alone. The Apple deal, while symbolically powerful, carries no confirmed economics. The market is pricing in strategic optionality — US reshoring premium, foundry credibility, sovereign chip manufacturing — that has not yet translated into disclosed revenue contracts.
Multiple Expansion vs. Estimate Revision
The dominant driver of INTC's price appreciation is multiple expansion, not earnings estimate revision. Consensus 2026/2027 EPS figures have moved modestly upward on the Q1 beat, but the magnitude of the stock's move far exceeds the revision magnitude. The $62→$125 move is primarily a valuation re-rating on the thesis that Intel's foundry business is credible, not a reflection of near-term cash flow improvement.
Short interest dynamics have contributed: sustained covering across a multi-week window has amplified directional momentum without constituting a pure squeeze. The absence of a single capitulation day makes this more durable than a typical short squeeze, but also means the covering pool may not be exhausted.
The Bifurcation Ahead
The investment case now rests on a binary path. If the Apple foundry engagement converts to volume contracts and Intel's 14A node wins additional external customers in H2 2026/H1 2027 as the company has guided, the strategic re-rating has fundamental justification — Intel would represent a unique US-domiciled advanced-node foundry with a major consumer electronics anchor customer, a profile that arguably deserves a premium to historical Intel multiples. RSI and price action suggest momentum remains constructive, with no visible distribution days through the most recent data.
If execution stumbles — Apple talks cool, 18A yields plateau, or DCAI growth decelerates — the stock is acutely exposed. At 104–140x forward earnings with negative free cash flow and a $2.4B quarterly foundry operating loss, there is no valuation floor built on current financials. The margin of safety that characterized INTC at $62 has been entirely consumed by the rally.
What to Watch
The next material inflection points are: (1) formal Apple contract announcement with volume/node details, (2) any additional external foundry customer win (NVDA, AMD, MSFT, or government), (3) Q2 2026 gross margin trajectory — can 41% be sustained or expanded, and (4) Intel Foundry's path toward operating breakeven. The 2027 consensus EPS revision trend in the next 30–60 days will be the most reliable early indicator of whether the street is beginning to build models that support current prices.