

AI Datacenter Buildout Re-Ranks Infrastructure Winners and Losers
Prompt v1.0
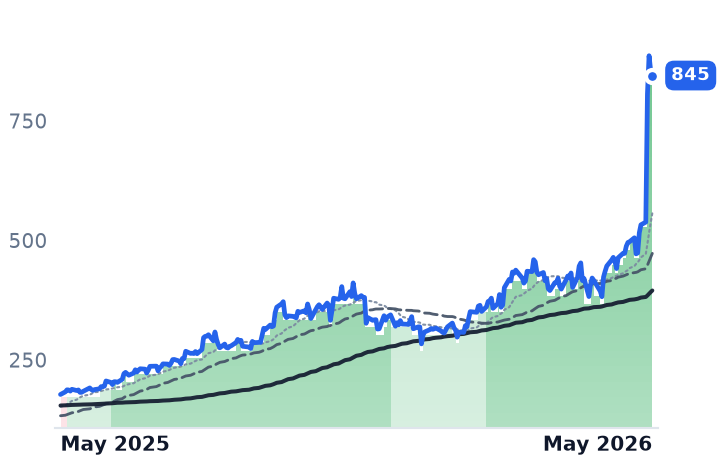
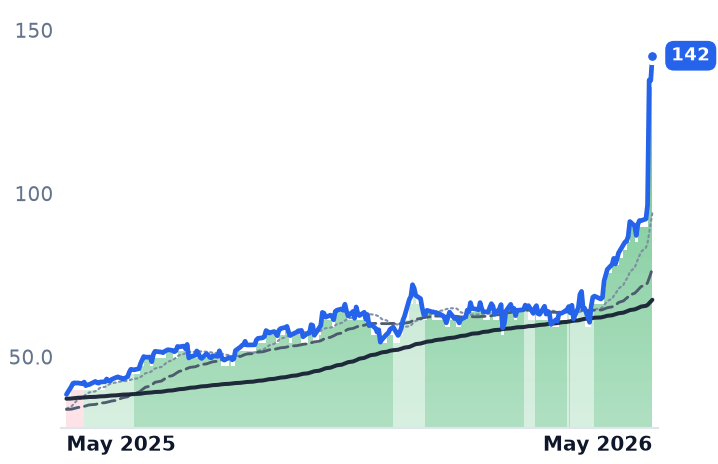
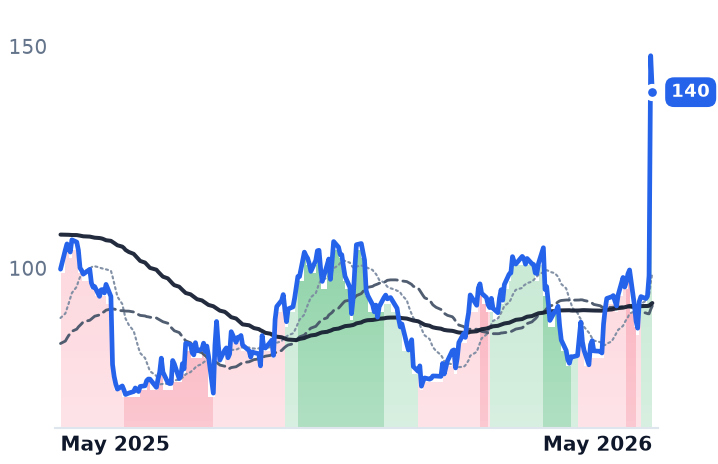
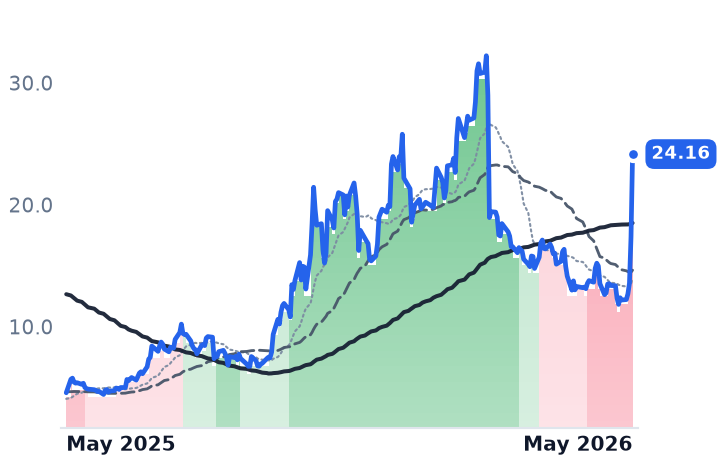
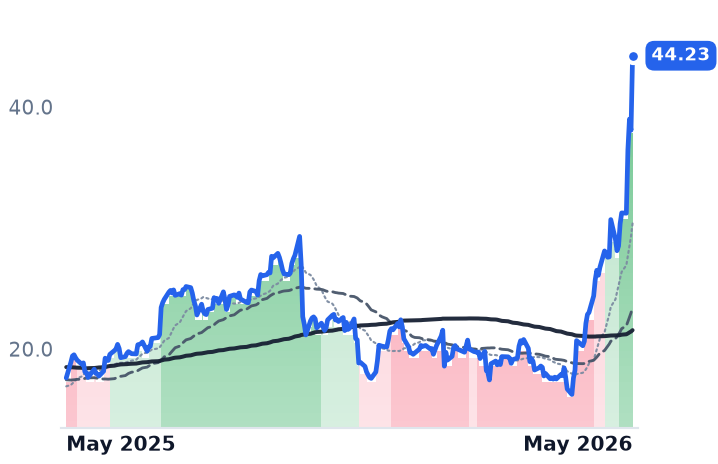
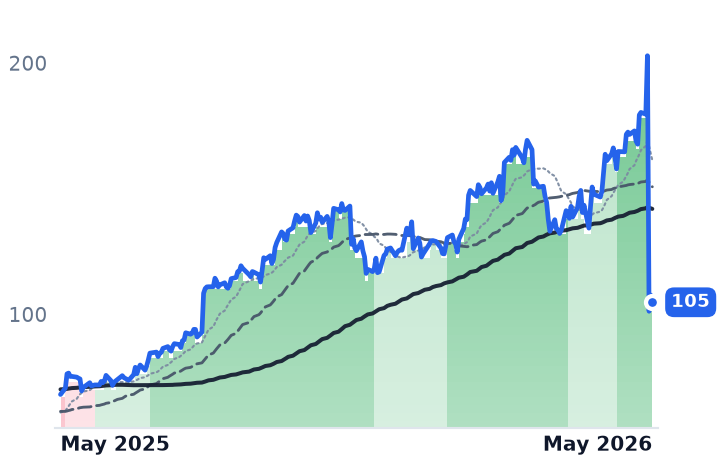
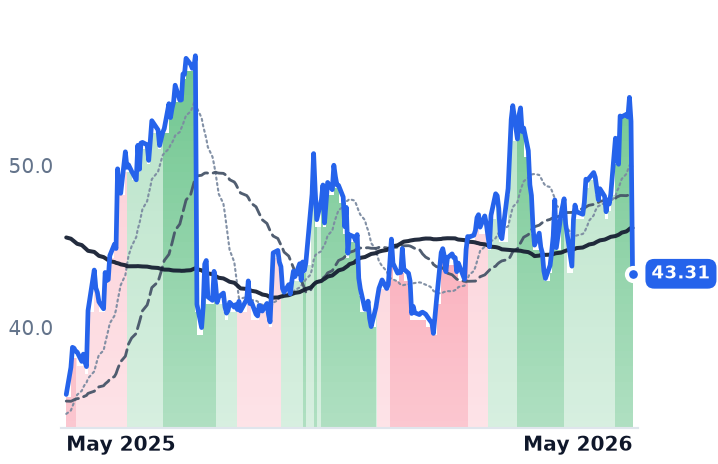
A violent 30-day re-ranking across power/grid/datacenter infrastructure names — STRL +94%, FLEX +90%, AAON +50%, FLNC +98%, PENG +94% — is overwhelmingly driven by fundamental earnings catalysts tied to AI-datacenter capex, not momentum. Meanwhile, PRIM −36% and FLR −19% reflect company-specific execution failures in unrelated segments, leaving the leaders' thesis intact.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
STRL | Sterling Infrastructure | Infrastructure & Civil Construction | 🟢 Cont. Bull | +93.9% | +375.3% |
FLEX | Flex | Electronic Manufacturing Services | 🟢 Cont. Bull | +89.5% | +269.5% |
AAON | AAON | HVAC Systems | 🌱 Emerging Bull | +53.9% | +40.0% |
FLNC | Fluence Energy | Energy Storage Systems | ⚠️ Emerging Bear | +78.2% | +427.5% |
PENG | Penguin Solutions | Data Infrastructure & Software Solutions | ⚠️ Emerging Bear | +93.6% | +151.2% |
PRIM | Primoris Services | Energy & Power Project Solutions | 🟢 Cont. Bull | −36.0% | +53.9% |
FLR | Fluor | Energy & Power Project Solutions | 🌱 Emerging Bull | −11.7% | +20.8% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
STRL | $18.3B | 52.7x | 31.6x | 6.3x | 4.9x | 27.3x | 21.0x | 30.8x | 2.4% |
FLEX | $48.0B | 50.2x | 27.7x | 1.6x | 1.4x | 17.3x | 14.6x | 26.9x | 2.2% |
AAON | $11.1B | 93.8x | 61.7x | 6.9x | 5.5x | 26.2x | 21.0x | 44.5x | -1.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FLNC | $3.8B | n/m | — | 1.5x | 1.1x | 12.9x | 9.9x | n/m | -7.1% |
PENG | $3.3B | 43.5x | 24.4x | 2.2x | 2.0x | 7.8x | 7.0x | 20.3x | -2.0% |
PRIM | $6.1B | 24.7x | 23.4x | 0.8x | 0.8x | 7.9x | 7.7x | 14.4x | 2.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FLR | $6.2B | 21.4x | 16.9x | 0.4x | 0.4x | — | — | n/m | -0.7% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
STRL | Revenue | +58.0% | +18.5% | +26.4% |
| EPS | +82.4% | +27.3% | +20.2% | |
FLEX | Revenue | +6.8% | +26.3% | +30.0% |
| EPS | +24.2% | +44.7% | +51.5% | |
AAON | Revenue | +44.5% | +15.1% | +21.9% |
| EPS | +55.9% | +53.8% | +35.7% | |
FLNC | Revenue | +29.7% | +23.6% | +18.1% |
| EPS | −61.9% | −292.6% | +127.2% | |
PENG | Revenue | +21.2% | +28.6% | +14.9% |
| EPS | +42.2% | +28.3% | +19.1% | |
PRIM | Revenue | +2.8% | +11.4% | +7.6% |
| EPS | −12.3% | +24.1% | +10.2% | |
FLR | Revenue | +2.8% | +7.0% | +6.9% |
| EPS | +19.4% | +23.9% | +15.8% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The Move Is Fundamental, Not Froth
The temptation to dismiss a basket of names posting 50–98% moves in a single month as a short-squeeze or momentum chase is understandable — but the evidence points elsewhere. Each leader in this cohort posted specific, verifiable catalysts tied directly to AI-datacenter infrastructure demand.
STRL's +94% move over the past month is anchored by a Q1 2026 earnings print showing 92% revenue growth and 131% combined backlog growth to $5.2B, with full-year 2026 guidance raised to $3.7–$3.8B in revenue and 72% adjusted EPS growth — all explicitly attributed to data center site development. That is not a company riding a narrative; that is a company with signed work.
AAON surged on a 72% YoY jump in its BasX data center cooling revenue, with a book-to-bill ratio exceeding 2x and backlog up 160% year-over-year. For a niche HVAC/cooling specialist, a book-to-bill above 2x signals demand that is materially outpacing current capacity — a signal that typically precedes sustained revenue growth, not a one-quarter aberration.
FLNC's final-day +78% spike, from roughly $13 to $24, was triggered by the signing of Master Service Agreements with two major hyperscalers and a record $5.6B backlog. This is the energy storage layer of the datacenter stack getting direct hyperscaler endorsement — a structural shift, not a rumor.
FLEX's +90% move is supported by confirmed 35%+ data center revenue growth for FY2026 and Q4 FY2026 revenue of $7.5B (+17% YoY). As a diversified electronics manufacturer with deep datacenter supply chain exposure, FLEX's re-rating reflects the market finally pricing its AI infrastructure mix more appropriately.
The Laggards Tell a Different Story — and That's the Point
PRIM's −36% collapse is entirely company-specific: solar project cost overruns and execution failures in new geographies caused a 30%+ EPS miss and a 17% full-year EPS guidance cut. Critically, PRIM's utility and gas generation segments — including datacenter-adjacent work — remained strong. This is not a signal that broad datacenter capex is slowing; it is a signal that PRIM is not a pure-play beneficiary and carries execution risk in its diversified portfolio.
FLR's −19% decline similarly reflects repeated quarterly misses (Q1 2026 adj. EPS of $0.14 vs. a $0.62 consensus estimate), a mining project charge, and Middle East-related project slowdown — all non-datacenter issues. FLR's datacenter positioning has lagged peers, and its stumbles are in legacy segments.
The divergence is thus clarifying rather than contradictory: the market is not randomly rotating — it is specifically rewarding companies with proven, contracted datacenter backlog and punishing diversified E&C names exposed to non-datacenter execution risk.
Stack-Layer Breakdown: Who Is Leading
Across the datacenter infrastructure stack, the current re-ranking favors:
- Site development / civil contracting: STRL (backlog +131%, guidance raised)
- Cooling/HVAC: AAON/BasX (book-to-bill >2x, backlog +160%)
- Energy storage: FLNC (hyperscaler MSAs, $5.6B backlog record)
- Electronics/supply chain manufacturing: FLEX (35%+ datacenter revenue growth)
The common thread is contracted, hyperscaler-linked backlog. Names without that direct linkage — or with execution risk in other segments — are being re-priced lower regardless of their notional datacenter exposure.
What to Watch
The open question the evidence does not yet answer is whether current forward multiples across the leaders already embed the backlog growth — particularly for STRL and AAON, which have re-rated most sharply. Consensus EPS revision pace relative to backlog conversion timelines will be the key variable. A book-to-bill above 2x is only valuable if margins hold as the work is executed at scale.