

AI Fiber Sub-Layer: DY Has Runway, GLW Extended, CIEN Disqualified
Prompt v1.0
Of the AI2-tagged fiber/connectivity names, Dycom (DY) is the standout "gradual uptrend with intact runway" name — record $9.5B backlog, 30x forward PE, explicit hyperscaler fiber buildout awards, and fiscal 2027 guidance of $6.85–$7.15B. Corning (GLW) is the structural winner but already extended at 87x trailing PE after a 46% 90-day surge. Ciena (CIEN) is firmly disqualified: up ~89% over 90 days and trading above the average sell-side consensus PT.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
GLW | Corning | Display & Optical Materials | 🟢 Cont. Bull | +10.1% | +320.9% |
DY | Dycom Industries | Electrical & Power Infrastructure | 🟢 Cont. Bull | +9.4% | +127.3% |
CIEN | Ciena | Optical Transport & Switching | 🟢 Cont. Bull | +12.5% | +633.4% |
LUMN | Lumen Technologies | Broadband & Fixed Services | 🟢 Cont. Bull | +13.4% | +93.2% |
BDC | Belden | Enterprise Networking Infrastructure | 🟢 Cont. Bull | −12.3% | +5.5% |
FN | Fabrinet | Specialty Manufacturing & Components | 🟢 Cont. Bull | +0.5% | +206.6% |
COMM | CommScope | Communication Equipment | 🔴 Cont. Bear | — | — |
CLFD | Clearfield | Specialized Connectivity | 🔴 Cont. Bear | +48.4% | +16.7% |
CALX | Calix | Cloud Infrastructure & Platform | ⚠️ Emerging Bear | −12.5% | +0.1% |
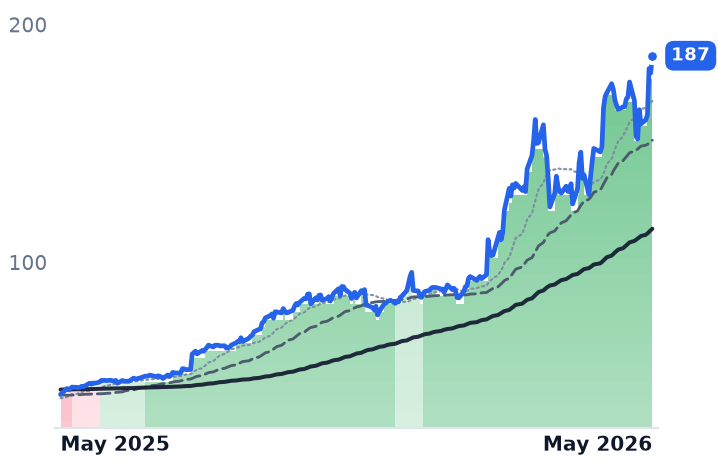
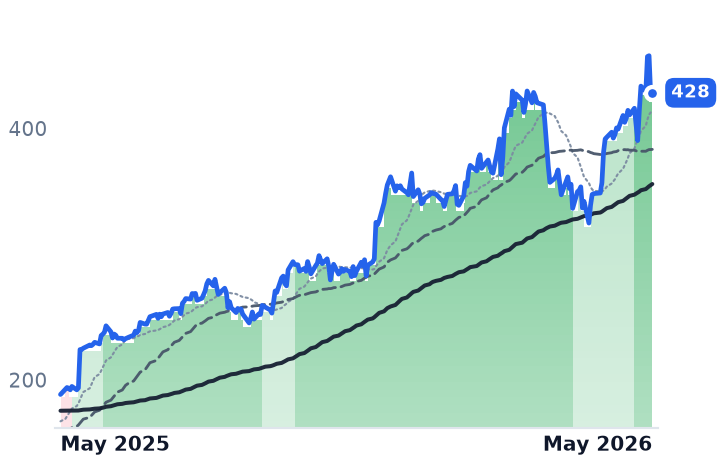
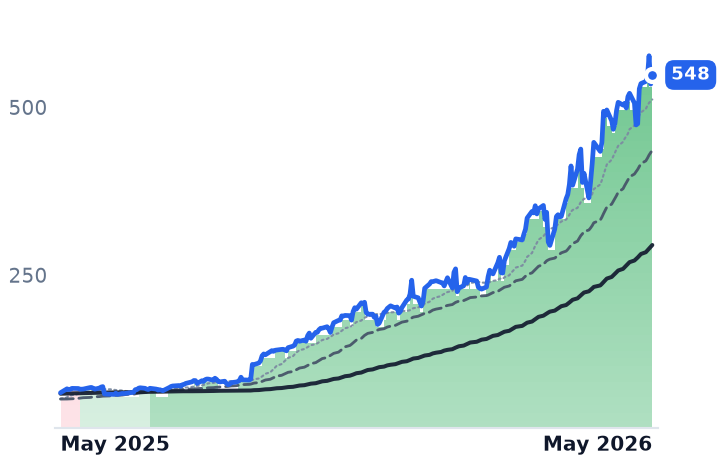
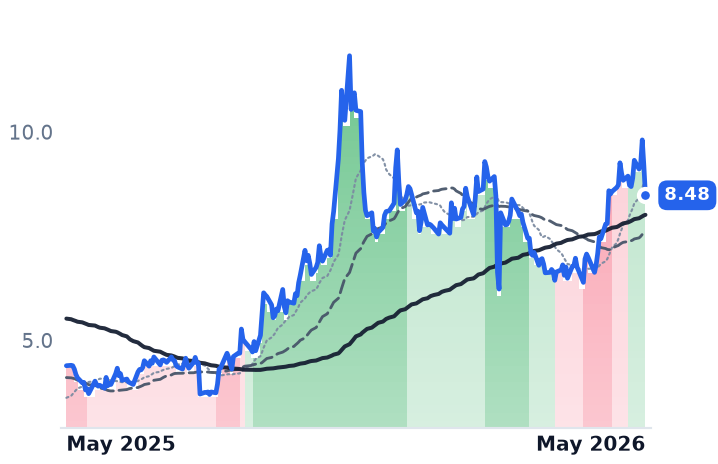
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
GLW | $137.7B | 72.4x | 48.9x | 8.1x | 7.2x | 22.4x | 19.7x | 37.1x | 1.7% |
DY | $12.0B | 37.8x | 24.2x | 1.9x | 1.6x | 9.8x | 8.1x | 13.6x | 3.7% |
CIEN | $60.7B | 138.8x | 65.6x | 10.9x | 9.6x | 25.3x | 22.3x | 83.8x | 1.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
LUMN | $6.9B | n/m | — | 0.6x | 0.6x | 1.2x | 1.3x | 8.3x | 12.1% |
BDC | $5.3B | 21.8x | 15.7x | 1.9x | 1.6x | 5.1x | 4.3x | 13.9x | 4.0% |
FN | $20.4B | 48.5x | 33.1x | 4.8x | 3.6x | 40.3x | 30.0x | 39.3x | 0.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
COMM | $3.9B | 0.6x | 11.7x | 17.7x | 0.9x | 20.7x | 1.1x | n/m | 2.2% |
CLFD | $591.1M | n/m | 82.5x | 4.3x | 3.6x | 11.7x | 9.6x | 53.9x | 2.7% |
CALX | $2.5B | 50.1x | 23.0x | 2.2x | 2.1x | 4.0x | 3.7x | 27.4x | 3.4% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
GLW | Revenue | +17.5% | +18.7% | +21.0% |
| EPS | +29.6% | +31.7% | +36.5% | |
DY | Revenue | +17.1% | +40.1% | +11.3% |
| EPS | +39.5% | +47.1% | +20.3% | |
CIEN | Revenue | +34.5% | +27.0% | +27.2% |
| EPS | +160.2% | +47.6% | +48.1% | |
LUMN | Revenue | −10.5% | −3.8% | −1.2% |
| EPS | +39.9% | −66.7% | −37.3% | |
BDC | Revenue | +25.3% | +17.2% | +4.3% |
| EPS | +16.5% | +16.2% | +9.2% | |
FN | Revenue | +35.6% | +23.6% | +21.3% |
| EPS | +36.0% | +24.7% | +24.0% | |
COMM | Revenue | −21.8% | +65.4% | — |
| EPS | −7.9% | +40.8% | — | |
CLFD | Revenue | −9.4% | +21.3% | — |
| EPS | +234.9% | +131.8% | — | |
CALX | Revenue | +19.4% | +15.6% | +14.4% |
| EPS | +27.8% | +33.8% | +45.1% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The Fiber Sub-Layer Sorting Problem
The AI2 fiber/connectivity sub-layer is not monolithic — names that share the same category tag are at wildly different points in the valuation and momentum cycle. The key editorial task here is separating the names with confirmed AI backlog and remaining price runway from those already blown out.
Dycom (DY): The Intact Runway Name
DY is the highest-conviction "gradual, unfinished" story in the cohort. The stock is up ~4.4% net over 90 days (from ~$410 to ~$428), but that headline understates the structure: the stock fell to ~$325 in late March before recovering, and the 30-day move is +12.4% — squarely inside the 12–30% "gradual uptrend" filter. Signal band transitioned to strongly bullish as of May 8, 2026.
According to Dycom's fiscal 2026 annual results release, the company ended the year with a record total backlog of $9.542 billion (+23% YoY), next-12-months backlog of $6.358B, and a book-to-bill of 1.3x for the year. Fiscal 2027 guidance is $6.85B–$7.15B in revenue (+23–29% YoY), with hyperscaler fiber infrastructure programs — long-haul, middle-mile, and inside-the-fence campus work — explicitly cited as demand drivers.
Management stated on the Q4 2026 earnings call that the original $20B five-year TAM estimate for outside-plant data center network infrastructure is "proving conservative," with long-haul/middle-mile builds "starting in earnest" around calendar 2028 — a 2–3 year gradual ramp profile that supports sustained backlog conversion rather than a one-quarter recognition event.
At ~$428, DY trades at ~30x FY2027 consensus EPS of $14.09 and 1.8x forward sales — well below the valuation of optical pure-plays. That relative cheapness, combined with confirmed hyperscaler inside-the-fence and middle-mile awards (disclosed in Q2 FY2026 earnings), gives DY the clearest combination of catalyst confirmation and remaining runway in the group.
Corning (GLW): Structural Winner, Extended Valuation
GLW has surged ~46% over 90 days (from ~$128 to ~$187), propelled by a sequence of increasingly large AI infrastructure disclosures. In Q1 2026 earnings, CEO Wendell Weeks confirmed Meta's up to $6B multiyear LTA plus two additional hyperscaler agreements "similar in size and duration" — all covering fiber, cable, and connectivity for AI data centers. Optical Communications grew 36% YoY to $1.8B in Q1 2026.
The May 6 Investor Event then accelerated the re-rating further: Corning upgraded its Springboard plan, now targeting $20B annualized sales by end-2026 and a 19% CAGR to an internal stretch target of $40B by 2030. The same day, Corning announced a multi-year partnership with NVIDIA as its optical connection partner for AI infrastructure, with NVIDIA purchasing Corning shares and a commitment tied to a tenfold increase in optical connectivity production and new U.S. manufacturing.
The structural thesis is intact. The valuation is not cheap: trailing PE of ~87x, forward PE ~58x, and 9.6x trailing sales. GLW now trades well past most pre-event consensus PTs, and while the Springboard upgrade will force sell-side revisions, the >15% consensus PT upside criterion is not met at current prices. The long-run secular story is among the strongest in the group; the near-term runway question is more complicated.
Ciena (CIEN): Firmly Disqualified
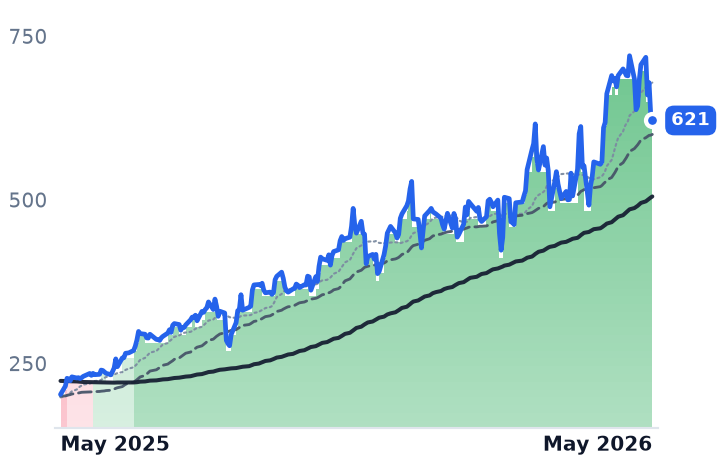
CIEN is up approximately 89% over 90 days (from ~$290 to ~$548). The fundamental story is exceptional — record $7B backlog, a $2B sequential order increase in Q1 FY2026, three confirmed hyperscaler scale-across wins for AI training clusters, and management commentary that demand will outstrip supply "for at least the next several quarters." Trailing PE of 333x and forward PE of 87x reflect the AI optical re-rating.
But Ciena's consensus analyst PT is approximately $387–$396, and even Stifel's aggressive $585 bull-case target raised May 5 — the highest in the Street — is only ~7% above where CIEN trades today. CIEN fails the >15% PT upside filter by a wide margin and is disqualified as a near-term opportunity under the hypothesis criteria.
The Disqualified / Impaired Names
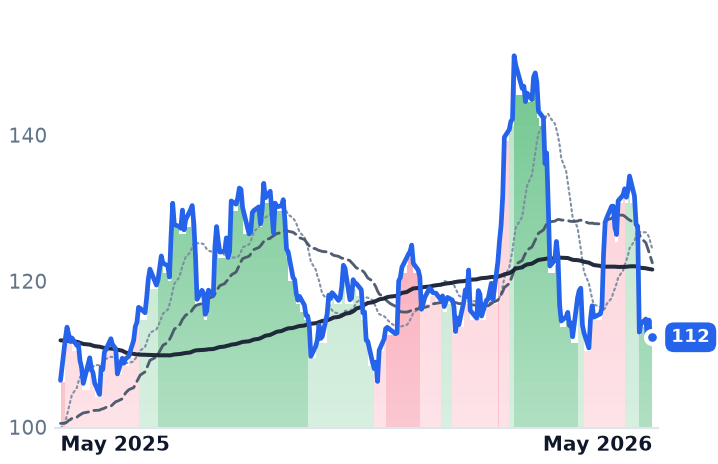
Belden (BDC): Down ~20% from its February peak (~$151 to ~$112). The $1.85B Ruckus Networks acquisition raises leverage to ~3.5x, pauses buybacks, and shifts strategic focus toward enterprise IT/OT rather than hyperscaler fiber plant. AI data center revenue is growing double-digits but remains below 5% of total revenue — too small a base to offset acquisition-driven complexity.
Lumen (LUMN): Up ~37% over 90 days, with confirmed Corning expanded partnership and a reported ~$13B PCF backlog — but revenue is structurally declining (-9% YoY in Q1 2026, -11.5% consensus for full 2026), EBITDA is negative, and the AT&T mass-market segment sale closed in February 2026, further shrinking the revenue base. This is a restructuring/catalyst story, not a gradual fiber compounder.
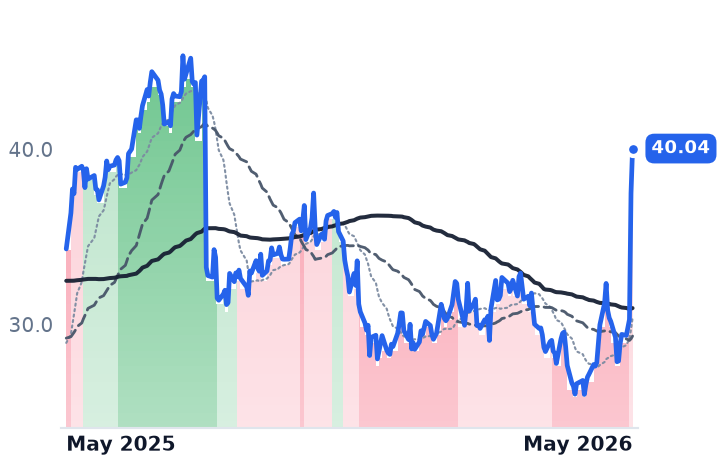
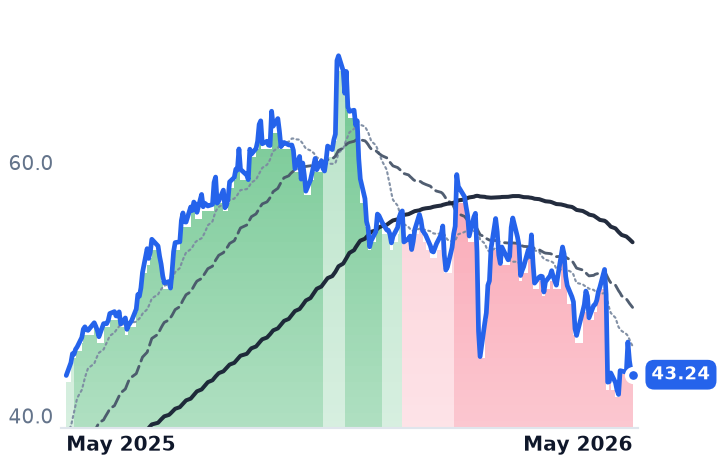
PRYMY, COMM, CLFD, CALX: No price data available in the local database for direct signal-band verification; not scoreable against the 30/60/90-day filter criteria.
Cross-Cutting Theme: Dark Fiber Capacity Tightening
The Corning-Lumen partnership — in which Corning supplies a next-generation fiber system enabling 2–4x more fiber into existing conduit — is a structural signal that long-haul dark-fiber conduit is tightening, not just transceiver demand. The PCF (prefunded capacity) model Lumen is using, with $78M recognized in Q1 2026 alone, represents hyperscalers paying upfront for fiber-network capacity they don't yet need — a demand signal that extends well beyond the current transceiver upcycle. DY's confirmed middle-mile and long-haul buildout awards sit directly in this demand stream.