

AKAM and FROG: Earnings-Driven Re-Ratings With Very Different Structures
Prompt v1.0
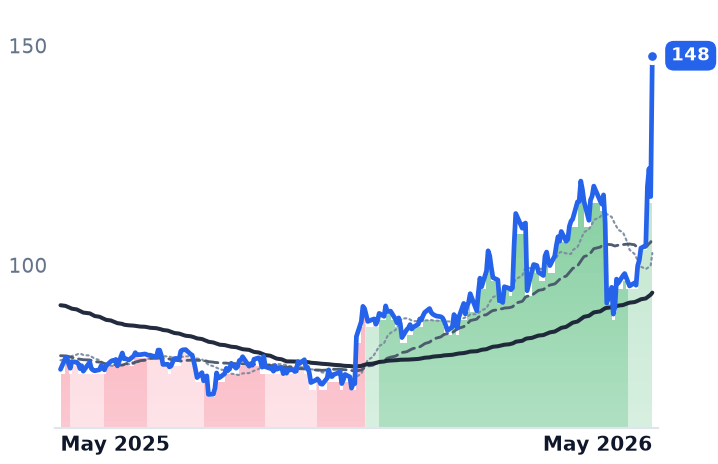
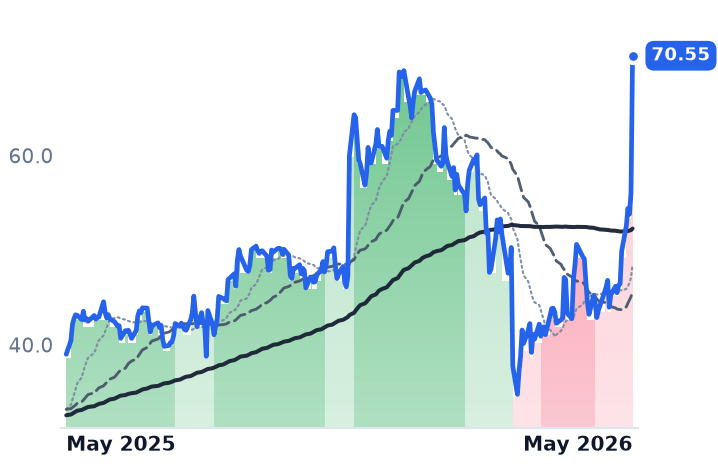
Akamai (+42% in 5 days) and JFrog (+41% in 5 days) both surged on Q1 2026 earnings, but the character of each move differs sharply: AKAM's rally is dominated by a single landmark AI infrastructure contract, while FROG's reflects a broad-based operational acceleration. Peers moved nowhere near as much, confirming company-specific catalysts rather than sector rotation.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
AKAM | Akamai Technologies | Network & Application Delivery | 🌱 Emerging Bull | +34.8% | +93.7% |
FROG | JFrog | Developer Tools & DevOps | ⚠️ Emerging Bear | +58.7% | +80.9% |
NET | Cloudflare | Network & Application Delivery | 🟢 Cont. Bull | +1.6% | +48.2% |
FSLY | Fastly | Cloud Infrastructure & Platform | 🟢 Cont. Bull | −30.4% | +167.1% |
ESTC | Elastic | Data & Analytics Platforms | 🔴 Cont. Bear | +16.1% | −38.9% |
GTLB | GitLab | Developer Tools & DevOps | 🔴 Cont. Bear | +32.1% | −47.2% |
DT | Dynatrace | Other | 🔴 Cont. Bear | +20.3% | −16.4% |
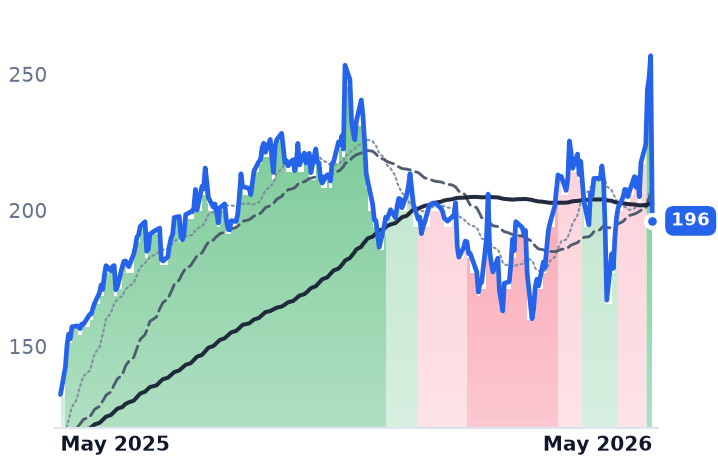
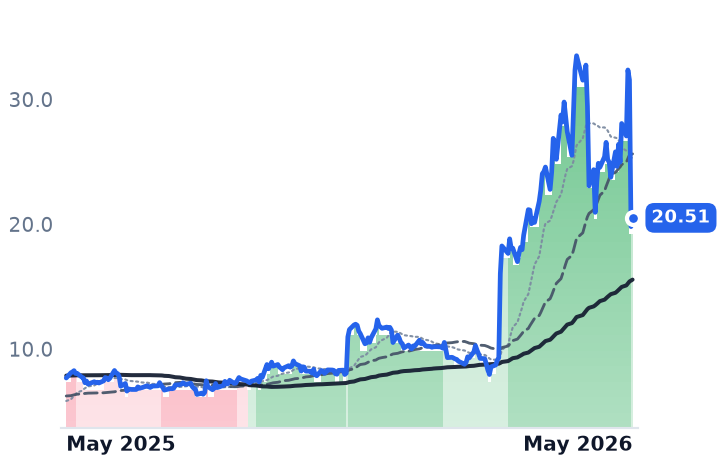
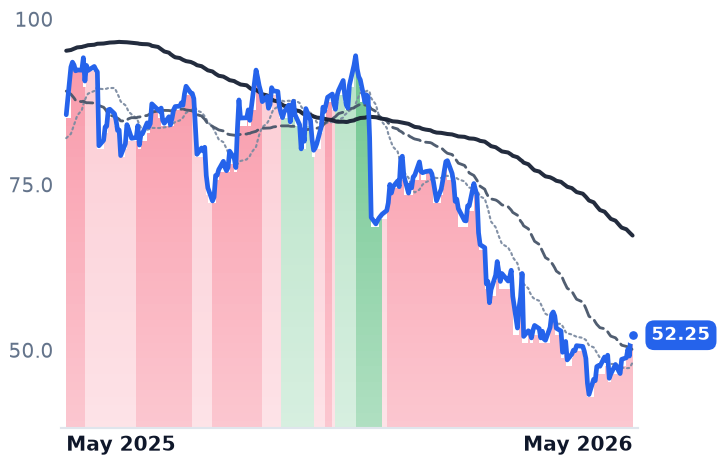
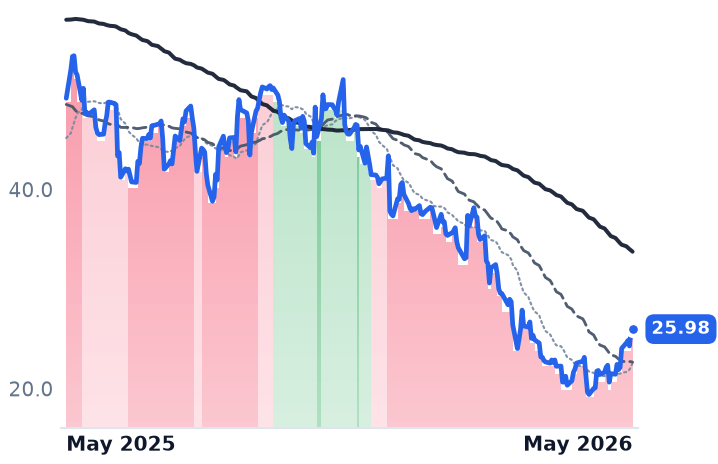
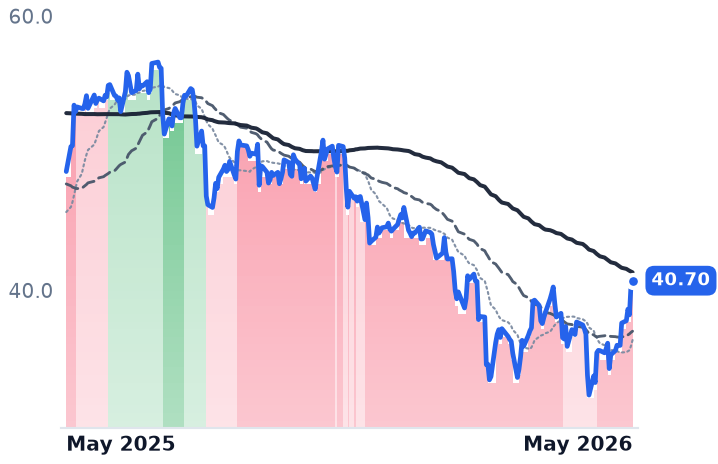
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AKAM | $16.7B | 40.6x | 17.2x | 3.9x | 3.7x | 6.9x | 6.6x | 19.1x | 3.8% |
FROG | $11.1B | n/m | 96.0x | 18.5x | 17.5x | 23.8x | 22.5x | n/m | 1.5% |
NET | $109.0B | n/m | 256.6x | 43.4x | 38.8x | 59.8x | 53.5x | — | 0.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FSLY | $4.7B | n/m | 58.7x | 6.8x | 6.3x | 11.1x | 10.3x | n/m | 0.9% |
ESTC | $9.0B | 24.5x | 26.7x | 5.2x | 4.5x | 6.8x | 5.9x | 122.4x | 3.6% |
GTLB | $6.8B | n/m | 49.9x | 6.8x | 6.1x | 7.9x | 7.1x | n/m | 3.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DT | $14.3B | 96.6x | 24.8x | 6.8x | 6.2x | 8.4x | 7.6x | 43.9x | 4.0% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
AKAM | Revenue | +7.4% | +11.0% | +10.4% |
| EPS | −5.0% | +6.5% | +11.1% | |
FROG | Revenue | +20.6% | +17.5% | +19.4% |
| EPS | +20.4% | +17.6% | +27.4% | |
NET | Revenue | +31.0% | +27.9% | +27.4% |
| EPS | +31.0% | +32.8% | +38.3% | |
FSLY | Revenue | +20.6% | +11.9% | +10.6% |
| EPS | +870.1% | +11.5% | +13.1% | |
ESTC | Revenue | +17.6% | +15.0% | +14.5% |
| EPS | +30.3% | +28.2% | +18.8% | |
GTLB | Revenue | +25.6% | +17.8% | +15.3% |
| EPS | +40.9% | −8.9% | +25.2% | |
DT | Revenue | +18.9% | +15.5% | +14.8% |
| EPS | +22.8% | +17.7% | +15.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
What Happened
On May 7–8, 2026, two names that had been trading well off multi-year highs posted some of the largest single-week moves in the infrastructure-software universe. AKAM closed at $147.71 on May 8 vs. $103.87 on May 1 — a 42.2% gain in five trading days — on volume of 20.8M shares, nearly 5x its typical daily average. FROG moved from $49.89 to $70.55 over the same span (+41.4%) on similarly outsized volume.
The peer backdrop makes the idiosyncratic nature unmistakable: FSLY fell 26.9% in the same window despite reporting record Q1 2026 revenue of $173M with security up 47%, NET fell 9.8%, while ESTC, GTLB, and DT each rose only 7–8%. The magnitude of AKAM/FROG outperformance — roughly 5–6x the gains of their closest peers — rules out a sector-wide rotation story.
AKAM: One Deal Changes the Narrative
Akamai's Q1 2026 fundamentals were, on their own, unremarkable: revenue of $1.074B came in-line, non-GAAP EPS of $1.61 beat by a penny. The re-rating story is almost entirely the landmark $1.8 billion, 7-year commitment from a "leading frontier model provider" for Cloud Infrastructure Services — the largest customer deal in Akamai's history. CEO Tom Leighton was direct on the call: "I think we've been undervalued for a while... and now we're getting that validation."
The underlying mix-shift thesis does have structural legs. CIS revenue grew 40% YoY in Q1 to $95M; security revenue ($590M, ~53% of total) grew 11% YoY; legacy delivery continues to decline ~7% YoY. Akamai's 4,100+ edge locations embedded inside ISP and carrier networks across 134 countries represent infrastructure that hyperscaler core data centers structurally cannot replicate for sub-10ms latency inference workloads — a meaningful competitive moat for the AI era. Akamai also raised FY2026 CIS guidance to at least 50% YoY growth in constant currency and repurchased 2M shares for $206M in Q1, with $975M remaining under authorization.
The risks are real. The $1.8B deal won't begin generating revenue until Q4 2026, contributing only $20–25M in that quarter, while requiring $800–825M of CapEx over the next 12 months. Non-GAAP operating margin already fell 4 percentage points YoY in Q1 to 26% as the company pre-invests in AI Inference Cloud capacity. The May 8 intraday session itself showed significant volatility — the stock sold off from near $150 pre-market to ~$134 intraday before recovering to close at $147.71 — suggesting substantial profit-taking even on the catalyst day. Sell-side responses were broadly positive: KeyBanc raised to $195 (Overweight), Guggenheim to $181, Craig Hallum upgraded to buy at $190, with UBS, Piper Sandler, and RBC also lifting targets.
At $147, AKAM trades at a forward P/S of ~3.8x on FY2026 consensus revenue of ~$4.48B — elevated vs. its 3-year depressed range but modest relative to hyperscalers, reflecting the asymmetric bet: if the $1.8B deal is the first of a series, the re-rating has further to run; if it proves a one-off, the CapEx drag weighs on margins for years.
FROG: A Cleaner Fundamental Beat
JFrog's story is structurally cleaner. Q1 2026 revenue of $154M beat consensus by 4.4%; non-GAAP EPS of $0.27 beat by 26.6%; non-GAAP operating income of $32.9M beat by 28.8%. Most notably, cloud revenue surged 50% YoY to $78.9M — crossing 51% of total revenue for the first time, a structural milestone indicating the platform has transitioned from predominantly self-hosted to cloud-first.
NRR improved to 120% in Q1, up 4pp YoY and 1pp sequentially — the highest in two years — while gross retention held at 97%. The CEO described an "AI-fueled tsunami of binaries" accelerating through the platform as AI coding agents generate compiled artifacts at increasing scale — a phrase that captures the structural tailwind: more AI-generated code means exponentially more artifacts that need to flow through JFrog's pipeline. Management raised FY2026 cloud growth guidance to 33–35% and set an NRR floor of 118%, and separately announced a $300M share repurchase program.
The platform stickiness is structural: every binary and container artifact in a CI/CD pipeline flows through Artifactory, and replacing it requires re-architecting build systems, deployment pipelines, and security scanning across an entire organization. Security Core products now comprise more than 10% of total ARR and 16% of RPO, growing from 12% a year earlier.
The valuation tension is also real. At $70.55, FROG trades at a forward P/S of ~11x on FY2026 consensus revenue of ~$627M — a multiple that prices in sustained ~25% growth, while the full-year guide midpoint of $630M is slightly below the pre-Q1 analyst consensus of $640M. A meaningful overhang: GuruFocus data shows $166.7M in insider share sales over the past three months — significant even in the context of improving fundamentals.
The Divergence That Matters
The FROG move was more distributed — daily closes from $49.89 (May 1) to $52.58, $54.41, $53.81, $56.08 before the post-earnings gap to $70.55 on May 8 — suggesting some pre-earnings accumulation followed by a fundamental confirmation gap. AKAM's move was more abrupt, with ~80% of the gain concentrated in the single May 8 session tied to the deal announcement.
These are not the same story. FROG is a beat-and-raise driven by operational momentum across cloud transition, NRR expansion, and AI-driven volume tailwinds. AKAM is a step-change re-rating event anchored to a single transformative contract whose revenue impact is backloaded into 2027 and beyond. Both trade well above their 3-year historical multiple ranges; both carry meaningful near-term overhangs (margin pressure and CapEx for AKAM; insider selling and consensus-guide gap for FROG). The peer comparison — five CDN/DevOps names moving a combined fraction of what AKAM and FROG moved — confirms these catalysts are company-specific, not sector-wide.