

SaaSpocalypse vs. Ticker Mix-Up: Separating Real AI De-Ratings from Noise
Prompt v1.0
The consumer-internet/ad-tech drawdown hypothesis is undermined by two critical ticker misidentifications — MEG is an environmental services firm and VG is an LNG exporter, not digital media plays. The genuine AI-substitution story belongs to DUOL (-68% from peak), MNDY (-80%), and KVYO (-35% in a single session) — but even there, the drivers are earnings-specific and idiosyncratic, not a unified CPM-compression wave.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
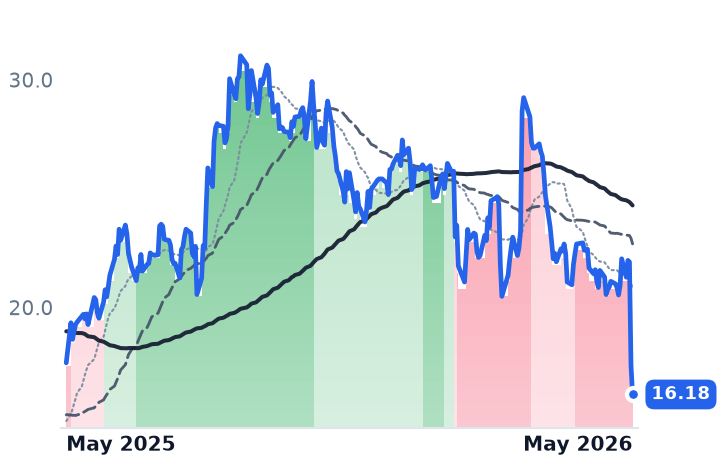
MEG | Montrose Environmental | Hazardous & Specialty Waste | ⚠️ Emerging Bear | −28.3% | −7.9% |
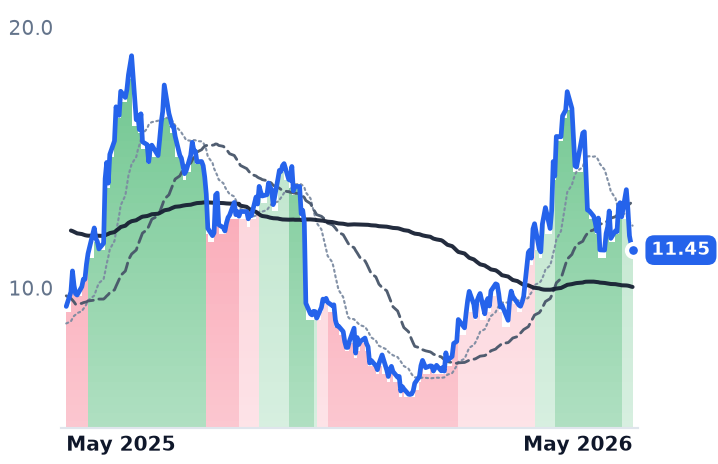
VG | Venture Global | LNG Export & Infrastructure | 🌱 Emerging Bull | −11.9% | +23.3% |
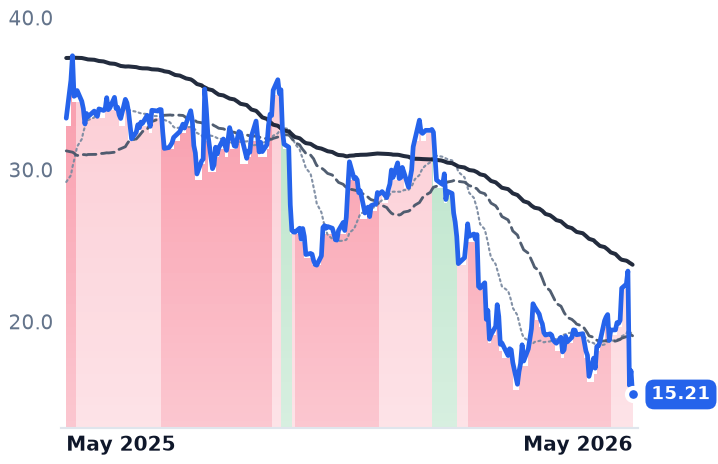
KVYO | Klaviyo | Marketing Automation | 🔴 Cont. Bear | −14.5% | −54.4% |
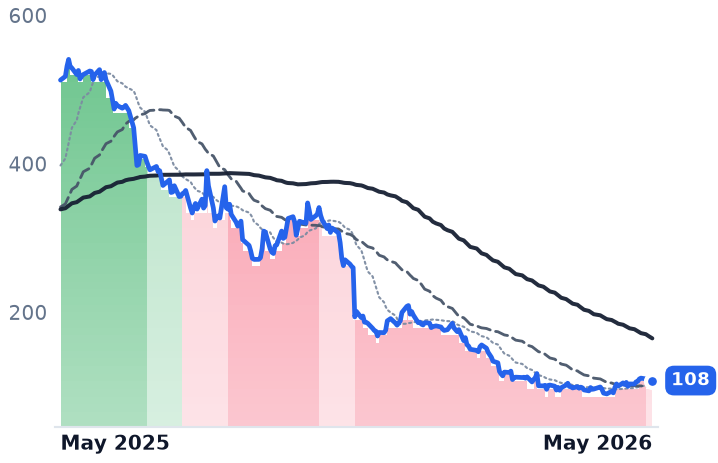
DUOL | Duolingo | Media & Content Platforms | 🔴 Cont. Bear | +19.3% | −78.9% |
MNDY | monday.com | Other | 🔴 Cont. Bear | +15.5% | −74.1% |
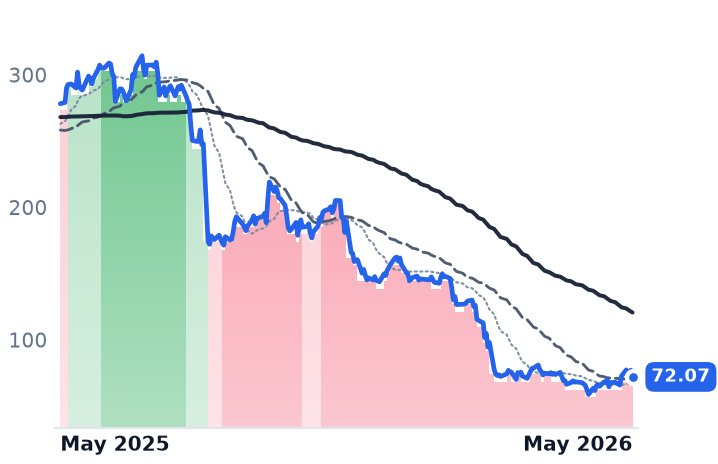
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MEG | $561.7M | 94.7x | 121.2x | 0.7x | 0.6x | 1.8x | 1.7x | 10.9x | 12.9% |
VG | $34.2B | 10.3x | 9.2x | 2.0x | 1.9x | 4.2x | 3.9x | 4.4x | -27.5% |
KVYO | $5.7B | n/m | 22.3x | 4.3x | 3.7x | 5.8x | 5.0x | 309.0x | 4.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DUOL | $6.5B | 15.3x | 49.1x | 6.0x | 5.4x | 8.3x | 7.5x | 25.2x | 6.4% |
MNDY | $4.7B | 39.8x | 20.3x | 3.6x | 3.2x | 4.1x | 3.6x | 51.1x | 6.4% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
MEG | Revenue | +5.6% | +7.2% | +5.2% |
| EPS | −1032.8% | +305.8% | +13.5% | |
VG | Revenue | +33.3% | −12.6% | +29.6% |
| EPS | +83.8% | −52.8% | +75.1% | |
KVYO | Revenue | +24.8% | +19.5% | +18.4% |
| EPS | +31.2% | +22.3% | +23.0% | |
DUOL | Revenue | +17.1% | +13.9% | +12.4% |
| EPS | −66.2% | +21.3% | +20.2% | |
MNDY | Revenue | +19.8% | +16.1% | +16.1% |
| EPS | +7.0% | +21.4% | +10.9% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The Ticker Problem That Changes Everything
The framing of a "second wave" consumer-internet/ad-tech de-rating breaks down immediately on two of its five constituent names. MEG on Yahoo Finance is Montrose Environmental Group — an environmental services and PFAS-testing company that recently rebranded as Onterris, Inc. — with zero exposure to advertising, CPMs, or consumer engagement. Its ~38% drawdown from January 2026 highs is driven by EPA regulatory uncertainty and small-cap industrial selling. CNN Markets confirms that Montrose reported Q4 2025 revenue up 2% YoY and actually raised its 2026 EBITDA outlook, with Evercore lifting its price target to $37 in March 2026.
VG on Yahoo Finance is Venture Global, a U.S. LNG exporter whose ~52% decline from its January 2025 IPO price of $24 to $11.45 reflects post-IPO multiple compression in LNG infrastructure and capital-structure overhang. StockAnalysis documents that the Plaquemines project alone issued $9.5B in senior secured notes since December 2024, and Calcasieu Pass arbitration disputes (partially settled in 2026) have weighed on sentiment. Critically, Venture Global's FY2025 results on StockTitan showed revenue of $13.8B (+177% YoY), net income of $2.3B, and Consolidated Adjusted EBITDA of $6.3B (+198%) — a fundamentally different story than CPM compression. JPMorgan's Neutral rating with a $16 price target implies ~39% upside from current prices near $11.45.
The Real AI De-Rating: DUOL and MNDY
The genuine "SaaSpocalypse" is real but its mechanism is AI-substitution of niche software workflows, not ad-budget reallocation. 247 Wall St. charts the damage: Duolingo (DUOL) is down ~80% from its 52-week high of $544.93, Monday.com (MNDY) off ~80.2%, Figma -86.5%. The investor thesis is that generative AI erodes competitive moats in language learning (DUOL) and workflow automation (MNDY) — not that advertisers are pulling budgets from these platforms (neither is an ad-tech company).
DUOL closed at $107.99 on May 8, 2026, after peaking near $341 in late October 2025. CNBC reported the Q3 2025 earnings crash — a record 25% single-day drop — when guidance missed and user growth disappointed. Perplexity Finance notes the 2026 bookings guide of 10-12% growth versus 24% actual in Q4 2025 compounded the pain, alongside an Argus downgrade to Hold. Yet the underlying business — $1.038B FY2025 revenue (+39%), 52.7M daily active users (+30%), and $360.4M FCF — remains robust. The disconnect between fundamentals and price is the de-rating story, not deterioration.
MNDY closed at $72.07 on May 8, 2026, and despite trailing-twelve-month revenue of $1.23B, $309.9M FCF, and 111% net dollar retention — with 18-19% revenue growth guided for 2026 — the stock sits at a deep discount to prior valuations, per the 247 Wall St. SaaSpocalypse analysis.
KVYO: Single-Session Crash, Idiosyncratic Drivers
Klaviyo (KVYO) is the most nuanced case. The stock dropped from $23.33 on May 5 to $15.21 by May 8 — a ~35% move in essentially one session — despite beating Q1 2026 estimates convincingly: $358M revenue (+28% YoY), 10% EPS beat, and record non-GAAP operating margins of 16.3%.
TipRanks identifies the real culprits: cautious Q2 2026 margin guidance (13-14% non-GAAP vs. 16.3% in Q1) and the announced departure of CFO Amanda Whalen in August 2026. Meanwhile, Klaviyo's Q1 earnings filing on StockTitan showed raised FY2026 revenue guidance of $1.514B–$1.522B (23% growth), strong enterprise wins, and new AI products (Composer, Customer Agent). The Investing.com Q1 transcript shows trailing TTM FCF of $212M (16% margin) and NRR of ~110%.
Where KVYO does connect to a macro theme: TipRanks notes management flagged SMB softness in new customer additions among smaller entrepreneur accounts — a macro spending headwind, not AI substitution of its marketing-automation platform. Analyst targets remain well above current prices — CNBC's KVYO quote page shows Barclays cut to $25 from $31, KeyBanc to $35 from $40, Piper Sandler to $26 from $30 — all implying 65-130% upside from $15.21.
Why the "Common Thread" Narrative Doesn't Hold
The five-ticker basket doesn't share a common de-rating driver. MEG and VG are entirely idiosyncratic with no ad-tech read-through. DUOL and MNDY are being de-rated on AI-substitution fears but are subscription/SaaS businesses, not ad-supported platforms subject to CPM compression. KVYO's sell-off is a post-earnings margin-guidance reaction compounded by a C-suite departure — with fundamentals that remain intact. The hypothesis of a "second wave" hitting consumer-engagement and marketing platforms as a unified phenomenon is not supported by the evidence.