

STRL's +90% Month: Earnings-Driven, Not Just Hype — But Valuation Now Demands Perfection
Prompt v1.0
Sterling Infrastructure (STRL) posted a historic Q1 2026 blowout — +92% revenue YoY, +57% EPS beat, and a 2.1x book-to-burn ratio — that fundamentally justifies its multi-week surge. But with STRL now trading near 40x trailing EV/EBITDA and sell-side price targets sitting 30–40% below current prices, the stock has priced in a great deal of the good news. Meanwhile, PENG's similar-looking move is driven by a completely different business: AI memory and HPC cluster integration, not site-prep contracting.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
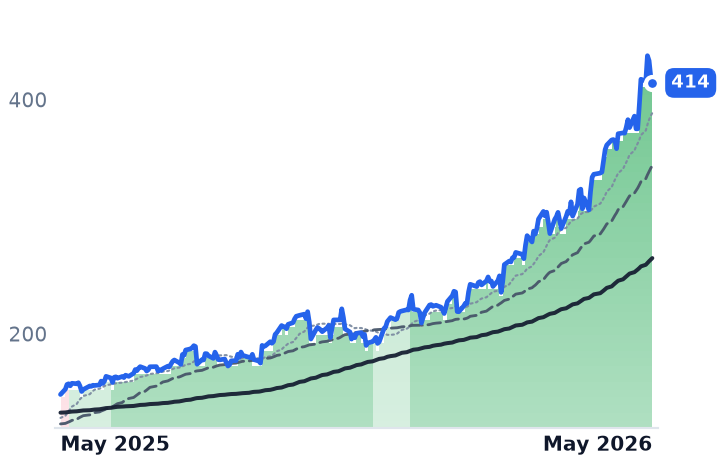
STRL | Sterling Infrastructure | Infrastructure & Civil Construction | 🟢 Cont. Bull | +93.9% | +375.3% |
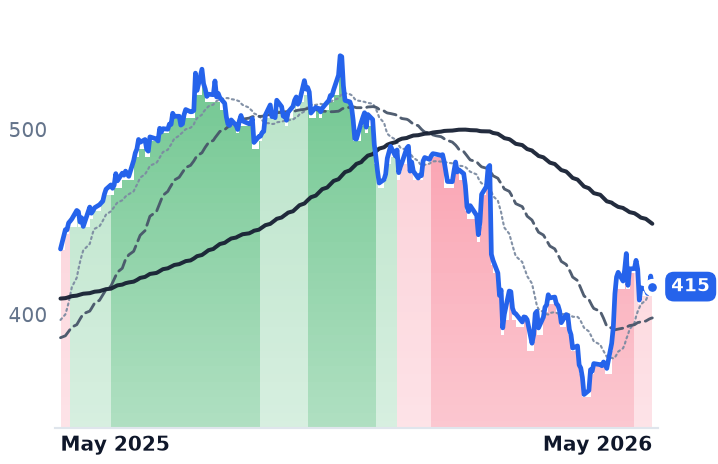
PENG | Penguin Solutions | Data Infrastructure & Software Solutions | ⚠️ Emerging Bear | +93.6% | +151.2% |
EME | EMCOR | Electrical & Power Infrastructure | 🟢 Cont. Bull | +15.2% | +110.1% |
PWR | Quanta Services | Electrical & Power Infrastructure | 🟢 Cont. Bull | +28.0% | +128.8% |
MTZ | MasTec | Electrical & Power Infrastructure | 🟢 Cont. Bull | +15.9% | +179.5% |
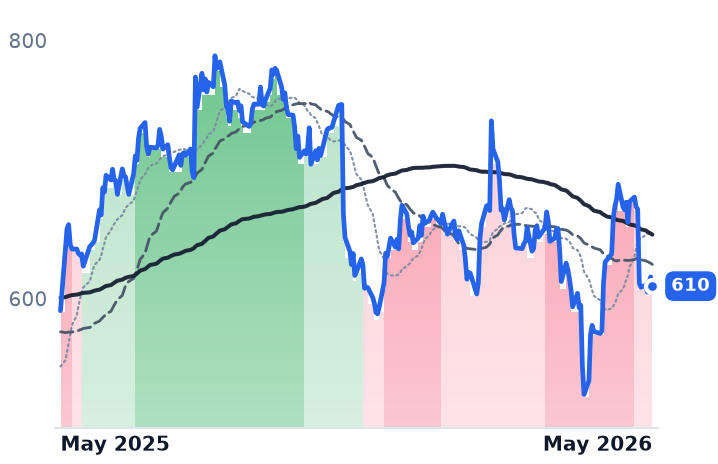
MSFT | Microsoft | Cloud Infrastructure & Platforms | ⚠️ Emerging Bear | +11.3% | −4.7% |
META | Meta Platforms | Social Media & Messaging | ⚠️ Emerging Bear | −3.0% | +3.2% |
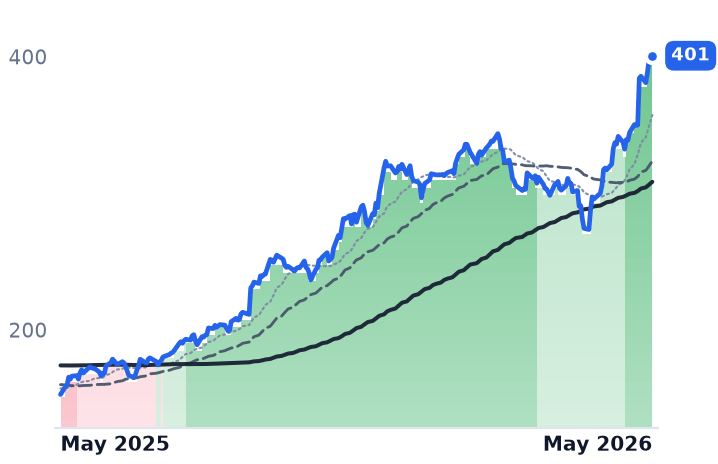
GOOGL | Alphabet | Search & Advertising | 🟢 Cont. Bull | +25.8% | +162.3% |
AMZN | Amazon.com | Online Marketplaces | ⚠️ Emerging Bear | +16.7% | +41.2% |
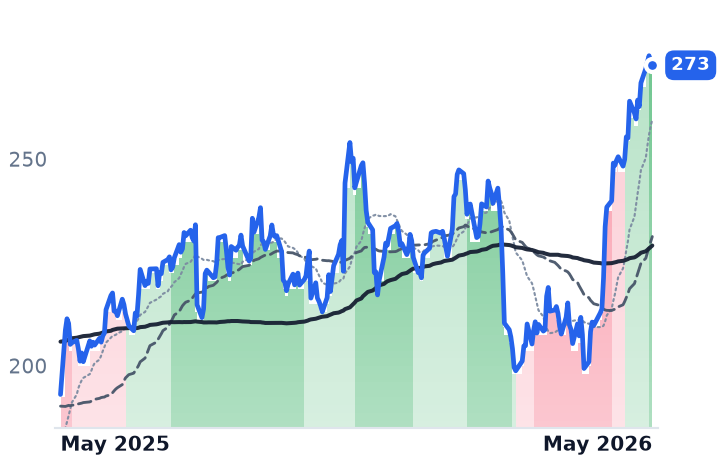
12-month price & trend
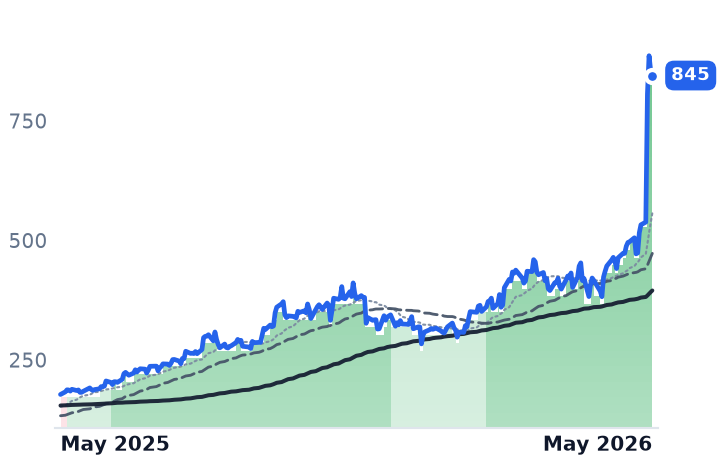
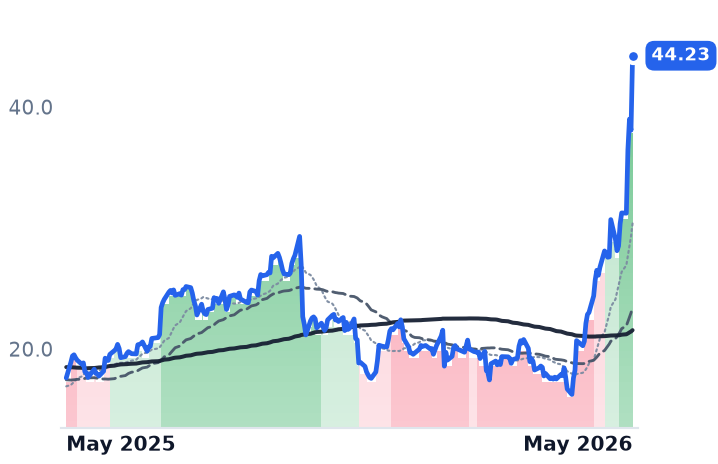
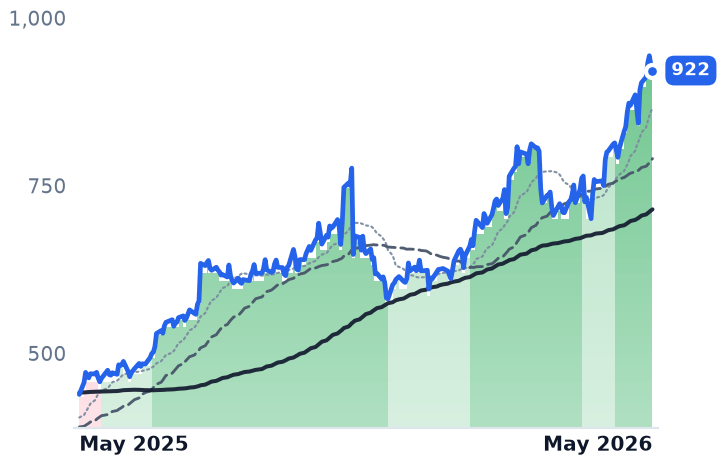
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
STRL | $18.3B | 52.7x | 31.6x | 6.3x | 4.9x | 27.3x | 21.0x | 30.8x | 2.4% |
PENG | $3.3B | 43.5x | 24.4x | 2.2x | 2.0x | 7.8x | 7.0x | 20.3x | -2.0% |
EME | $40.7B | 30.8x | 31.1x | 2.3x | 2.1x | 11.7x | 11.0x | 19.8x | 2.7% |
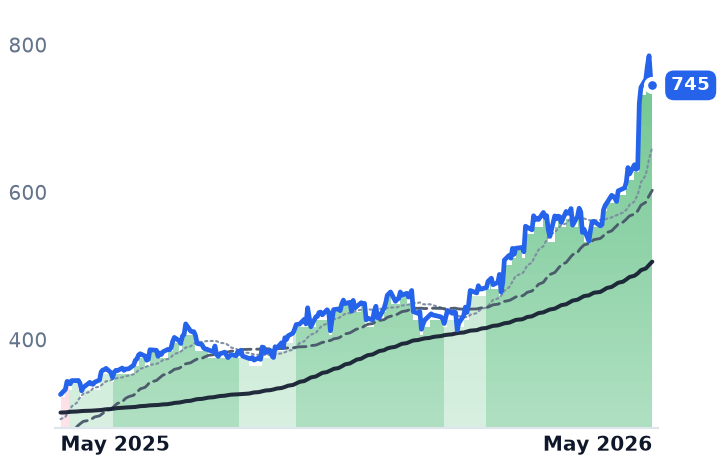
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
PWR | $100.3B | 75.5x | 42.9x | 3.1x | 2.7x | 21.2x | 18.5x | 35.1x | 2.4% |
MTZ | $21.1B | 41.4x | 28.6x | 1.3x | 1.2x | 11.4x | 10.0x | 21.9x | 1.2% |
MSFT | $3.7T | 27.5x | 25.2x | 11.1x | 9.4x | 16.3x | 13.9x | 18.2x | 1.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
META | $1.5T | 21.9x | 18.4x | 6.6x | 5.9x | 8.1x | 7.2x | 14.9x | 2.7% |
GOOGL | $4.2T | 17.2x | 17.1x | 9.4x | 8.5x | 15.4x | 13.9x | 13.0x | 1.3% |
AMZN | $2.8T | 20.8x | 22.4x | 3.6x | 3.4x | 7.2x | 6.7x | 11.7x | -0.4% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
STRL | Revenue | +58.0% | +18.5% | +26.4% |
| EPS | +82.4% | +27.3% | +20.2% | |
PENG | Revenue | +21.2% | +28.6% | +14.9% |
| EPS | +42.2% | +28.3% | +19.1% | |
EME | Revenue | +13.3% | +7.5% | +6.9% |
| EPS | +15.8% | +11.2% | +13.6% | |
PWR | Revenue | +34.0% | +15.2% | +13.1% |
| EPS | +46.4% | +16.9% | +17.3% | |
MTZ | Revenue | +30.5% | +20.3% | +14.5% |
| EPS | +43.0% | +34.8% | +28.0% | |
MSFT | Revenue | +18.0% | +18.2% | +19.6% |
| EPS | +26.7% | +15.4% | +18.5% | |
META | Revenue | +27.3% | +19.9% | +17.9% |
| EPS | +39.6% | +7.2% | +15.8% | |
GOOGL | Revenue | +23.7% | +22.5% | +19.0% |
| EPS | +90.3% | −25.8% | +18.1% | |
AMZN | Revenue | +15.7% | +14.0% | +15.9% |
| EPS | +63.6% | −10.9% | +30.2% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Separating the Two Names First
The hypothesis groups PENG and STRL as twin "datacenter site-development and electrical-infrastructure contractors" — but this framing is only half right. STRL (Sterling Infrastructure) is the genuine pure-play: its E-Infrastructure segment does physical site development, civil work, and electrical contracting for hyperscaler campuses. PENG (Penguin Solutions), by contrast, is an AI cluster integrator and HPC memory company whose segments include Advanced Computing (AI/HPC clusters), Integrated Memory, and Optimized LED — no dirt-moving, no electrical construction. PENG's +42% 5-day / +92% 1-month move is a memory-demand and AI-inference story, with the company raising FY2026 revenue growth guidance to ~12% (from ~6%) on the back of tight memory supply and 50% YoY growth in non-hyperscale AI/HPC sales. These are two distinct AI buildout plays that happen to be moving together.
STRL: The Fundamentals Behind the Surge
STRL's move is among the most fundamental-driven re-ratings in the current AI buildout cohort. Q1 2026 delivered revenue of $825.7M (+92% YoY), adjusted EPS of $3.59 vs. $2.28 consensus, net income up 143% YoY, and adjusted EBITDA margins hitting a Q1 record of 20% — a 57.5% earnings beat that few analysts saw coming.
The backlog picture is equally striking. Signed backlog reached $3.8B (+78% YoY), combined backlog (including unsigned awards) grew 131% to $5.2B, and the book-to-burn ratio clocked in at 2.1x for signed and 3.5x for combined backlog — meaning STRL is winning work far faster than it is burning through it. The pipeline of high-probability future-phase opportunities exceeds $1.3B, bringing the total addressable pool of work to approximately $6.5B, up ~$2B since year-end 2025.
Management raised full-year 2026 guidance to $3.70B–$3.80B in revenue and $18.40–$19.05 in adjusted EPS — a midpoint of ~$18.73 vs. the prior Wall Street consensus of ~$13.59 EPS and ~$3.1B in revenue. That ~38% EPS guide raise above prior consensus is massive and virtually guarantees multiple rounds of sell-side estimate revisions in the coming weeks.
Mission-critical work — data centers, semiconductor fabrication, large manufacturing — now represents over 90% of STRL's E-Infrastructure signed backlog. The CEC acquisition (an electrical contractor serving Texas data centers) contributed $156.1M in Q1 revenue and added $1.2B to combined backlog in the quarter alone. STRL was also awarded the first phase (>$500M) of a multi-phase semiconductor fabrication campus, with additional scopes extending through 2027+.
The Hyperscaler Tailwind Remains Intact
The demand side shows no signs of wobbling. The four largest hyperscalers collectively disclosed $700B+ in 2026 capex plans, up ~77% from 2025's ~$410B record, with three of four raising guidance in Q1 2026 earnings. Meta raised its 2026 capex guide to $125B–$145B; Microsoft set calendar 2026 capex at $190B; Alphabet spent $35.67B in capex in Q1 alone, more than doubling YoY. Crucially, Microsoft's AI business surpassed a $37B annual revenue run rate (+123% YoY) and the company disclosed it remains capacity-constrained through at least 2026 — exactly the kind of urgency that translates into fast-track site development awards.
STRL's CEO described being "pulled more rapidly into new geographies including Texas, Pacific Northwest, and the Midwest" with customers "screaming to get into these markets faster." The constraint is not demand — it is electrician labor supply. Management explicitly stated that access to 2,000–3,000 more electricians would accelerate growth further, and STRL is tripling its modular fabrication facility to reduce field labor requirements.
The Valuation Problem
Here is where the story gets complicated. STRL now trades at a trailing EV/EBITDA of ~40x, vs. a 10-year median of 8.46x and a 5-year average of 16.43x — a 378% premium to its historical median. Forward P/E sits near 48–50x on the raised guidance EPS. Sell-side price targets — KeyBanc at $572 (Overweight) and Argus at $510 (Buy) — sit 30–40% below the current ~$845 price, a rare and notable divergence between analyst conviction and market pricing.
CEO Joseph Cutillo sold 50,000 shares (~$24.9M) on April 23, 2026 — ahead of the blowout Q1 report — though he retains 290,593 shares. The CEO sale alone is not a red flag, but combined with a trailing P/E near 78x and EV/EBITDA at nearly 5x historical norms, the stock is priced for continued execution perfection with no room for project delays, labor shortfalls, or any hyperscaler capex moderation.
What the Evidence Weighs
The multi-week sustained move in STRL is backed by one of the clearest fundamental catalysts in the AI infrastructure space: a 35%+ revenue beat, a 57%+ EPS beat, a 2.1x book-to-burn, and a raised full-year guide that will force broad sell-side estimate revisions upward. STRL's signal band has remained strongly bullish continuously through May 8, 2026, and the 52-week return is approximately +380%. The secular demand story — hyperscaler capex racing to keep pace with AI capacity constraints — shows no 2026 deceleration signal.
The tension is entirely valuation: a company with extraordinary near-term execution trading at multiples that require that execution to continue without interruption for multiple years. PENG, meanwhile, is a cheaper and differently-structured AI infrastructure story (trailing EV/EBITDA ~19x, forward P/E ~18x) whose memory and HPC cluster exposure is genuine but distinct from the site-development narrative.