

Second-Tier Datacenter Names: Earnings Catalysts, Valuations, and Remaining Runway
Prompt v1.0
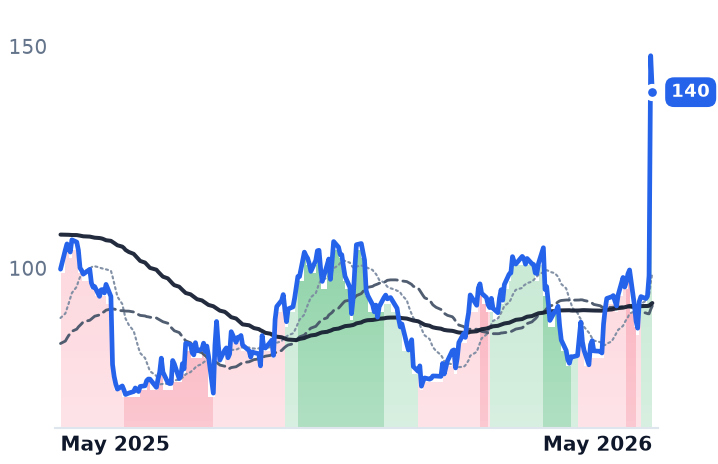
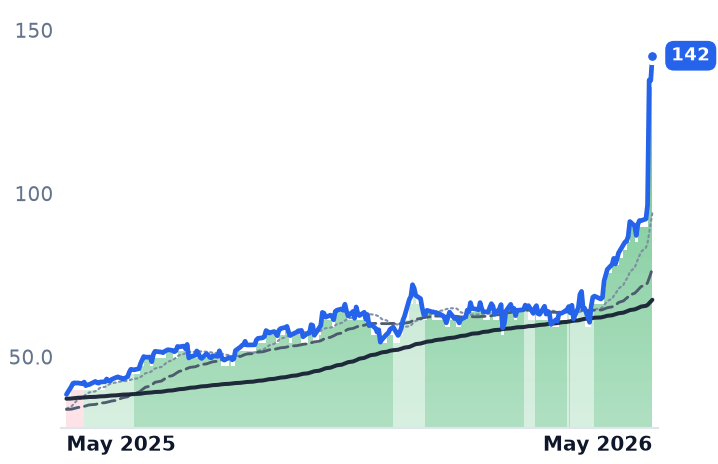
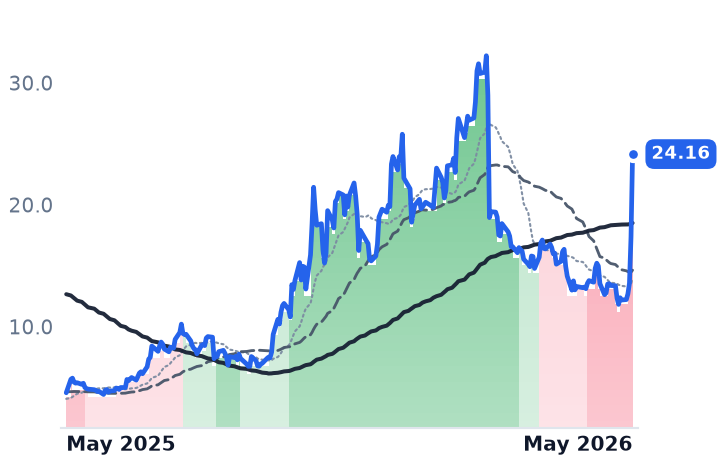
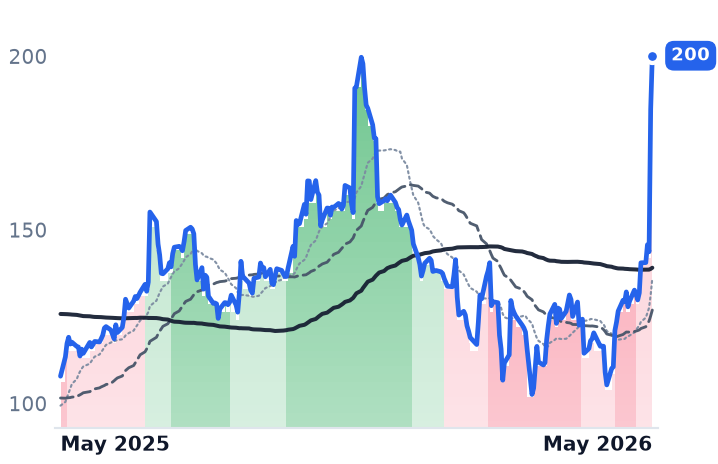
A May 7 earnings wave re-rated AAON (+72% from 35d low), FLEX (+110%), FLNC (+98%), and DDOG (+90%) on concrete backlog, revenue, and hyperscaler partnership catalysts — but post-surge, none of these names are cheap. The pivot now is from 'did they participate?' to 'how much of the AI buildout is already in the price?' with FLEX's 28x trailing EV/EBITDA standing out as the widest spread against confirmed 35%+ datacenter revenue growth.
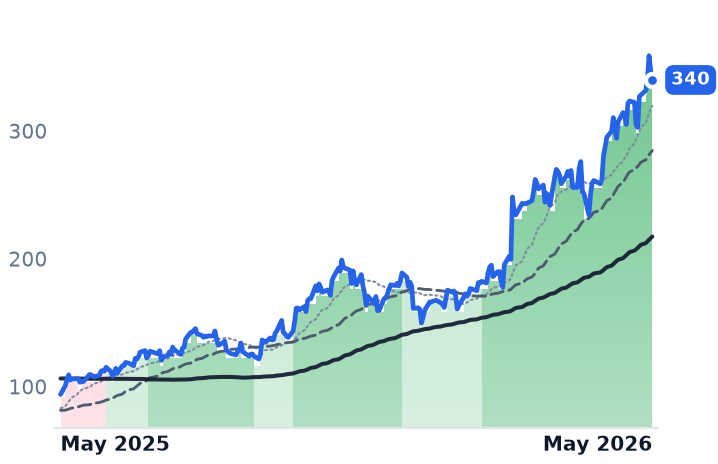
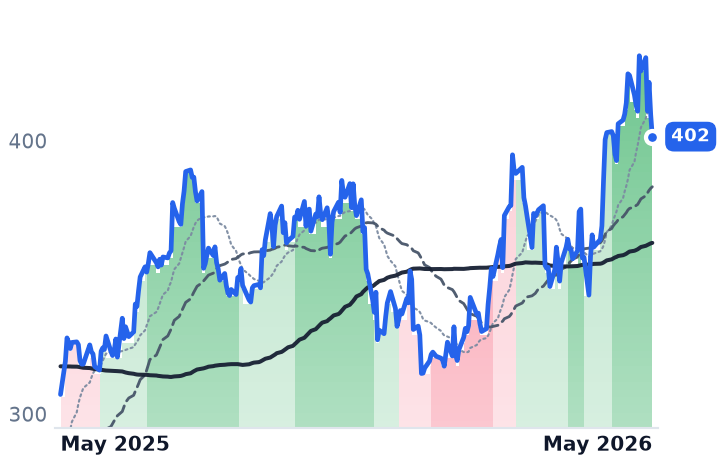
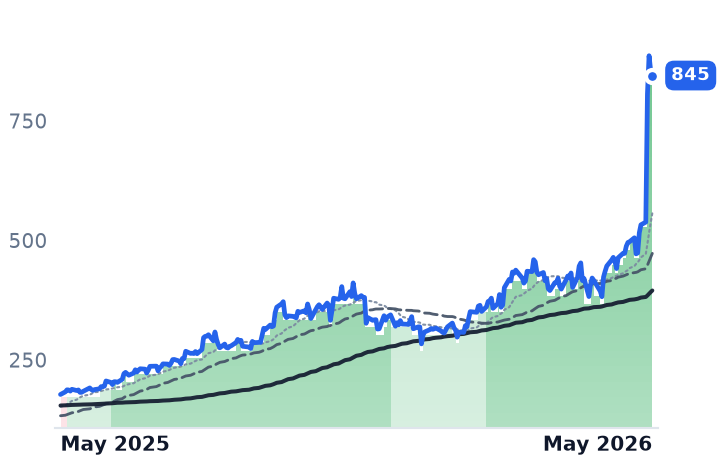
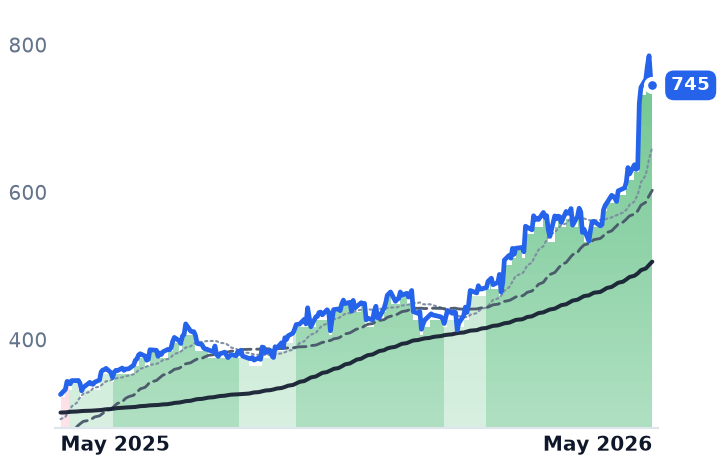
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
AAON | AAON | HVAC Systems | 🌱 Emerging Bull | +53.9% | +40.0% |
FLEX | Flex | Electronic Manufacturing Services | 🟢 Cont. Bull | +89.5% | +269.5% |
FLNC | Fluence Energy | Energy Storage Systems | ⚠️ Emerging Bear | +78.2% | +427.5% |
DDOG | Datadog | Data & Analytics Platforms | ⚠️ Emerging Bear | +83.7% | +85.5% |
VRT | Vertiv | Data Center Power & Thermal | 🟢 Cont. Bull | +18.2% | +261.9% |
ETN | Eaton | Power & Propulsion Systems | 🟢 Cont. Bull | +0.3% | +30.7% |
STRL | Sterling Infrastructure | Infrastructure & Civil Construction | 🟢 Cont. Bull | +93.9% | +375.3% |
PWR | Quanta Services | Electrical & Power Infrastructure | 🟢 Cont. Bull | +28.0% | +128.8% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AAON | $11.1B | 93.8x | 61.7x | 6.9x | 5.5x | 26.2x | 21.0x | 44.5x | -1.3% |
FLEX | $48.0B | 50.2x | 27.7x | 1.6x | 1.4x | 17.3x | 14.6x | 26.9x | 2.2% |
FLNC | $3.8B | n/m | — | 1.5x | 1.1x | 12.9x | 9.9x | n/m | -7.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DDOG | $88.0B | 497.4x | 101.3x | 22.2x | 20.1x | 27.9x | 25.3x | 337.6x | 1.3% |
VRT | $142.5B | 91.1x | 57.7x | 13.1x | 10.3x | 36.3x | 28.5x | 61.1x | 1.6% |
ETN | $178.2B | 46.6x | 34.1x | 5.9x | 5.5x | 16.5x | 15.3x | 32.9x | 2.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
STRL | $18.3B | 52.7x | 31.6x | 6.3x | 4.9x | 27.3x | 21.0x | 30.8x | 2.4% |
PWR | $100.3B | 75.5x | 42.9x | 3.1x | 2.7x | 21.2x | 18.5x | 35.1x | 2.4% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
AAON | Revenue | +44.5% | +15.1% | +21.9% |
| EPS | +55.9% | +53.8% | +35.7% | |
FLEX | Revenue | +6.8% | +26.3% | +30.0% |
| EPS | +24.2% | +44.7% | +51.5% | |
FLNC | Revenue | +29.7% | +23.6% | +18.1% |
| EPS | −61.9% | −292.6% | +127.2% | |
DDOG | Revenue | +28.9% | +21.5% | +23.5% |
| EPS | +20.9% | +17.3% | +23.1% | |
VRT | Revenue | +35.2% | +25.8% | +19.4% |
| EPS | +55.6% | +33.8% | +25.8% | |
ETN | Revenue | +18.5% | +10.9% | +8.9% |
| EPS | +11.6% | +18.3% | +16.9% | |
STRL | Revenue | +58.0% | +18.5% | +26.4% |
| EPS | +82.4% | +27.3% | +20.2% | |
PWR | Revenue | +34.0% | +15.2% | +13.1% |
| EPS | +46.4% | +16.9% | +17.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
What happened on May 7
The second-tier datacenter buildout cohort repriced sharply and simultaneously as Q1/fiscal Q4 2026 earnings hit. AAON reported Q1 2026 revenue of $496.9M — a 54.3% YoY surge that crushed the $381M consensus — with its BASX data-center cooling brand growing 72.4% to $228.6M and total backlog up 107% to $2.13B, its sixth consecutive quarterly record. AAON then raised full-year 2026 revenue guidance to 40–45% growth (from a prior 18–20% guide), implying roughly $1B in BASX revenue for the year. The stock moved from ~$98 pre-earnings to ~$148 at the close, a ~50% single-session jump, and stands ~72% above its April 6 low of $81.25.
Flex posted fiscal Q4 2026 revenue of $7.48B (+16.9% YoY) and confirmed its data center business is growing at least 35% annually, representing approximately $6.5B in revenue — roughly 25% of the total company. Flex also disclosed a new partnership with Amazon Web Services and a collaboration with NVIDIA on next-generation 800V DC AI factory infrastructure, alongside power manufacturing expansions in Dallas, Poland, Fontana (California), and Colombia. The stock surged from $96.45 to $134.73 on the earnings release and reached $142.17 by May 8, up ~110% from its April 6 low of $67.70.
Fluence Energy (FLNC) disclosed two Master Supply Agreements with major hyperscalers for data center energy storage — selected from 26 competing vendors — plus a 12-gigawatt-hour hyperscaler-specific pipeline and a record $5.6B total backlog as of March 31, 2026, with order intake doubling year-to-date. FLNC surged ~78% in two sessions following the announcements, now up ~98% from its 35-day low.
Datadog crossed $1B in quarterly revenue for the first time ($1.006B, +32% YoY) and raised FY2026 guidance to $4.3–4.34B. The company disclosed 8-figure annualized deals with AI research divisions of two of the world's largest technology companies for GPU monitoring on hyperscale training workloads, signaling expansion into training observability. DDOG cleared $200 by May 8, up ~90% from its 35-day low.
The macro anchor: $725B in hyperscaler capex
Q1 2026 hyperscaler earnings confirmed combined Big-5 capex of approximately $725B for 2026 — up ~64% YoY, with Alphabet raising to $180–190B, Meta to $125–145B, Microsoft guiding to ~$190B, and Amazon reaffirming $200B. Critically, all four hyperscalers characterized conditions as supply-constrained rather than demand-constrained: Microsoft confirmed Azure AI at a $37B annual run-rate (+123% YoY), Google Cloud's backlog exceeded $460B, and AWS grew 28% — its fastest pace in 15 quarters. The supply-constrained framing is the single most important macro variable for the second-tier names: it means backlogs should convert, not evaporate.
Valuation dispersion within the cohort
Post-surge, valuations have diverged sharply and the runway question is no longer uniform across the four names.
FLEX remains the most attractively valued on a risk-adjusted basis. Its trailing EV/EBITDA of 28.4x and forward P/E of 35.5x sit well below the Tier-1 comp set, and the company has sustained 6%+ operating margins for four consecutive quarters with strong free cash flow conversion. At roughly $6.5B in data center revenue growing 35%+, the datacenter segment alone is approaching the size of many pure-play peers — yet FLEX still carries the multiple of a diversified contract manufacturer.
AAON trades at 46.3x trailing EV/EBITDA and 89.5x trailing P/E (forward P/E ~65.6x). Vertiv (VRT), the Tier-1 thermal management peer, trades at ~52x trailing EV/EBITDA and ~45x forward P/E after raising its FY2026 guidance to $13.5–14.0B in net sales, with a backlog exceeding $15B. AAON's relative discount to VRT on trailing EV/EBITDA (~46x vs. ~52x) is narrowing, but AAON's 40–45% revenue guide compares favorably to VRT's 34%. The key variable is gross margin recovery: AAON margins compressed from 33% (FY2024) to 25.1% in Q1 2026, with management attributing the gap to outsourcing costs, Memphis ramp inefficiencies, and tariffs — all characterized as transitory and already addressed in backlog pricing. Management's stated facility revenue potential exceeds $2B with the heavy Memphis capex phase largely complete, implying a path to operating leverage.
FLNC is pre-profitability (FY2026 EBITDA guided to just $40–60M on $3.2–3.6B revenue), making traditional multiple comparisons less meaningful. The investment thesis here is option-like: two confirmed hyperscaler MSAs, a $5.6B backlog, a $12B data-center-specific pipeline, and Fluence's specific technical differentiation — sub-10ms power response for AI datacenter load fluctuations, derived from European grid markets — at a market cap that remains small relative to the pipeline. The stock has already moved ~98% from its low, and margin execution will determine whether the MSA wins translate to durable earnings power.
DDOG is the most extended at 386x trailing EV/EBITDA and 86x forward P/E. The premium reflects 79%+ gross margins, 32% revenue acceleration, and structural positioning as the observability standard for AI-era cloud and training workloads. New logo ARR more than doubled YoY in Q1, setting an all-time record. The valuation leaves little room for execution variance.
Context from Tier-1 peers
The second-tier cohort's moves look less extreme against the Tier-1 backdrop. Sterling Infrastructure (STRL) reported Q1 2026 revenue up 92% with E-Infrastructure margins of 25% and raised its 2026 guide to >50% revenue growth; the stock rose ~115% from its 35-day low to ~$844 and now trades at ~79x P/E. Quanta Services (PWR) surged from $554 (35d low) to a $785 peak on a record $48.5B backlog and 1.5x book-to-bill, pulling back to ~$745 with a forward P/E of ~57x. By those standards, FLEX's 35.5x forward P/E and AAON's 65.6x forward P/E represent the more moderate end of the cohort spectrum.
What the runway looks like from here
The earnings prints resolved the primary uncertainty — demand is real and accelerating — but introduced a new set of variables: margin recovery timelines at AAON, conversion of multi-billion backlogs at FLNC, tariff and supply-chain execution at FLEX, and DDOG's ability to sustain 30%+ growth against increasingly difficult year-over-year comparisons. The supply-constrained hyperscaler posture argues that backlog conversion risk is lower than in a demand-constrained cycle. But the second-tier names are no longer operating in valuation obscurity — each has now been discovered, priced, and partially re-rated toward its Tier-1 peers. The question of remaining runway is primarily an execution question, not a demand question.