

AAON, FLEX, DDOG: Post-Earnings Re-Rating or Lasting Runway?
Prompt v1.0
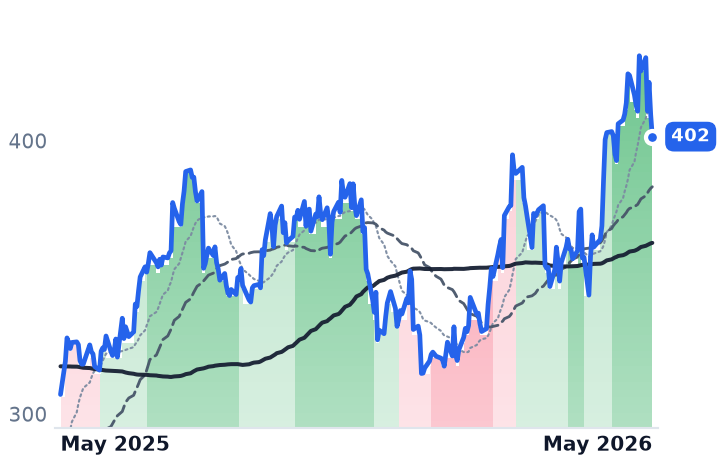
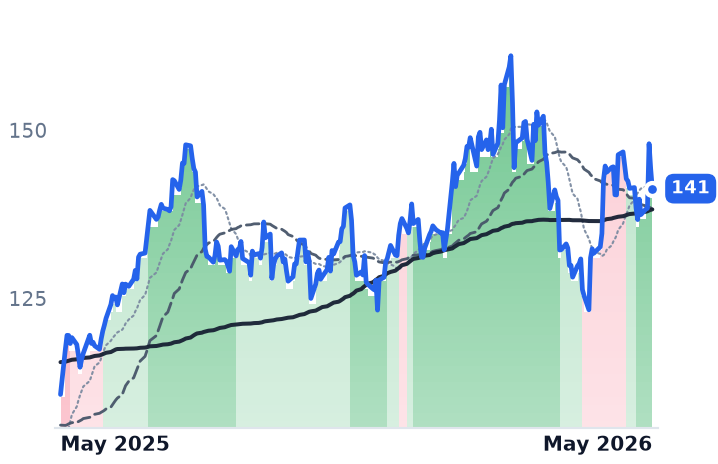
All three names surged 30–50% on May 7–8 earnings beats, not from gradual buildout momentum — the moves are post-earnings re-ratings driven by a confirmed $725B+ hyperscaler capex cycle. At current prices, FLEX carries the most identifiable residual upside via a SpinCo spin-off; AAON and DDOG are stretched on trailing multiples but carry strong forward order visibility.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
AAON | AAON | HVAC Systems | 🌱 Emerging Bull | +53.9% | +40.0% |
FLEX | Flex | Electronic Manufacturing Services | 🟢 Cont. Bull | +89.5% | +269.5% |
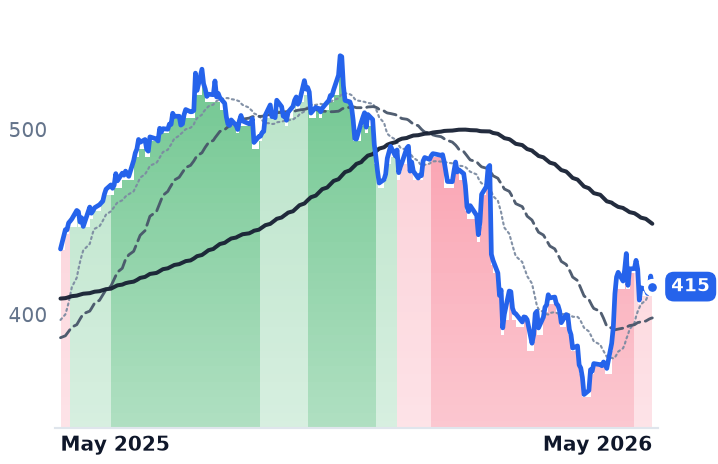
DDOG | Datadog | Data & Analytics Platforms | ⚠️ Emerging Bear | +83.7% | +85.5% |
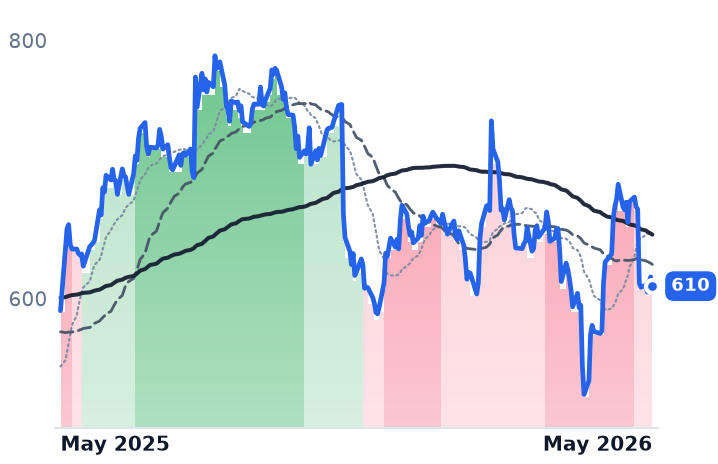
VRT | Vertiv | Data Center Power & Thermal | 🟢 Cont. Bull | +18.2% | +261.9% |
ETN | Eaton | Power & Propulsion Systems | 🟢 Cont. Bull | +0.3% | +30.7% |
EMR | Emerson Electric | Industrial Automation & Controls | 🟢 Cont. Bull | −2.3% | +27.6% |
MSFT | Microsoft | Cloud Infrastructure & Platforms | ⚠️ Emerging Bear | +11.3% | −4.7% |
META | Meta Platforms | Social Media & Messaging | ⚠️ Emerging Bear | −3.0% | +3.2% |
GOOGL | Alphabet | Search & Advertising | 🟢 Cont. Bull | +25.8% | +162.3% |
AMZN | Amazon.com | Online Marketplaces | ⚠️ Emerging Bear | +16.7% | +41.2% |
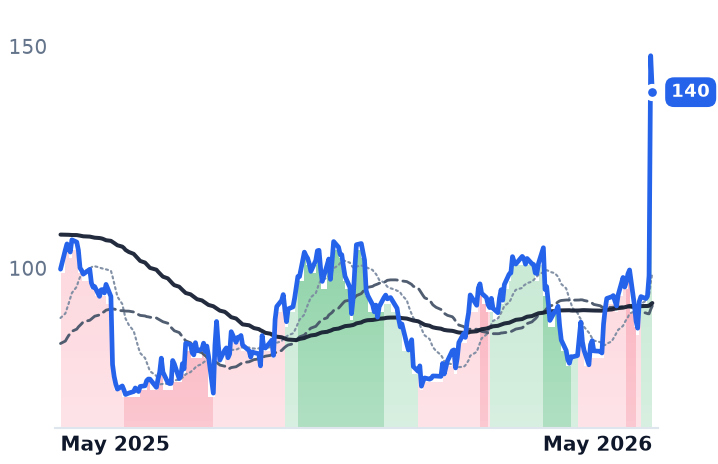
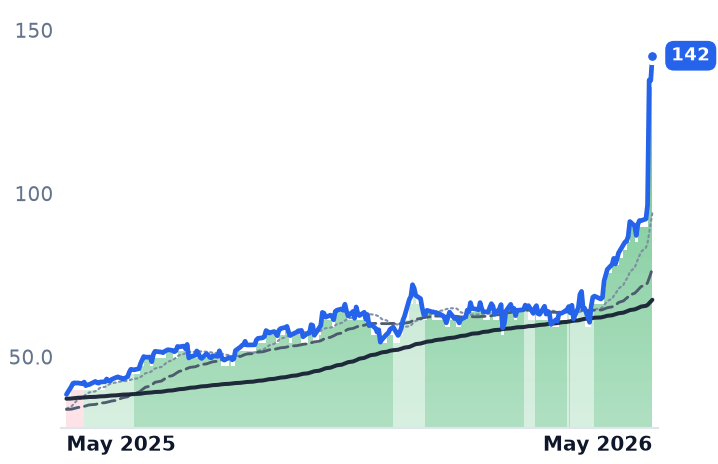
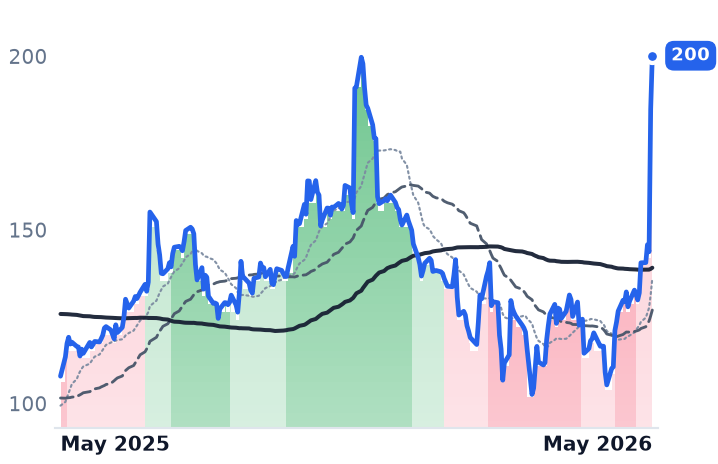
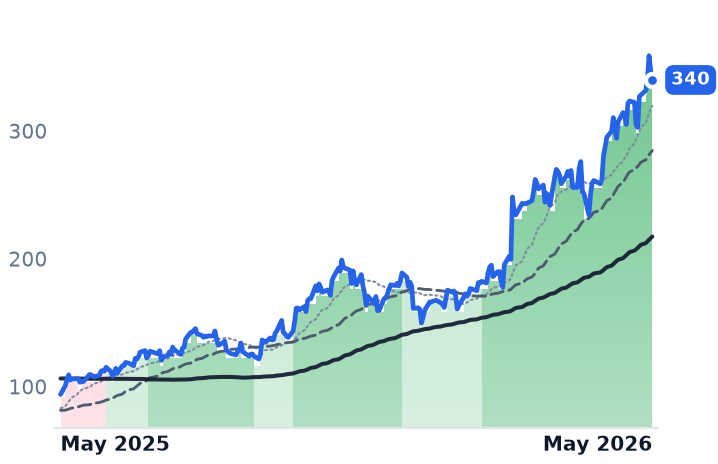
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AAON | $11.1B | 93.8x | 61.7x | 6.9x | 5.5x | 26.2x | 21.0x | 44.5x | -1.3% |
FLEX | $48.0B | 50.2x | 27.7x | 1.6x | 1.4x | 17.3x | 14.6x | 26.9x | 2.2% |
DDOG | $88.0B | 497.4x | 101.3x | 22.2x | 20.1x | 27.9x | 25.3x | 337.6x | 1.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
VRT | $142.5B | 91.1x | 57.7x | 13.1x | 10.3x | 36.3x | 28.5x | 61.1x | 1.6% |
ETN | $178.2B | 46.6x | 34.1x | 5.9x | 5.5x | 16.5x | 15.3x | 32.9x | 2.5% |
EMR | $74.5B | 30.5x | 20.5x | 4.1x | 4.0x | 7.7x | 7.5x | 16.7x | 4.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MSFT | $3.7T | 27.5x | 25.2x | 11.1x | 9.4x | 16.3x | 13.9x | 18.2x | 1.8% |
META | $1.5T | 21.9x | 18.4x | 6.6x | 5.9x | 8.1x | 7.2x | 14.9x | 2.7% |
GOOGL | $4.2T | 17.2x | 17.1x | 9.4x | 8.5x | 15.4x | 13.9x | 13.0x | 1.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AMZN | $2.8T | 20.8x | 22.4x | 3.6x | 3.4x | 7.2x | 6.7x | 11.7x | -0.4% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
AAON | Revenue | +44.5% | +15.1% | +21.9% |
| EPS | +55.9% | +53.8% | +35.7% | |
FLEX | Revenue | +6.8% | +26.3% | +30.0% |
| EPS | +24.2% | +44.7% | +51.5% | |
DDOG | Revenue | +28.9% | +21.5% | +23.5% |
| EPS | +20.9% | +17.3% | +23.1% | |
VRT | Revenue | +35.2% | +25.8% | +19.4% |
| EPS | +55.6% | +33.8% | +25.8% | |
ETN | Revenue | +18.5% | +10.9% | +8.9% |
| EPS | +11.6% | +18.3% | +16.9% | |
EMR | Revenue | +4.3% | +5.4% | +5.1% |
| EPS | +8.4% | +10.3% | +10.5% | |
MSFT | Revenue | +18.0% | +18.2% | +19.6% |
| EPS | +26.7% | +15.4% | +18.5% | |
META | Revenue | +27.3% | +19.9% | +17.9% |
| EPS | +39.6% | +7.2% | +15.8% | |
GOOGL | Revenue | +23.7% | +22.5% | +19.0% |
| EPS | +90.3% | −25.8% | +18.1% | |
AMZN | Revenue | +15.7% | +14.0% | +15.9% |
| EPS | +63.6% | −10.9% | +30.2% |
Forward fiscal years only. Blank means no analyst coverage for that year.
What Actually Happened
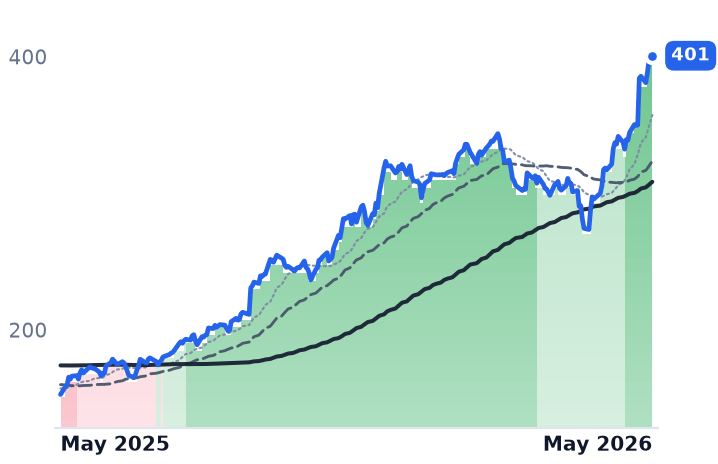
The framing of a 'gradual cohort breakout' doesn't survive a close look at the price data. AAON traded from ~$80 to $98 in the four weeks before May 7 — a 22% drift. Then it exploded roughly +50% in a single session on May 7, closing at $129.25 from a prior close of $98.30. Similarly, DDOG ranged $105–$145 through April before the May 7 earnings gap to $185, and FLEX ranged $80–$100 in mid-April before a May 5–6 gap to ~$134. This is a concentrated post-earnings re-rating event across all three names, not the multi-week band step-up the hypothesis anticipated.
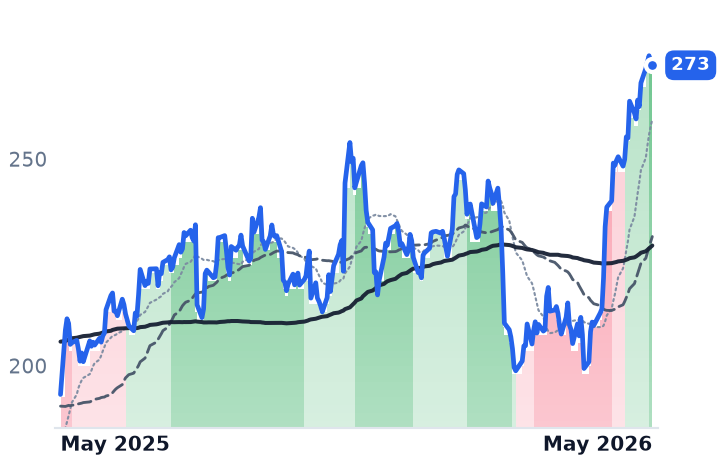
The catalyst is the same for all three: Big-4 hyperscalers collectively confirmed approximately $725 billion in 2026 capex, up ~64% from 2025's ~$443 billion — with Amazon at $200B, Google at $180–190B, Microsoft at ~$190B, and Meta at $125–145B, none showing moderation. Roughly 75% of that aggregate spend (~$545B) is directed at AI-specific infrastructure — GPUs, servers, data center construction, power systems, and cooling. Microsoft separately disclosed an $80 billion Azure backlog it cannot fulfill due to power constraints, confirming supply-side constraints as an ongoing demand driver for the exact products AAON and FLEX provide.
AAON: The Most Stretched, But the Deepest Backlog
AAON's BASX segment produced one of the most dramatic guidance resets of this earnings season. The company raised its 2026 revenue growth outlook to 40–45% (from prior guidance of 18–20%), implying roughly $1 billion in BASX-branded revenue for full-year 2026. The total company backlog reached $2.1 billion as of March 31 — the sixth consecutive record quarter — with BASX-specific backlog up 160% YoY and a book-to-bill above 2.0.
However, gross margins compressed to 25.1% in Q1 2026, down from 26.8% a year ago, and full-year gross margin guidance was cut to 27–28% from a prior 29–31%, reflecting outsourcing costs, Memphis facility ramp expenses, and tariff headwinds. Post-rally, AAON trades at a trailing P/E of ~89x, trailing EV/EBITDA of ~46x, and trailing P/S of ~6.5x. Forward P/E on FY2026 consensus ($1.97 EPS, $1.71B revenue) is approximately 65x. The balance sheet adds another consideration: AAON carries $425M in revolving credit with only $1.1M in cash and operating cash flow of $34M versus $52.9M in capex — 1.71x leverage that leaves limited cushion if the order book faces any air pocket.
FLEX: The Most Distinctive Risk/Reward
Flex reported Q4 FY2026 revenue of $7.48 billion, up 17% YoY, beating estimates by 7.6%, with adjusted EPS of $0.93 vs. $0.88 consensus. The structural catalyst is the planned tax-free spin-off of its Cloud and Power Infrastructure (CPI) unit into an independent public company, targeted for Q1 calendar 2027, with the SpinCo targeting 65–75% revenue growth in FY2027 and 80%+ in FY2028.
The CPI SpinCo is described as 'booked out' in capacity and backlog for the next couple of years, with CapEx of $1.4–$1.6 billion required in FY2027 — a deliberate investment cycle before normalizing. Flex's forward P/E is approximately 35x on FY2027 consensus EPS of ~$3.75, and trailing P/S is 1.75x — substantially cheaper than AAON or DDOG on a growth-adjusted basis. The sum-of-parts re-rating thesis is the clearest identifiable source of residual asymmetry in the cohort.
DDOG: Genuine Acceleration, Premium Valuation
Datadog reported Q1 2026 revenue of $1.01 billion, up 32% YoY, above the high end of guidance, with free cash flow of $289 million (29% margin) and a record sequential ARR addition. Crucially, the company landed 8-figure annualized GPU-monitoring deals with the AI research divisions of two major hyperscalers — the first meaningful proof of training-workload observability monetization. AI-native customers now number 6,500+, with 22 spending over $1M annually and 5 over $10M.
Guggenheim raised its price target to $225 following the guidance raise to $4.30–$4.34B full-year revenue. The May 7 surge of roughly 29–30% was supported by record new logo bookings (more than doubled YoY) and NRR in the low-120% range. Non-AI customer revenue also re-accelerated to mid-20% YoY growth, suggesting the story isn't purely AI-dependent. But at a trailing P/E near 484x, trailing EV/EBITDA of ~386x, and trailing P/S of ~18x, the multiple demands continued estimate raises to sustain the current price level.
Runway Check: What's Left?
| Name | Forward P/E | Key Upside Driver | Key Risk |
|---|---|---|---|
| AAON | ~65x | $2.1B backlog, BASX ramp | Margin compression, leverage |
| FLEX | ~35x | SpinCo sum-of-parts | CapEx cycle dilution pre-spin |
| DDOG | ~86x | Training-workload monetization | Multiple requires ongoing beats |
The hyperscaler capex story is unambiguously reaffirmed for 2026 and beyond. The demand environment for all three businesses is real and growing. However, the entry point that defined the hypothesis's asymmetry — the pre-earnings price — has passed. Whether current prices still carry 15–30% headroom is stock-specific: FLEX's SpinCo introduction creates a structural re-rating path not yet in consensus; AAON's backlog depth supports the revenue line even if margins are under pressure; DDOG's monetization of training workloads is a new vector but demands near-flawless execution at current multiples.