

AI2 Mid-Tier Silicon Photonics & Packaging: Who Has Room to Run?
Prompt v1.0
Among the quieter AI2-tagged optical/packaging names, ONTO and MCHP offer the cleanest intact setups with confirmed catalysts and sell-side upside remaining. COHR and ACLS are extended — COHR past consensus targets with 22 insider sales and ACLS in blowoff territory well above analyst PTs. CRDO's parabolic 69% run leaves only thin median upside, though high-conviction bulls see 40%+. FN and AEIS are trend-intact but momentum is decelerating near consensus ceilings.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
ONTO | Onto Innovation | Semiconduct Equipment | 🌱 Emerging Bull | +15.3% | +221.7% |
MCHP | Microchip Technology Incorporated | Analog & Mixed-Signal | 🟢 Cont. Bull | +39.1% | +84.4% |
FN | Fabrinet | Specialty Manufacturing & Components | 🟢 Cont. Bull | +0.5% | +206.6% |
COHR | Coherent | Instrumentation & Test Equipment | 🟢 Cont. Bull | +18.0% | +375.1% |
ACLS | Axcelis Technologies | Semiconduct Equipment | 🟢 Cont. Bull | +50.6% | +182.7% |
CRDO | Credo Technology | Optical Transport & Switching | ⚠️ Emerging Bear | +74.7% | +271.1% |
FORM | FormFactor | Process Control & Metrology | 🟢 Cont. Bull | +22.1% | +396.2% |
AEIS | Advanced Energy Industries | Data Center Power & Thermal | 🟢 Cont. Bull | −4.7% | +217.7% |
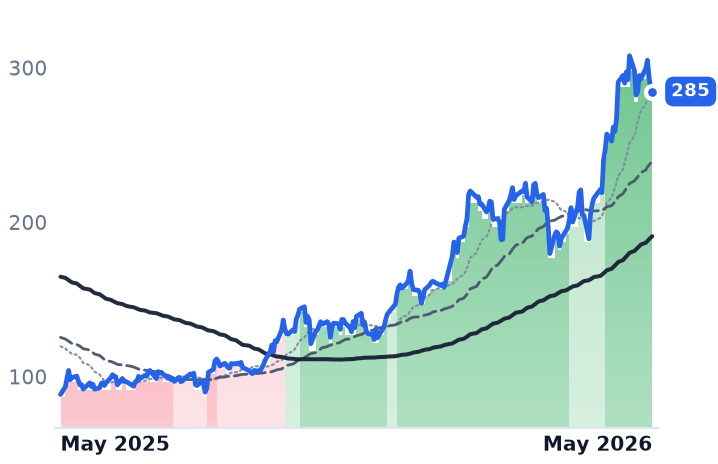
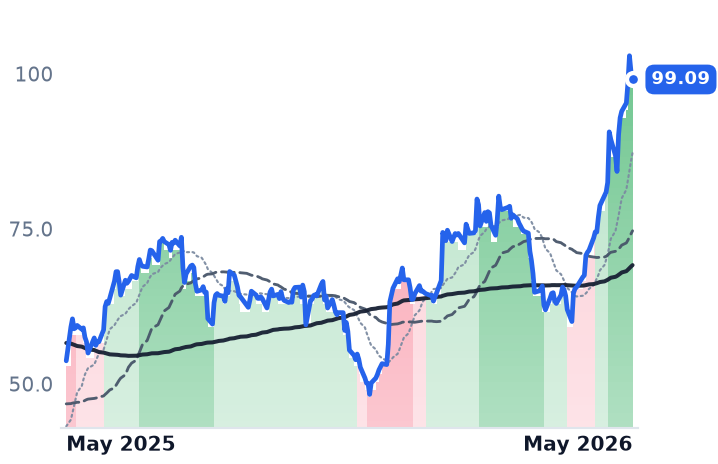
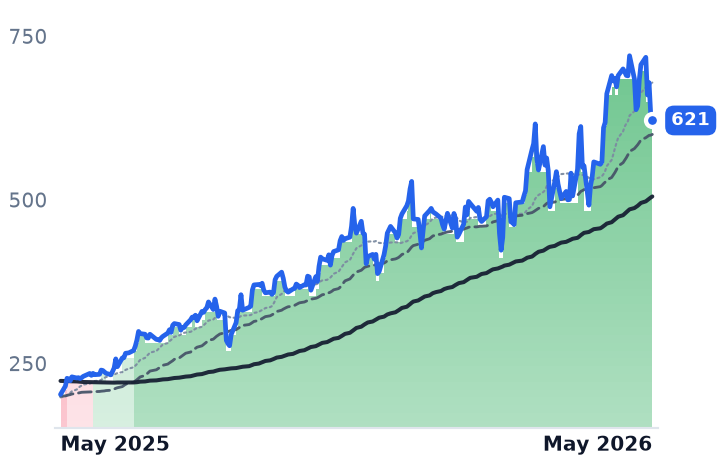
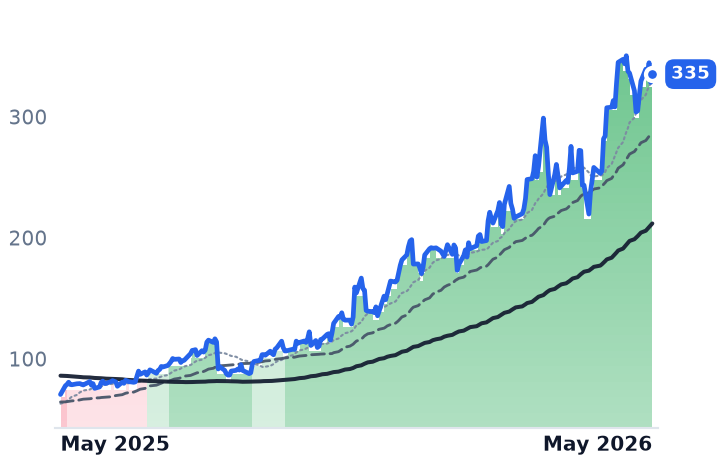
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ONTO | $17.5B | 130.5x | 48.8x | 15.6x | 13.0x | 31.0x | 25.8x | 66.8x | 1.4% |
MCHP | $42.5B | 108.3x | 24.5x | 8.3x | 6.8x | 13.8x | 11.3x | 28.2x | 2.6% |
FN | $20.4B | 48.5x | 33.1x | 4.8x | 3.6x | 40.3x | 30.0x | 39.3x | 0.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
COHR | $68.7B | 80.7x | 42.0x | 9.7x | 7.1x | 25.7x | 18.9x | 53.7x | -85.8% |
ACLS | $4.4B | 48.0x | 37.6x | 5.1x | 5.2x | 11.9x | 12.2x | 33.8x | 1.5% |
CRDO | $52.7B | 107.9x | 46.2x | 39.5x | 21.6x | 58.1x | 31.8x | 101.1x | 0.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FORM | $9.8B | 143.8x | 51.5x | 11.7x | 10.2x | 27.8x | 24.3x | 64.2x | 0.4% |
AEIS | $12.3B | 64.0x | 34.7x | 6.5x | 5.5x | 16.7x | 14.2x | 45.6x | 0.6% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
ONTO | Revenue | +2.2% | +33.5% | +23.2% |
| EPS | −5.1% | +44.8% | +35.6% | |
MCHP | Revenue | +6.2% | +33.3% | +16.1% |
| EPS | +20.7% | +103.7% | +31.1% | |
FN | Revenue | +35.6% | +23.6% | +21.3% |
| EPS | +36.0% | +24.7% | +24.0% | |
COHR | Revenue | +21.9% | +37.7% | +38.2% |
| EPS | +55.9% | +53.4% | +58.4% | |
ACLS | Revenue | +3.5% | +9.6% | +20.0% |
| EPS | −14.8% | +26.4% | +41.7% | |
CRDO | Revenue | +211.9% | +83.3% | +49.4% |
| EPS | +423.2% | +85.0% | +47.8% | |
FORM | Revenue | +23.5% | +15.3% | −0.4% |
| EPS | +117.3% | +24.7% | −5.6% | |
AEIS | Revenue | +25.2% | +16.8% | +9.9% |
| EPS | +49.1% | +26.1% | +11.4% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The Tier Map: Who's Extended, Who's Not
The AI2 mid-tier has been quietly compounding while the parabolic first-tier names (LITE, AAOI, SNDK) captured headlines. A systematic screen of FN, CRDO, COHR, MCHP, ACLS, ONTO, FORM, and AEIS reveals sharp differentiation: two names still have confirmed catalysts plus sell-side room to run, two are textbook extended/exhaustion setups, and the rest fall in a muddier middle.
ONTO: Cleanest Intact Setup
Onto Innovation stands out as the most structurally sound: a well-formed +36.5% 90-day gain in a rising-low pattern, Q1 FY26 revenue of $292M (+9.5% YoY) ahead of guidance, and a Dragonfly G5 commercial qualification at a leading 2.5D logic customer with shipments ahead of plan. Management guided FY26 revenue >$1.3B (>30% growth), and the company holds a $240M+ volume purchase agreement from a leading HBM memory customer through 2027. Needham raised their price target to $330 with a Buy rating, while Oppenheimer and Jefferies sit at $350 — versus a current price near $284, implying up to 23% upside to the highest credible targets. A Rigaku X-ray partnership (27% stake for $710M) adds sub-1nm metrology optionality not yet priced into 2026 estimates. The strongly bullish SMA signal has been continuous across the full 90-day window.
MCHP: Recovery Intact, Upgrade Cycle Underway
Microchip Technology's +30.4% 90-day gain is partially a deep-inventory-correction bounce, but the forward catalyst is real: the industry's first 3nm PCIe Gen 6 switch (Switchtec) with initial production expected June 2026 and volume ramp in H2 2026. Citigroup raised its price target to $113 (from $91) on May 8, maintaining Buy, implying ~14% upside from the ~$99–$101 current price. The key overhang is well-documented: $1.095B in inventory (~199 days), underutilization charges running ~$51M/quarter, and inventory write-offs ~$71.8M/quarter compressing reported gross margins to the 57–59% range vs. an underlying product gross margin near 67%. The path to normalized 65%+ margins is 3–4 more quarters out. For investors focused on the trend, momentum has re-accelerated and the PCIe Gen 6 design-win cycle is a confirmed hyperscaler-adjacent catalyst.
FN: Trend Intact, But Ceiling Approaching
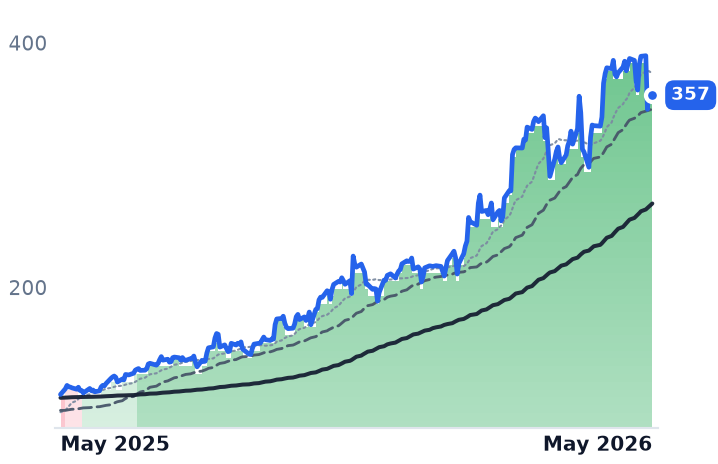
Fabrinet delivered record Q3 FY26 revenue of $1.214B (+39.3% YoY), beat EPS by $0.14, and guided Q4 to $1.25B–$1.29B. The HPC ramp surged from $15M to $86M sequentially, and three CPO programs with distinct customers are active. Rosenblatt raised its price target to $750 post-earnings, with Northland at $800, but median consensus sits at $544–$661 versus a current ~$621 price — meaning most analysts are at or below current levels. The 30-day momentum has flattened to just +1.8%, signaling deceleration. FN remains in strongly bullish for 11 consecutive months, but the room-to-run gate (>15% to consensus median) is not cleared at current prices without relying on high-conviction outlier targets.
COHR: Fundamental Inflection, Valuation Extended
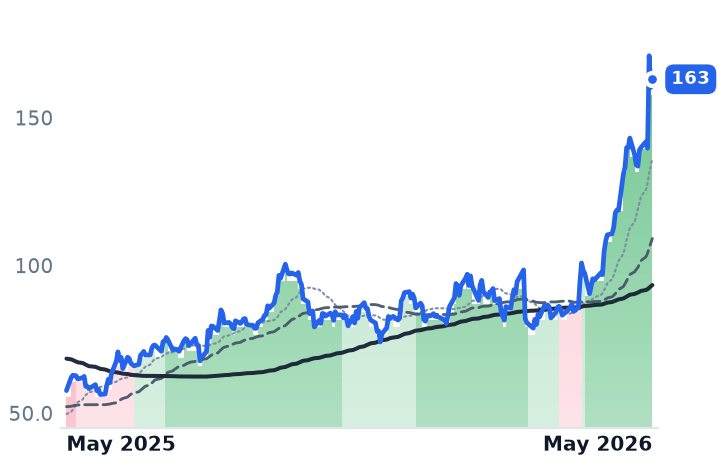
Coherent's fundamentals are undeniably strong: Q3 FY26 revenue of $1.806B (+27% YoY) beat consensus, and the company guided Q4 to $1.91B–$2.05B. Most importantly, NVIDIA took a $2B equity stake and signed a multiyear CPO supply agreement, with management calling CPO a >$15B incremental TAM. Stifel raised its price target to $420, citing InP capacity coming online ahead of schedule and CPO revenue beginning H2 CY2026. Despite all this, the stock's 47% 90-day run to ~$335 already sits at or slightly above the $330–$334 median consensus PT — and 22 insider transactions over the past six months were all sales (0 purchases), including Bain Capital offloading 7.5M shares. The distribution pattern at or above consensus PT is a meaningful disconfirming signal.
ACLS: Blowoff Pattern, PT Already Breached
Axcelis has surged +89% over 90 days and +55.8% in the last 30 days alone, printing a vertical spike to $171 on May 6 from ~$140 in late April. The fundamental story has merit — the Purion H6 high-current implanter is positioned for HBM4 DRAM demand, and the pending $4.4B all-stock merger with Veeco (both shareholder approvals secured, awaiting China SAMR clearance expected H2 2026) creates the 4th largest US WFE supplier with $35M+ in targeted synergies. However, ACLS's HBM4 positioning via the Purion H6 and the combined Axcelis-Veeco implant/anneal expertise is acknowledged as compelling, yet sell-side PTs of $91 (B.Riley) and $100 (BofA) sit dramatically below the current ~$163 price. Q1 FY26 operating income fell -72.7% YoY. The blowoff spike pattern matches the disconfirming criteria from the hypothesis exactly.
FORM and AEIS: Priced-for-Perfection Outliers
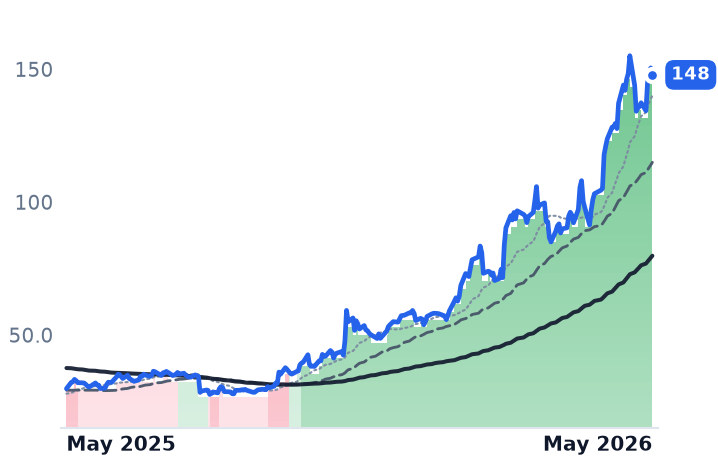
FormFactor's analyst consensus is Hold with a median PT of ~$133 versus a current ~$148 price — a PT-breached setup with forward GAAP P/E exceeding 130x and zero Buy ratings from the six analysts covering it. AEIS (Advanced Energy Industries) has delivered +30.7% over 90 days in a continuous strongly bullish SMA signal but trades at ~93x trailing P/E with the prior analysis note flagging valuation as stretched. Both are momentum-confirmed but consensus-ceiling-limited.
CRDO: High-Conviction Story, But the Move Has Happened
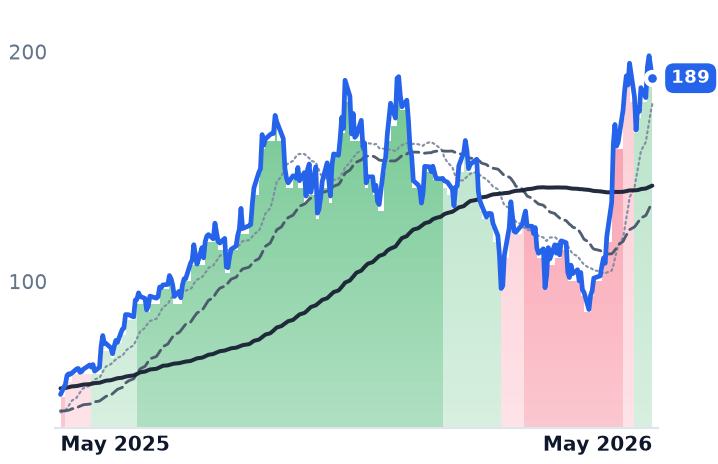
Credo Technology's +201% YoY revenue growth and $750M DustPhotonics silicon-photonics acquisition are genuine. But the stock's 69% 90-day gain was heavily catalyzed by a single +18% session on the acquisition announcement, and median consensus PT sits at ~$200 versus a current ~$188 — only ~9–15% median upside, barely clearing the >15% gate and only comfortably so at the $260 high-conviction outlier target. Trailing P/E ~98x and ~$52.95M in insider selling last quarter are material disconfirming signals. The trend signal only flipped from strongly bearish back to mildly bullish as of early May, meaning the new uptrend is in early confirmation stages.